

London watchdog’s name-and-shame plan is mad, bad and dangerous to the City
The UK regulator’s attempt to increase the transparency of its investigations has prompted a storm of protest
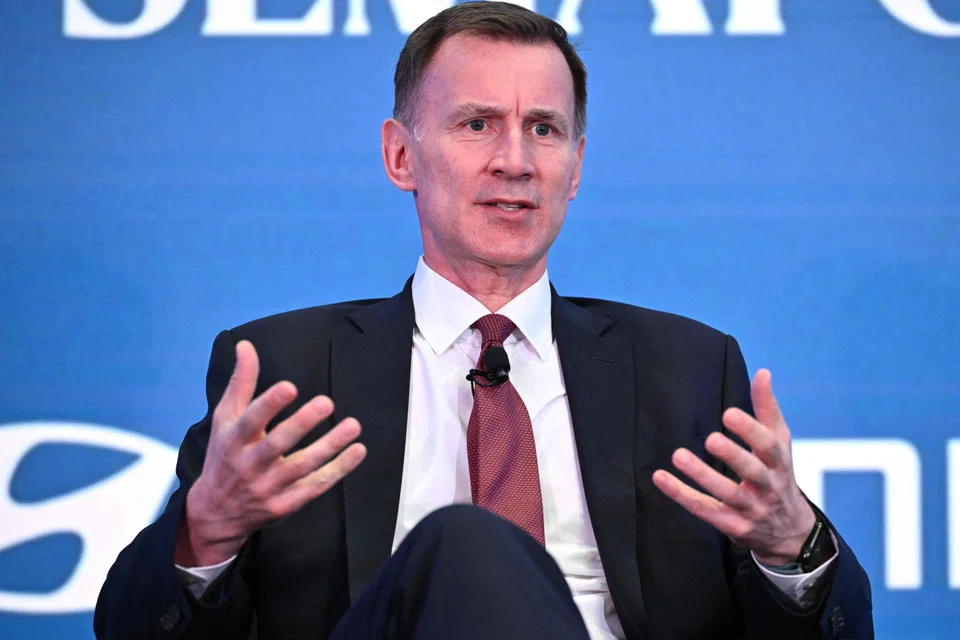
THE United Kingdom’s Financial Conduct Authority (FCA), the principal financial services watchdog, has got itself in a spot of bother over proposals to “name and shame” financial services firms at the beginning, rather than the conclusion, of any investigation. It needs to rapidly revise its thinking, or risk damaging the City’s standing even further.
The regulator has succeeded in uniting opposition from the entire financial sector, with at least 16 industry bodies, including UK Finance and the City of London Corporation, asserting their view in a letter to Chancellor of the Exchequer Jeremy Hunt that the suggestion breaches principles of basic fairness.
If the FCA doesn’t backtrack, he needs to intervene – otherwise the UK will move out of step with other global regulators by holding UK firms to overly stringent oversight. It could leave efforts to revive the City in tatters.
Removing roadblocks
The whole point of the government’s recent Edinburgh reforms is to remove roadblocks that hamper the financial services industry, the UK’s most important export sector, and restore some dynamism.
This latest regulatory land grab just doesn’t seem very well thought out – and will require heavy revision to become workable in the real world. No one opposes the FCA’s efforts to weed out bad actors, but this isn’t the way to achieve that aim.
“By being more transparent when we open and close cases, we can enhance public confidence by showing that we are on the case”, is the FCA’s rationale for the change it proposed in February, starting a consultation period that ended earlier this week.
Not all new cases will be revealed upfront; instead, the regulator says that it will decide when publicity serves the “public interest”. That sounds like the kind of lottery likely to deter firms looking to start businesses or expand in the UK.
The FCA is independent of government and is entitled to make its own rules, although it’s nominally held to account by several parliamentary committees. It’s unclear when it will make a final decision, but a compromise that adopts industry input would be prudent.
The House of Lords Financial Services Regulation Committee says that the proposed change “risks the overall integrity of the market”.
UK Finance, which is leading the response, points out that these proposals create a more stringent regime in the UK than in any other major country.
Out of 26 comparable systems, the FCA can cite some similarities only with South Africa and Singapore – but in both those countries such powers are used in exceptional circumstances, an option that already exists in the UK.
The proposals appear designed to defend the FCA from previous criticisms over how long it takes to bring investigations to a conclusion, as well as its relatively low success rate.
Cases that settle take on average a little over three years, with those that don’t conclude dragging on for upwards of five years.
Only a third of as many as 200 annual investigations lead to any action, with less than a fifth entailing enforcement. There are presently 500 investigations under way.
Everyone wants a tough but fair regulator – not just a Robocop. But there’s no insight on how identifying the accused at the beginning of the process will improve this dismal record.
Innocent until proven guilty
In fairness to the FCA, it’s clear something needs to change, and it understandably wants deterrence to work earlier in the process rather than after years of legal wrangling.
But it needs the support of the industry, rather than just focusing on making its own life easier – otherwise suspicion will mount that the real objective is to transform towards a US-style system of quicker settlements accompanied by much bigger fines.
Sensible widespread requests for a proper cost-benefit analysis have been rejected as “not required”.
Yet the FCA’s limited analysis of the share-price effect on companies investigated appears to gloss over wider impacts, such as potential loss of business and reputation. A future regime of increased aggression isn’t comparable with historical cases.
Furthermore, the FCA’s riposte that firms often disclose they’re under investigation rather misses the point that most public-listed entities are required by law to do so when presenting accounts.
Individuals won’t be named; English defamation law strongly protects personal privacy by putting the burden of proof on the accuser. But this affords little comfort, as often it will be obvious to work out those involved.
As the ethos of justice is innocence until proven guilty, then surely that should apply to companies as well. A “no smoke without fire” presumption of guilt can build rapidly. This won’t be the FCA’s intention, but the risks of contagion for others in related businesses could prove unavoidable.
Mission creep is an insidious affliction that permeates many governmental organisations. Regulators’ ambitions need to be kept firmly in tandem with the industries they oversee. After all, who will guard the guards themselves?
TRENDING NOW
Chairman’s role in spotlight with raft of proposed new rules for Singapore boards
Director of PR firm sacked for secretly recording internal meeting loses wrongful dismissal claim

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status

If Europe goes to war, the fallout will be felt in East Asia

