

No winners in a trade war: US cannot continue to grow if its trading partners shrink
Economists estimate the impact of the likely tariffs so far would add half a percentage point to US consumer inflation this year
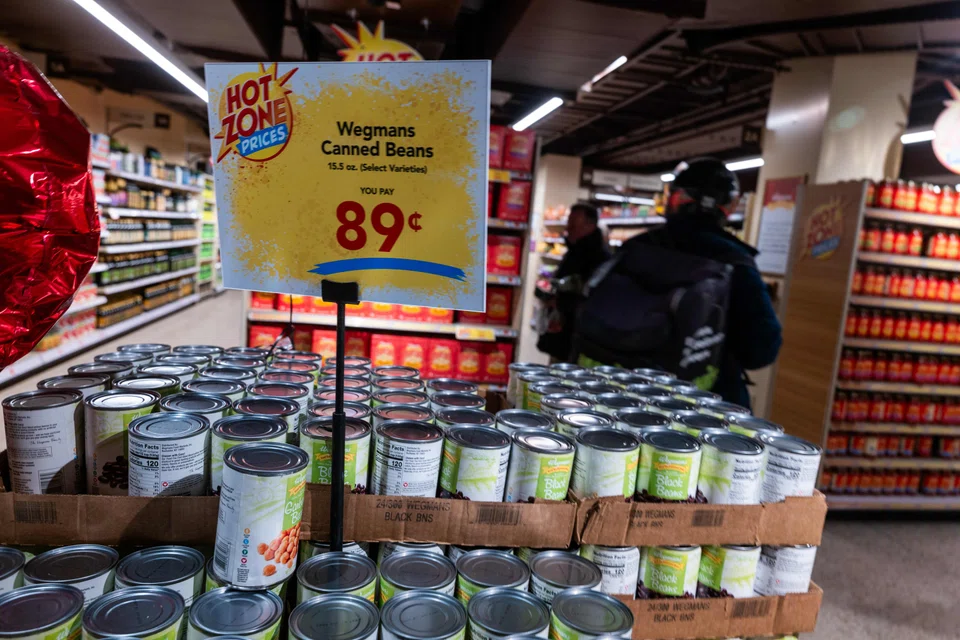
THE US consumer’s pocketbook and the bull market in stocks could be the first casualties of President Donald Trump’s trade war.
Former Treasury secretary Larry Summers summed up this risk in no uncertain terms when he described Trump’s warning to the world as: “Stop, or I’ll shoot myself in the foot”. The best that can be said of the protectionist policies is that they artificially preserve jobs in heavy industries in the United States.
In a surprising move to this end, Trump imposed an additional 25 per cent tariffs on all imports of two vital industrial metals – steel and aluminium. The Economist called the metals tariffs “an act of self-harm” because they would drive up the costs of consumer goods and splinter already-delicate supply chains.
As anticipated, Trump has also imposed tariffs on all Chinese imports, escalating a trade war that was mostly contained to the technology sector during the administration of former president Joe Biden.
The US does not have the capacity to replace all imports, and exporters will have no choice but to raise prices in order to cover their tariff costs. Even if American manufacturers started to purchase the majority of their metals from US foundries, the cost of production there would inevitably be higher.
In a trade war, there are no winners. Indeed, the prolonged slowdown in global economic activity in the 1930s is sometimes attributed to a trade war during that era, motivated by some of the same nativist instincts present today.
The US economy has been more resilient than those in Europe and China during the last two years, but, in the intertwined global economy, the US cannot continue to grow if its trading partners continue to shrink.
Effect on inflation
The more worrying impact of Trump’s trade policy for the stock market could be the effect of tariffs on inflation rather than economic growth.
The tariffs themselves are not yet drastically large. So far, the Trump administration has raised tariffs on all Chinese imports by 10 per cent, in addition to the metals tariffs. Proposed tariffs include those to be levied on Canadian and Mexican imports, and reciprocal duties on exporters that charge tariffs on their imports from the US.
Economists at brokerage Goldman Sachs Group estimated that the impact of the likely tariffs so far would add half a percentage point to consumer inflation this year. By the Wall Street brokerage’s reckoning, that would bring year-end inflation to a 2.6 per cent level.
The inflationary effects are likely to be immediate. The price of one of the most important consumer products in the US – automobiles – depends on cheap imports of metal.
The Telsey Advisory Group, a brokerage that concentrates on retail and consumer-services businesses, estimates that the tariffs will generate additional costs of US$830 to US$1,200 per household in 2025. For Black-American householders, that would represent about 2 per cent of the median income.
Economists differ on whether tariff-related inflation can change the trajectory of consumer prices.
“Brace for second-round effects from tariffs on the consumer price index (CPI),” warned economists at brokerage BNP Paribas, in a note to clients. Tariffs, they argued, act like a “supply shock”.
“Tariffs, and supply shocks in general, do not happen in a vacuum,” they wrote. “They interact with current pricing dynamics and can trigger persistent (inflation).”
The end user, in BNP Paribas’ view, always pays the tariff.
Many factors at play
One hope is that movements in the US dollar mute the inflationary impact. The movement of the greenback against the Canadian dollar in the last six months could mean that the net effect of a 10 per cent tariff (on imported energy resources from Canada) is negligible on the price in US dollars, said veteran Wall Street strategist Jim Paulsen.
The BNP Paribas economists warned that this offset may not be lasting, however, because the role of the US dollar as the world’s reserve currency means that its value is constantly shifting for a host of reasons.
There are plenty of dynamics for the tariffs to interact with. Inflation is on the march in the US once more, a fact that triggered a sell-off early on Wednesday (Feb 12).
In January, the US CPI rose 3 per cent from a year earlier, reversing recent progress towards the Federal Reserve’s 2 per cent target.
It is still nowhere near the peak inflation levels of 2022, but it’s enough to make the Fed abandon its rate-cutting cycle. An untimely chicken pandemic has already made eggs a precious commodity on the shelves of many US grocery stores.
Indeed, strategists at brokerage Bank of America Global Research recently pronounced the rate-cut cycle officially dead, killed by stubborn inflation. In his testimony before the US Congress earlier this week, Fed chairman Jerome Powell said that the trend of consumer prices is close to, but not quite where the central bank wants it.
He has consistently warned that the central bank is watching for the impact of tariffs and other fiscal policies before it makes another policy move.
Trump’s calculation appears to be that the disproportionate importance of the US as an export market gives him more leverage over his trading partners than their leaders have over him.
The uncountable factor in such trade wars, however, is national pride. It might not make economic sense for Canada or China to hold out against Trump’s tariff-cudgelling. But an aggressive response could still be as popular a policy among Canadian or Chinese voters as Trump’s aggression appears to be with his base voters.
The most US-focused major stock index, the small-cap Russell 2000, is more or less flat for the year to date and since the presidential election in November. If inflation returns with a vengeance, the lacklustre performance could presage a major sell-off.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Asean’s challenge is to become resilient against global geopolitics: former Indonesia trade minister

