

Singapore’s new data centres must use renewables. Can they overcome the hurdles?
The upcoming facilities on Jurong Island may be small in capacity, but have a chance to test new frontiers
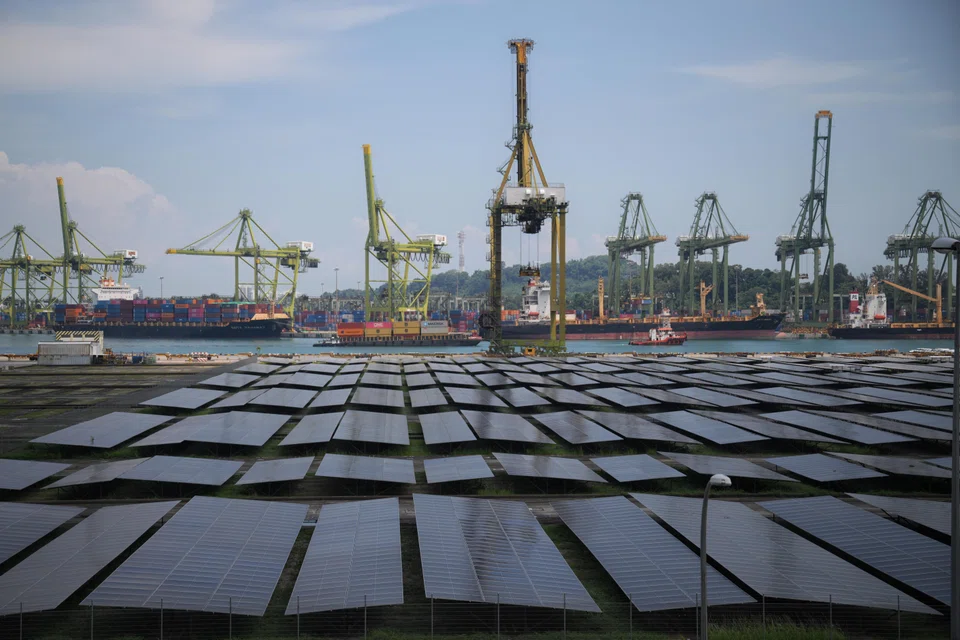
[SINGAPORE] The latest crop of data-centre operators awarded capacity in Singapore face a crucial test: whether they can break existing barriers to clean energy adoption – from price uncertainty to supply bottlenecks – and pave the way for the rest of the industry.
On Aug 21, Singapore awarded 200 megawatts (MW) of data-centre capacity to four operators: 50 MW each to Equinix, Digital Realty, Keppel Data Centres and ST Telemedia Global Data Centres for new facilities on Jurong Island.
This was part of Singapore’s second Data Centre-Call For Application tender (DC-CFA2), which stipulated that facilities must be at least 50 per cent powered by “eligible green energy pathways”.
Such a requirement came amid persistent concerns over data centres’ energy footprint.
In a recent survey by the Sustainable Energy Association of Singapore, increased pressure on energy supply and infrastructure was the most cited impact of data-centre growth on the Republic’s energy sector by 2030.
As The Business Times has previously reported, clean energy and data centres make for a “tricky marriage”, with the lack of standardised power-purchase agreements and financing challenges.
Challenges exist for all options
The DC-CFA2 tender cited several examples of green pathways that data centres could adopt: vertical solar panels integrated into buildings, biomethane, low-carbon ammonia or hydrogen, and fuel cells with carbon capture and storage technologies.
Solar power is an economical option, with prices having crashed in recent years. But its output is weather-dependent and limited by Singapore’s high cloud cover.
The other clean energy options come with cost and supply chain challenges, but can be game-changers if data centres crack the puzzle.
Biomethane may be the lowest-hanging fruit after solar power. The renewable fuel is typically derived from biogas, which is in turn produced from organic matter such as agricultural waste.
This is a promising option. South-east Asia is abundant in waste from the palm oil and other agricultural sectors.
That waste could serve as the raw material for biomethane production.
Biomethane is also compatible with existing natural gas plants, without the need for infrastructural upgrades.
But the supply chain is still nascent. Biomethane represents only 0.01 per cent of South-east Asia’s gas supply, and can cost up to twice as much as fossil natural gas, going by an industry estimate.
Singapore has taken steps to tackle this constraint. In October 2025, it set up a sandbox for biomethane imports to catalyse supply chain development and facilitate adoption.
Data centres’ ability to tap this fuel could be a key breakthrough to the adoption of biomethane.
The other pathways cited in the tender are yet more challenging.
Low-carbon hydrogen – produced using renewable energy – can on average cost three times as much as “grey” hydrogen made using natural gas, 2023 data from research outfit BloombergNEF showed.
Carbon capture and storage, meanwhile, remains untested territory in this region, with high costs and complex logistics.
The awardees of DC-CFA2, however, have an opportunity to begin exploring these possibilities and mapping out the steps needed.
There is also the chance to lay out new best practices for the industry in green-power procurement.
Facilities of up to 50 MW will be smaller than hyperscale facilities that operate at the gigawatt level, but they are a promising start towards bigger strides of progress in the Republic’s use of new renewable sources.
TRENDING NOW

Government to bring forward raising of retirement age, give employers more financial support to create flexi-load jobs

If Europe goes to war, the fallout will be felt in East Asia

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status

Vietnam’s northern provinces, not Hanoi or Ho Chi Minh City, are powering near 10% GDP growth

