Is Stoneweg Europe Stapled Trust’s manager-internalisation deal the key to reviving S-Reits?
Some view manager-internalisation as a ‘nuclear option’, but Sert is demonstrating that it is also a constructive growth-oriented strategy
[SINGAPORE] When Stoneweg Europe Stapled Trust (Sert) flagged in August that the internalisation of its managers was on the cards, this column warned that the move might alienate minority investors and do little to boost the market valuation of its stapled securities.
Sert is not just acquiring the managers of its own assets, though. On Sep 28, it was revealed that Sert plans to acquire its sponsor’s pan-European logistics and light-industrial platform – which manages Sert’s 2.3 billion euro (US$2.6 billion) portfolio, as well as a further 820 million euros worth of third-party assets across 11 mandates.
Sert’s managers were circumspect about the significance of these third-party mandates in their comments on the deal last week. They said the mandates are not a standalone growth business but a means for its local teams across Europe to maintain market relationships and create potential future co-investment and acquisition opportunities for Sert.
The caution is understandable, given the potentially volatile revenue contributions from these third-party mandates and the current scrutiny of Sert’s manager-internalisation exercise.
Yet, once the transaction is completed, these third-party mandates may become a more significant element of Sert’s growth story – and reshape some popular narratives around manager-internalisation initiatives in the Singapore market.
While the merits of internalising the manager of Singapore-listed real estate investment trusts (S-Reits) are often premised entirely on the elimination of external management fees and enhancement of manager accountability, Sert is framing its manager-internalisation proposal partly as an acquisition of institutional capabilities that may support its future growth.
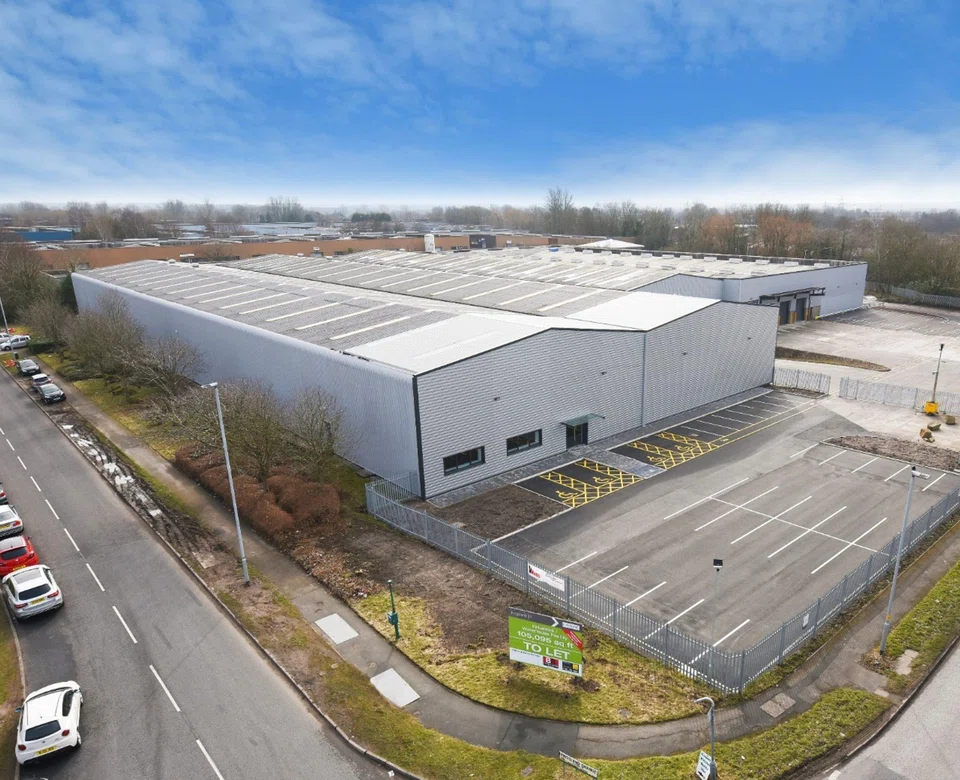
Sert’s managers said last week that the deal will bring in-house approximately 100 employees across 10 European jurisdictions and Singapore. These employees manage 96 properties with more than 1.6 million square metres of lettable area owned by the Reit, and a further 46 assets with 618,000 sq m of lettable area held by third parties.
“Combined, these capabilities create a fully integrated European logistics and digital infrastructure growth platform that combines recurring property income, asset management earnings and future growth opportunities within a single listed structure,” Sert’s managers said in a statement.
Redefined sponsor relationship
Sert’s expanded capabilities will redefine its relationship with its sponsor SWI Group, of course.
Under the deal, SWI Group will sell its pan-European logistics and light-industrial platform to Sert for 114 million euros. Sert will pay 80 million euros through the issue of 40 million stapled securities priced at two euros each, and the remaining 34 million euros in cash.
Sert may pay a further 8.4 million euros to its sponsor for a number of co-investment stakes in properties linked to third-party asset management contracts.
The issue of the new stapled securities will increase SWI Group’s interest in Sert from 28.2 per cent to 33 per cent.
Sert’s subsequent interaction with SWI Group will be regulated by two “strategic cooperation” agreements. The first of these gives Sert exclusive rights within the entire SWI Group to operate in the logistics and light-industrial property sector across Europe.
The agreement also caps any fees that may be payable if SWI Group refers opportunities within the sector to Sert. For instance, finder’s fees will be capped at 1 per cent of the acquisition price while capital partner introduction fees will be capped at 2 per cent of equity deployed.
The other strategic cooperation agreement provides a framework for Sert to continue tapping SWI Group’s capabilities in the data centre space on a non-exclusive basis. In this field, development management fees will be capped at 2.25 per cent of development cost, while combined development and technical project management fees will be capped at 3.75 per cent.
On the face of it, Sert’s manager-internalisation exercise will probably not completely halt the flow of fees to its sponsor.
Sert is aiming to increase its data centre exposure from 7.2 per cent at the end of H1 2026 to between 15 per cent and 25 per cent by 2028. It is also trying to build up its exposure to logistics and light-industrial assets from 55.7 per cent to as much as 70 per cent.
Value accretive deal
Nevertheless, the manager-internalisation exercise will probably be value accretive for investors, judging from the financial information Sert’s managers provided last week.
For starters, the 114 million euro price tag for the management platform that Sert is acquiring from SWI Group is 14.4 per cent below the mid-point of an independent valuation range.
The “maximum purchase consideration” of 122.4 million euros (which includes the additional 8.4 million euros payment for the co-investments linked to third-party asset management contracts) is 13.3 per cent below the mid-point of an independent valuation range.
The stapled securities Sert is issuing to SWI Group are also being priced 30 per cent above their current market price of 1.5 euros, and close to Sert’s recent net asset value (NAV) of 2.02 euros per share. This should keep Sert’s relatively high gearing of 41.9 per cent in check, and limit the dilutive impact on minority investors.
On a pro forma basis, the deal would have been 5.9 per cent accretive to Sert’s 2025 distribution per stapled security.
Meanwhile, Sert’s stapled securities are not richly priced. At the end of last week, they were trading at a H1 2026 annualised yield of 8.9 per cent, and just 0.74 times NAV.
Will investors back the manager-internalisation proposal Sert unveiled last week? Could Sert be on the brink of a sustained market re-rating?
S-Reit revitalisation playbook?
For many local market watchers, manager-internalisation is often viewed as the “nuclear option” – a desperate last resort to unseat errant sponsors and rescue persistently underperforming S-Reits.
Sert’s proposal may turn that narrative on its head. By subsuming a well-established management platform with active third-party mandates, and carefully recalibrating its relationship with its sponsor, Sert is demonstrating that manager-internalisation can be a constructive, growth-oriented strategy.
If successfully executed, this transaction could provide the S-Reit sector with a revitalisation playbook of sorts – demonstrating to big property groups and unitholders that the real power of manager-internalisation initiatives lies not merely in eliminating management fees, but in acquiring the means to drive capital-light growth.