

Manager internalisation isn’t the solution to Stoneweg Europe Stapled Trust’s problem
It should focus on ensuring its portfolio pivot boosts its DPS instead of wading into a potentially contentious overhaul
[SINGAPORE] The announcement last week that Stoneweg Europe Stapled Trust (Sert) may internalise its managers did not grab much attention in the market.
One reason may have been that the statement was not definitive. Before the market opened on Thursday (Aug 13), the managers of Sert said that they were in discussions with the trust’s sponsor about a range of “strategic, governance and organisational initiatives” aimed at enhancing long-term value for holders of its stapled securities.
They went on to say that these initiatives may include changes to management arrangements, fee incentive frameworks and the internalisation of the managers.
Without any specific details about these possible initiatives, the market did not seem interested in speculating about what exactly might be in store for Sert – especially as there were a number of more compelling value unlocking stories unfolding in the real estate sector.
Notably, CapitaLand Investment (CLI) said last week that it had identified S$9 billion of assets for accelerated value realisation. This portfolio reorganisation will include offloading some legacy funds and balance sheet investments, and cutting its stakes in its larger real estate investment trusts, such as CapitaLand Integrated Commercial Trust (CICT) and CapitaLand Ascendas Reit (Clar).
CLI said the capital it frees up will be used to support its growth and strengthen its balance sheet, or be returned to its shareholders.
Meanwhile, Frasers Property Ltd (FPL) is preparing to seek minority shareholder approval later this month to optimise S$2.1 billion of assets held by Frasers Hospitality Trust (FHT), which was taken private last year. Under the deal, FPL will offload FHT’s most fully priced properties to the group’s controlling shareholder, and position Valley Point for a full redevelopment.
Capital recycling initiatives aside, City Developments Ltd (CDL) and UOL Group reported strong H1 2026 financial results last week, driven by surging residential property sales in Singapore. CDL’s numbers were so strong that they triggered a bounce in its share price – underscoring the importance of robust operational performance in driving further share price gains at this point.
Against this backdrop, the early value unlocking discussions at Sert might not even have made headlines last week if the potentially controversial and divisive matter of manager internalisation had not been mentioned.
Is such a move in the best interest of Sert’s stapled securityholders? Or, should Sert just emulate the less contentious value enhancing strategies of CLI, FPL and CDL instead?
Pros and cons
For many market watchers, internalising the manager of a real estate investment trust (Reit) is intuitively appealing. Besides possibly saving some fees, an internally managed Reit would arguably be less likely than an externally managed Reit to prioritise asset growth over returns to investors.
It is also often pointed out that Reits in the US are predominantly internally managed; and that internally managed Reits tend to outperform externally managed ones.
Among the counter arguments are that Reits with external managers owned by major property developers usually have access to a pipeline of high quality assets, and are often able to raise funds on more advantageous terms.
Whatever the case, the main sticking point in any manager-internalisation proposal at Sert is likely to be the valuation of its manager entities.
Sert was part of Australian Securities Exchange-listed Cromwell Property Group until two years ago. In 2024, Cromwell sold its European fund management platform along with its 27.8 per cent stake in the Reit to Stoneweg Global Platform for 280 million euros. Based on the disclosed price of the Reit’s units, the implied price of Sert’s manager and property manager in that transaction was 42.5 million euros.
Would a valuation in the same ballpark be acceptable to Sert’s stapled securityholders and its sponsor group? What impact would it have on Sert’s future performance?
Over the years, stakes in a number of Reit managers have changed hands. Among them were the managers of IReit Global and Sabana Industrial Reit in 2019, and Viva Industrial Trust in 2018.
However, there has only been one case so far of a Reit buying its own manager. In 2016, Croesus Retail Trust (CRT) acquired its manager for S$50 million.
It is unclear how this would have reshaped CRT’s long-term performance, though. Less than a year after the internalisation was completed, a deal was reached for Blackstone Real Estate to acquire CRT at a 23 per cent premium to its net asset value (NAV).
Then there is Sabana Reit. In 2023, its unitholders voted to oust its external manager, and direct its trustee to internalise the management function. This process was finally completed last year, and the Reit was renamed Alpha Integrated Reit. The costs incurred by the trustee and the former manager in the internalisation process amounted to S$12.6 million.
During the 12-month period up to Aug 12, the Reit delivered a strong total return of 33.9 per cent, indicated Bloomberg data.
Weak valuation
My sense is that Sert’s stapled securityholders will not be easily persuaded that internalising its managers is in their best interests – unless the manager entities are acquired at a nominal cost.
For one thing, Sert has been performing reasonably well. During the 12 months to Aug 12, it delivered a total return of 6 per cent, slightly ahead of the iEdge S-Reit Index’s total return of 5.7 per cent. Sert was the 11th best performer of the index’s 34 components.
Over the last three years, Sert was the fifth best performing component of the index with a total return of 33.7 per cent. The index itself returned 11.4 per cent.
The problem is that Sert’s stapled securities have a market valuation. At their Friday close of 1.58 euros, they were trading at an annualised H1 2026 distribution yield of 8.4 per cent, and 0.78 times NAV.
This hampers Sert’s ability to tap investors for equity to acquire assets, and address its relatively high gearing of 41.9 per cent.
But would internalising Sert’s managers fix this problem?
The way I see it, Sert’s weak valuation is mostly due to local investors being unfamiliar with its properties. It may also be partly the result of the decline in its distribution per stapled security (DPS) over the past few years.
Sert is currently guiding for its full-year 2026 DPS to be in line with its 2025 DPS of 0.1339 euros – which was lower than its 2024 DPS of 0.14106 euros, its 2023 DPS of 0.15693 euros, and its 2022 DPS of 0.17189 euros.
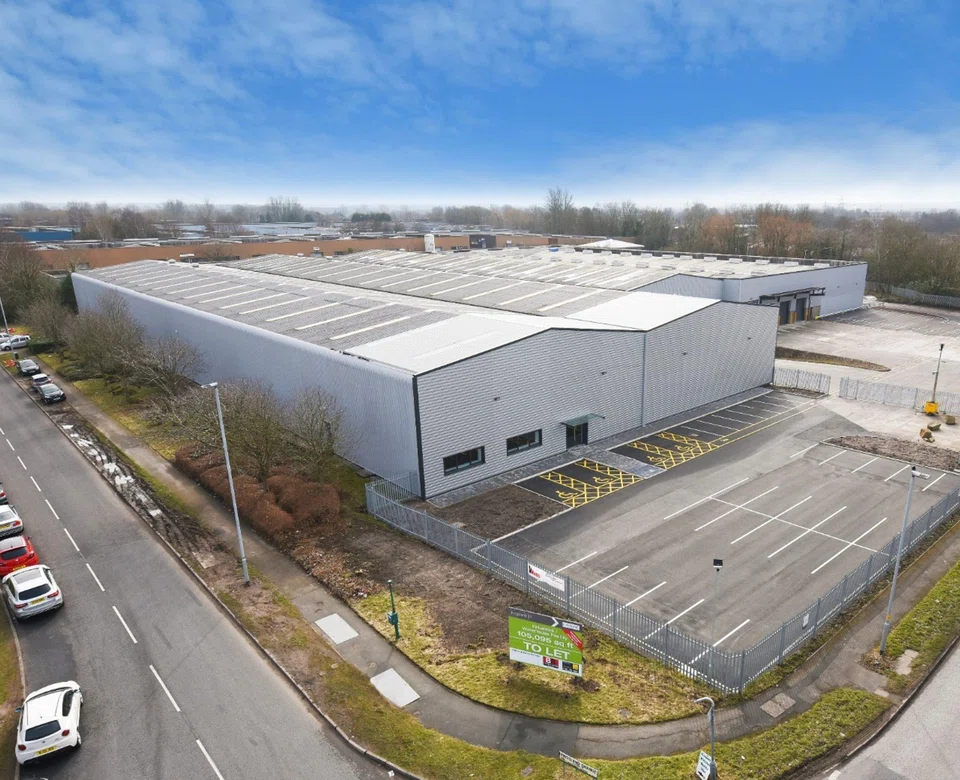
However, Sert has been working to improve its operational performance. Much like CLI and FPL, it has been actively restructuring its portfolio – tilting away from dull office properties towards more exciting logistics, light industrial and data centre assets.
By 2028, its exposure to logistics, light industrial and data centre properties is targeted to breach 80 per cent, up from 63 per cent as at Jun 30.
If this leads to a positive shift in its DPS trajectory, more local investors may be inclined to take a chance on its Europe-focused portfolio, which could lead to a market re-rating similar to that of CDL and UOL.
In the meantime, it might be a good idea not to alienate the market with talk of a manager-internalisation exercise.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

