

There isn’t a practical alternative to US Treasuries
American government debt is the world’s benchmark for a reason – and that hasn’t changed
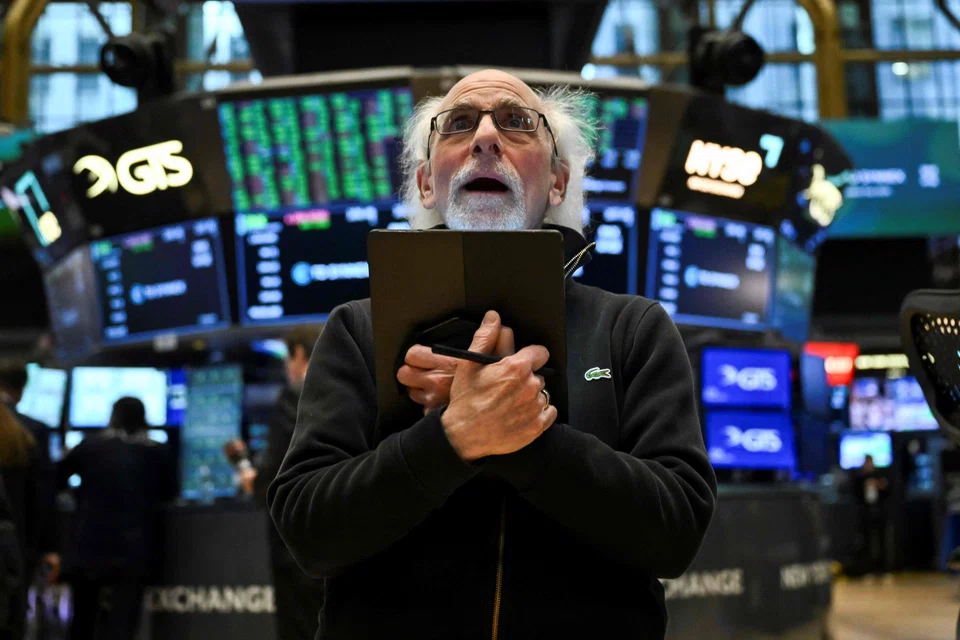
MY BLOOMBERG News colleagues have written that the mayhem spawned by the Trump tariffs has planted the seeds for plausible alternatives to US Treasuries as a global haven. While they make many salient points, the reality is that there is no viable option for the vast majority of investors.
Treasuries are the bulwark of the world’s financial system for a reason, and the current ructions mostly reflect a well-functioning machine clearing out a well-documented excess of leverage. The greenback has held up fairly steadily, amid strong demand for US dollars in funding markets; central banks aren’t reporting any issues with access to the currency.
There’s still a market price for securities with, so far, no need for central bank intervention. The moment bears little resemblance to the March 2020 Treasury bond rout at the outset of the Covid-19 pandemic, though there has indeed been a similar dash to cash as longer-dated US Treasuries were no longer seen as risk-free assets.
The steepening of the yield curve, as short maturities price in prospective rate cuts, is entirely logical. Higher long-end Treasury yields, combined perhaps with issuance shifting shorter, should provide willing buyers.
Equally, the sovereign creditworthiness of the US is no longer what it perhaps once was – but then neither is it anywhere else. Foreign investors are in the US because their own domestic markets provide insufficient liquidity or returns – and the search for returns is the unstoppable force of all investment funds.
It makes sense for Japanese investors to head home if they fear capital losses and potential currency losses if the US dollar no longer appreciates inexorably versus the yen. But they won’t be content for long to accept 1.25 per cent yields for 10 years versus 4.25 per cent for Treasuries.
Japan’s vast debt – more than 250 per cent of gross domestic product – hasn’t gone away, and its bond market benchmark sometimes doesn’t even register a single daily trade.
The same is broadly true for the European investors who have seen the US as the promised land when faced for many long years with an underperforming economy and stock market and near-zero bond yields.
German yields this week proved popular, outperforming euro-area peers, but that’s not likely to last long either, at about 2.6 per cent when higher-yielding alternatives beckon.
It’s hard to see many non-European fixed-income investors hanging around while Germany ramps up its defence spending by nearly 1 trillion euros (S$1.5 trillion). The common currency has existed for a quarter-century, but it’s yet to challenge the greenback’s global usage.
Liquidity may be an ephemeral concept and impossible to measure, but it’s best defined as the ability to buy or sell an asset with relative ease without meaningfully altering the price. A huge amount of volume has traded and there are few reports of inability to exit normally liquid securities.
This is the key benefit of the largest financial market the world has ever seen – no other comparison exists. It’s akin to the debate about whether Brics nations could ever create a liquid alternative to the US dollar.
The US may well be a dirtier shirt as the tariff debacle plays out, but we’re no closer to an alternative either. The US may not be as exceptional as we once thought, but it’s still way more attractive than anywhere else as an investment conduit for the rest of the world. BLOOMBERG
TRENDING NOW
US Fed hikes rates amid stubborn inflation; signals further tightening in coming months
Quarter of Singtel special discounted shares sold ahead of CPF Board transfer
AirAsia’s funding woes test how far Malaysia will go to protect its budget champion
Singapore’s wealth boom is raising the bar for aspiring private bankers

