

Is the Trump administration intentionally weakening the US dollar?
The greenback’s decline reflects the consequences of aggressive and erratic economic policies that have shaken global confidence in US leadership
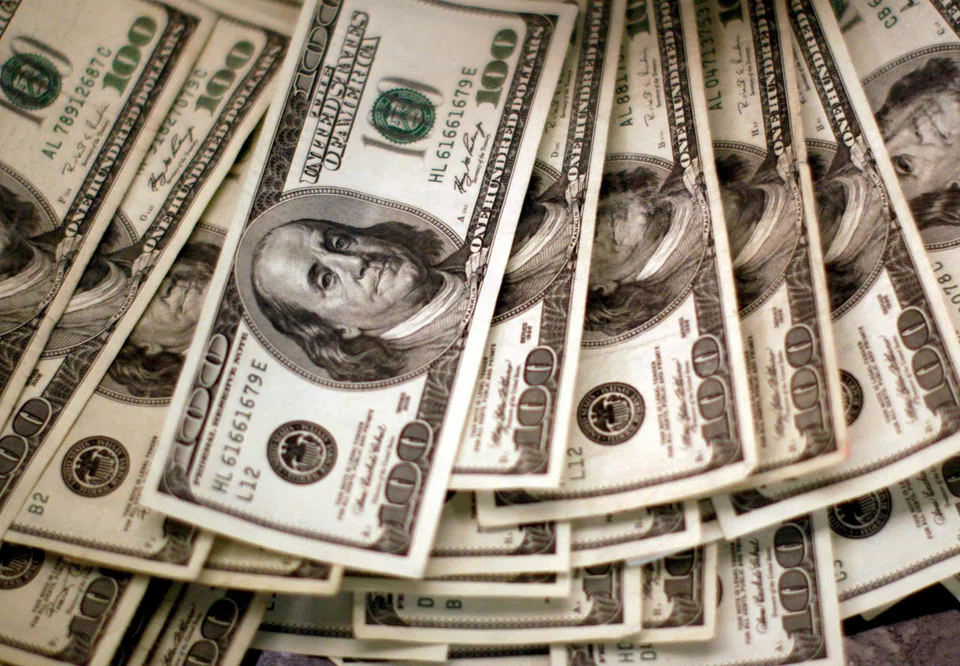
THE question of whether the Trump administration is deliberately pursuing a weaker US dollar has become one of the most consequential debates in international economics today. The answer, paradoxically, appears to be both yes and no – revealing deep contradictions within the administration’s economic strategy.
The paradox: A dollar in decline
The dollar experienced its steepest first-half decline in over 50 years during 2025, dropping nearly 11 per cent in the six months following Trump’s inauguration. This historic weakness stands in stark contrast to Wall Street’s pre-election expectations that his policies would strengthen the greenback. The dollar index fell 10.8 per cent in H1, while the euro has risen 13 per cent to above US$1.17.
Yet this decline cannot be attributed to a coherent, intentional policy. Instead, it reflects the unintended consequences of aggressive and erratic economic policies that have shaken global confidence in American leadership.
Competing visions within the administration
Within the White House, there appear to be competing and fractured views about the dollar’s role, with Treasury Secretary Scott Bessent maintaining that the strong dollar policy remains intact, while Council of Economic Advisers chair Stephen Miran has proposed weakening the dollar through a “Mar-a-Lago Accord”.
This internal discord reveals three conflicting approaches:
- The “Strong Dollar Camp”: Bessent publicly affirms America’s traditional strong dollar policy, arguing that currency strength reflects global confidence in US economic management and the rule of law.
- The “Weak Dollar Camp”: Miran and others see an overvalued dollar as hindering American manufacturing competitiveness and contributing to persistent trade deficits. They advocate coordinated international action to devalue the greenback while maintaining its reserve currency status.
- The Trump View: The president appears to view the dollar’s international role through his “America First” lens, threatening 100 per cent tariffs on nations seeking to undermine “the mighty US dollar”, yet simultaneously complaining that a strong dollar hurts American exports.
The tariff conundrum
Trump’s tariff strategy – ostensibly designed to protect American industry – has paradoxically accelerated the dollar’s decline. The “Liberation Day” tariff announcement on Apr 2 triggered market turmoil, with more than US$5 trillion erased from the S&P 500 in days.
Traditional economic theory suggests tariffs should strengthen a currency by reducing imports and improving trade balances. Instead, Trump’s back-and-forth decisions on tariffs have injected uncertainty into markets and clouded the outlook for the US economy, with investors increasingly uncomfortable with policy unpredictability.
A loss of confidence
The evidence suggests that while some administration officials may desire a weaker dollar to boost manufacturing competitiveness, the actual decline stems primarily from loss of confidence rather than deliberate policy. Several factors are driving this erosion:
- Fiscal concerns: Trump’s tax legislation is expected to add trillions of dollars to the US debt pile over the coming decade, raising concerns about the sustainability of Washington’s borrowing and prompting an exodus from the Treasury market.
- Policy unpredictability: The administration’s constantly shifting stance on tariffs and trade relationships has undermined the dollar’s traditional “safe haven” status during times of uncertainty.
- Geopolitical risks: Trump’s tariffs on closest allies, antipathy towards international cooperation and ambiguous stance on conflicts such as Russia-Ukraine have weakened longstanding international relationships.
- Loss of safe-haven status: The dollar declined sharply even as financial volatility soared following “Liberation Day” – an unprecedented deviation from historical flight-to-safety behaviour.
The long-term threat to dollar dominance
Perhaps most concerning is the potential long-term damage to the dollar’s role as the world’s reserve currency. Central banks have begun shifting reserve holdings to other currencies amid increasing doubts about whether the US is a reliable economic partner.
Foreign investors sold US$63 billion in US equities between March and April 2025, marking a major withdrawal from their record 18 per cent ownership share entering the year. This capital flight reflects deeper concerns about US institutional stability and policy coherence.
The administration’s threats to use the dollar system as a weapon against adversaries and allies alike may backfire spectacularly. Such threats portend far more economic devastation than tariffs precisely because of the dollar’s centrality to the global economy, yet the willingness to use such threats means the administration has little hope of maintaining allied economic support.
Chaos, not strategy
The evidence suggests the Trump administration is not deliberately weakening the dollar through coordinated policy.
Instead, the dollar’s historic decline represents an unintended consequence of contradictory internal positions that confuse markets; aggressive tariff policies; fiscal irresponsibility; erratic policymaking that undermines confidence in US economic management, and threats that drive trading partners to develop alternatives to dollar-based systems.
The irony is profound: An administration that frequently invokes the “mighty US dollar” and threatens nations seeking alternatives has pursued policies that accelerate the very de-dollarisation it claims to oppose. Whether intentional or not, the result is the same: a weakened currency and diminished American economic leadership.
The question going forward is whether the damage can be contained, or whether we are witnessing the beginning of a fundamental shift in the global monetary order that has underpinned American power for eight decades. If the administration genuinely wants a weaker dollar to boost manufacturing, it may be getting its wish – but at a cost far higher than anticipated.
TRENDING NOW
NEA identifies 7 firms responsible for haze fires, notices issued urging action: Grace Fu
DBS remains analysts’ pick ahead of Q3 earnings after Singapore banks’ share slump

High Court rules against Julius Baer’s Singapore trust arm in US$50 million family trust dispute

Could stablecoins be the future of money?

