

UltraGreen.ai’s big slump: Was it the Singapore market that failed the company, or vice versa?
Firms seeking to be priced on their potential must adopt a culture of transparency and meaningful engagement
[SINGAPORE] During the National Day weekend, an independent analyst named Jamal Aliyev sent an e-mail to some of my colleagues and me to draw our attention to research he had just published about UltraGreen.ai.
Aliyev had identified two companies – Zydus Lifesciences and Provepharm – that may soon begin competing with UltraGreen.ai in the supply of indocyanine green (ICG) dye in the US.
He also pointed out that UltraGreen.ai had made no disclosures about the recent regulatory approvals these potential competitors had obtained in that key market.
My colleague Benjamin Cher eventually set about doing the necessary legwork for a story, which included verifying certain facts, engaging Aliyev and other analysts, and asking UltraGreen.ai for comment.
By the time his story was published last week – on Aug 19, in the afternoon – the possibility of UltraGreen.ai’s core business facing new competitors had arguably been carefully weighed by analysts and the company itself.
Yet, after the story was published, UltraGreen.ai’s share price went into a tailspin, falling 44.8 per cent over the next two days. Its shares closed Friday (Aug 21) at US$0.635 – down 49.6 per cent for the week, and 57.9 per cent lower since the beginning of the year.
It may be a while longer before the market fully digests the negative news. At least one research house has downgraded its view on the counter since the sell-off.
In a note dated Aug 17, DBS Group Research said that UltraGreen.ai was well-placed to defend its market share, and that the adoption of ICG fluorescence imaging across a broader range of surgical procedures could partly offset the impact of a more competitive landscape.
The research house noted that the company was expanding into new geographies, and that its quantification platform would further entrench its market position.
While DBS warned that UltraGreen.ai’s sales volume and average selling price (ASP) in the US should be closely watched, it maintained a “buy” recommendation on its shares with a target price of US$1.95.
However, in a subsequent note on Aug 21, DBS said that it was maintaining its earnings forecasts for UltraGreen.ai but offered a range of estimates for the company’s 2027 earnings, based on different assumptions for its ICG sales volume and ASPs.
According to these alternative estimates, DBS cut its recommendation on UltraGreen.ai’s shares to “hold” and more than halved its price target to US$0.80.
Company or ecosystem problem?
As I watched the carnage unfold, I wondered if the Singapore market ecosystem was letting UltraGreen.ai down.
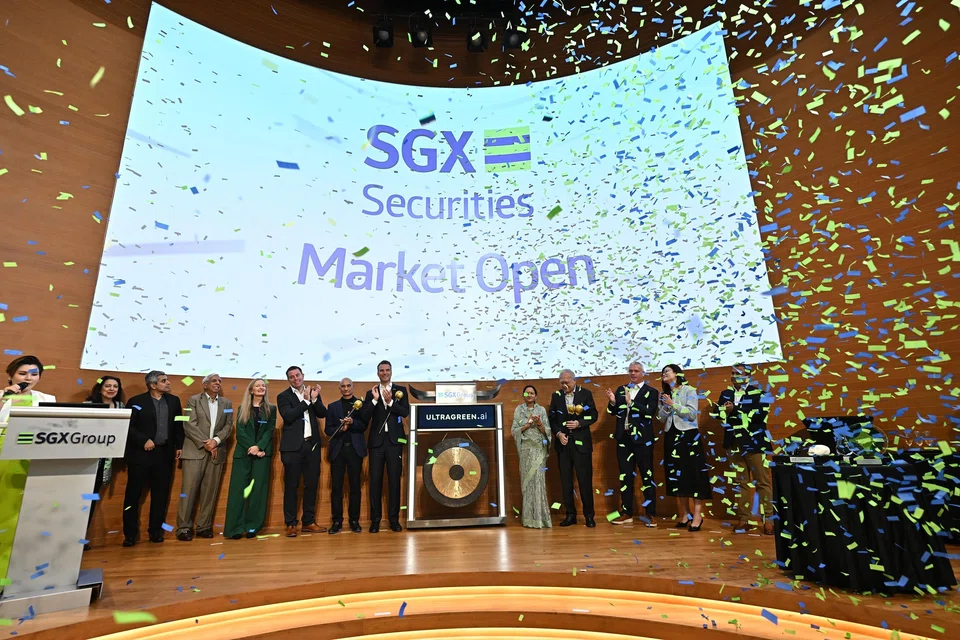
The company is exactly the kind of technology-driven, growth-oriented listing aspirant that the Monetary Authority of Singapore and Singapore Exchange (SGX) have been trying to attract to revitalise the local market.
One of its backers is the Anchor Fund – managed by Temasek’s 65 Equity Partners – which seeks to support promising companies ahead of an SGX listing.
Since its debut last December, UltraGreen.ai has delivered strong financial numbers. For the first half of 2026, it reported a 53 per cent rise in net profit to US$39.2 million, on a 24 per cent increase in revenue to US$87.2 million.
The company said that it expects its H2 revenue to exceed H1’s, and its full-year revenue to come in between US$175 million and US$185 million.
Yet, even before the recent concerns about increased competition, UltraGreen.ai was struggling to stay above its initial public offering price of US$1.45 per share – which valued the company at US$1.6 billion, or 20.4 times its annualised H1 earnings.
Is the Singapore market simply not ready for fast-growing but volatile companies operating in burgeoning new fields such as fluorescence-guided surgery?
Why was the market-moving concern about UltraGreen.ai facing more competition raised by an independent analyst, rather than the established research houses that had been covering the company?
Or, is it UltraGreen.ai that is too immature for Singapore’s staid public equities market? Given its apparent vulnerability to competition in the ICG space, should the company have gone public at a less demanding valuation?
Shouldn’t the company have anticipated all the market noise the prospect of increased competition would generate? Why didn’t the company address the matter when it reported its H1 results on Aug 12?
Less defensiveness, more engagement
On Aug 20, UltraGreen.ai responded to my colleague’s story with a clarification announcement that appeared to be partly aimed at declaring its compliance with the listing rules.
The company noted that the regulatory approvals obtained by Zydus Lifesciences and Provepharm in the US are publicly available information, and that it is continuing to monitor competitive developments in that market.
It went on to say that regulatory approvals do not necessarily lead to a commercial launch, market adoption or market penetration; and that the views expressed by analysts in my colleague’s story about the potential impact of increased competition “do not constitute information, forecasts or guidance provided or endorsed by the company”.
UltraGreen.ai also reaffirmed the revenue guidance it provided when it reported its H1 results.
In my view, this is unlikely to soothe nervous investors. The company’s shares didn’t tumble last week because of concerns about how Zydus Lifesciences and Provepharm might affect its financial performance in its current financial year, but on how they might reshape the company’s longer-term profitability.
More to the point, in order for the local market to extend its strong gains, and provide fast-growing companies like UltraGreen.ai with decent enough valuations to go public and remain public, investors have to be prepared to look beyond their earnings today to the blockbuster profits they might begin raking in five or 10 years from now.
For that to happen, companies have to shed their defensiveness and adopt a culture of voluntary transparency and meaningful investor engagement.
When approached for comment last week, Michael Tang, head of listing compliance at SGX Regulation, said: “While the listing rules do not require an announcement about external events relating to third parties or circumstances that may impact an entire industry or market, it is in the issuer’s interest to provide assurance to shareholders should such information have material impact on its operations and/or performance.
“An issuer is expected to have in place mechanisms to monitor its industry and competitive landscape. Where developments are evaluated to have material impact on the issuer, an announcement would be required to update shareholders accordingly.”
He added: “On a related note, as part of the Value Unlock movement, we have been encouraging companies to engage investors with relevant information.
“We believe that voluntary disclosures and the attendant market discipline will come together to create durable value for the ecosystem.”
If all stakeholders play their part, perhaps these efforts will help locally listed companies – especially less-established high-fliers such as UltraGreen.ai – maintain the confidence of investors when they inevitably encounter challenges on their growth journey.
The writer owns shares in UltraGreen.ai






