

Wall Street analysts are getting irrelevant
Bureaucracy is eroding the shrinking value-add that sell-side research can provide
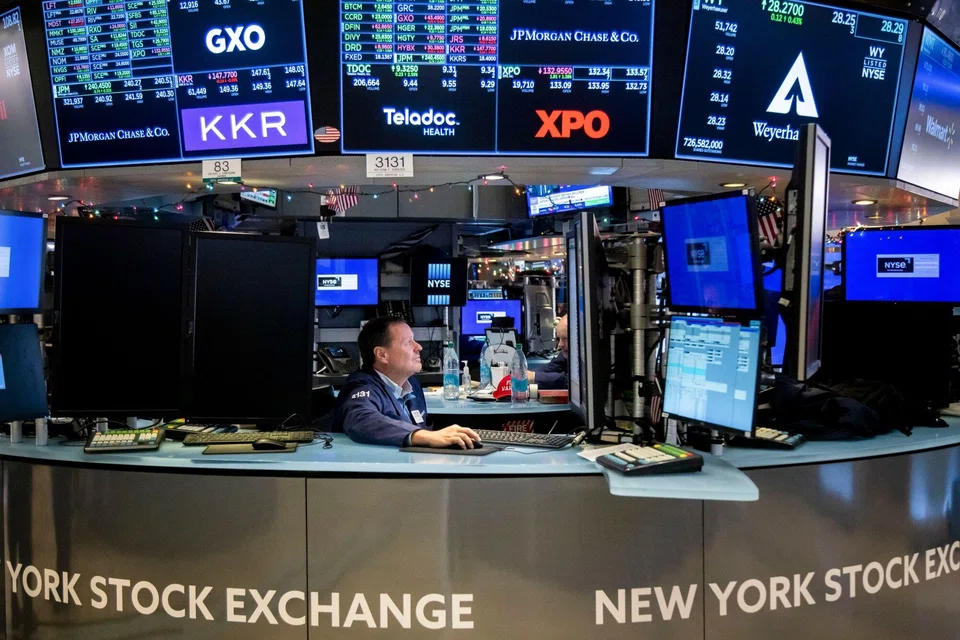
A RECENT Bloomberg article sounded the alarm on Wall Street research jobs. At the world’s 15 biggest banks, the number of equity analysts has fallen by about 30 per cent from a decade ago, with most cuts in Europe and Asia. Compensation has stagnated as well, forcing many to reinvent themselves. Some are becoming content creators on platforms such as Substack and X.
I went through a similar metamorphosis myself: I came into journalism after the Global Financial Crisis, when my former employer Lehman Brothers went bust. In so many ways, it was a good career move.
Bureaucracy and banking regulations have steadily eroded the value-add that analysts can provide. Sell-side research is a marketing tool. An investment bank can hope to retain and charge clients commissions if their insights are timely and unique. But a lengthy compliance and editing process is slowing that down, especially when there’s breaking news such as an unexpected chief executive change. Often, by the time sell-side research gets published, investors would have already found informed opinions elsewhere. For global banks, the situation is even more dire in China, where regulations are easier, competition is fiercer and local brokerages practically give away their research for free.
To make matters worse, even paying clients sometimes struggle to access research. European lenders, for instance, are subject to the MiFID II regulation that requires asset managers to pay directly for reports that they use. Try logging on to their research portals when markets are seeing sharp moves: One has to be patient and tolerate multiple steps of identity verification.
Meanwhile, the rise of social media has made an analyst’s life that much harder. In China, the so-called “little essays” – typically small items of unverified news shared as images in WeChat messaging groups to avoid text-based censorship – can swing stock and bond prices. Analysts don’t comment on these essays, since they are often unverifiable, unless they impact securities pricing in a meaningful way. As these market rumours continue to appear on a regular basis, sell-side research comes across as sleepy and untimely, and not useful when investors need it the most.
Granted, an analyst is still highly valuable if she can make correct predictions on industry trends. But alas, there’s hardly any long-term trend to speak of in markets like China, where a short government notice can kill an entire profitable sector, as we have seen with video gaming, fintech and after-school coaching. Even in the US, investment outlooks have become unpredictable with the impending return of Donald Trump to the White House.
Of course, there are other seismic factors making Wall Street analysts irrelevant. As my colleague Matt Levine noted, market concentration means that asset managers just need to understand a few dozen stocks, thereby reducing their need to outsource research to investment banks. The shrinking stock pool – in the US, the number of listed companies has fallen by half from a 1996 peak – also means fewer equity analysts are needed.
Over the years, people have asked me if I am worried that artificial intelligence and social media will make journalism obsolete. My response has always been that I think about the counterfactual and ask myself whether I would be happy and engaged as an equity analyst. These days, at least I don’t have to deal with excessive bureaucracy and compliance.
TRENDING NOW
Inside Jensen Huang’s last hours as Nvidia CEO

Higher rates, weaker spending: Is the Philippines entering stagflation?
‘I’ll be buying more’: Singapore investors pour into Nvidia shares on Jensen Huang’s exit

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista

