

Worried over job prospects? Young adults should go forth fearlessly to buy an HDB BTO flat
Bank on creating wealth from purchasing a subsidised home amid rising uncertainty
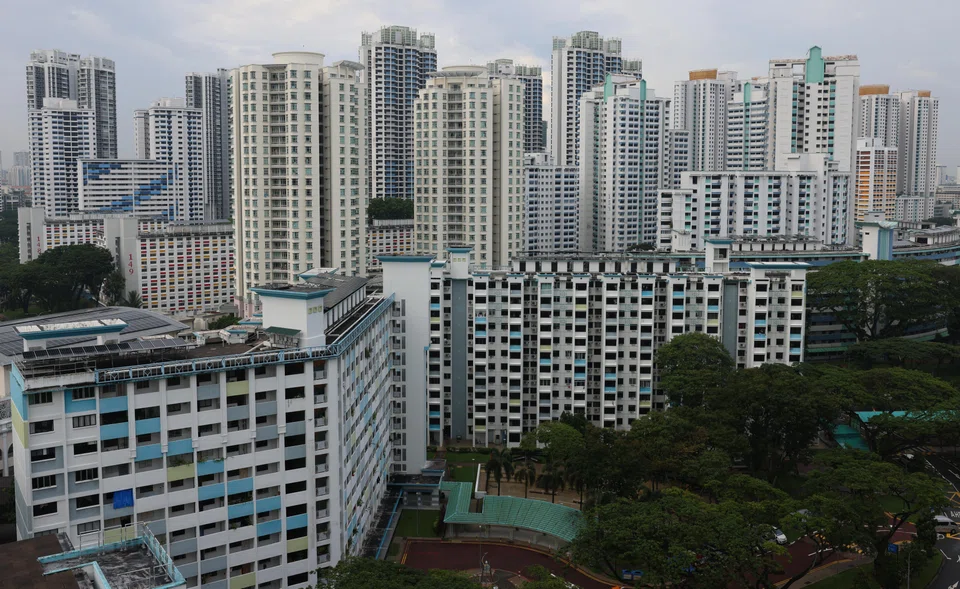
[SINGAPORE] The Housing & Development Board’s (HDB) upcoming June 2026 Build-To-Order (BTO) exercise will offer approximately 6,900 flats in Ang Mo Kio, Bishan, Bukit Merah, Sembawang and Woodlands.
Doubtless, many eligible young local couples will make a beeline to secure their maiden home at the upcoming BTO exercise. And getting a good ballot number is critical to snaring a choice unit.
However, life is not easy for many young people. After struggling through the stressful academic rat race, finding a suitable full-time permanent job can be challenging especially with mounting economic uncertainties.
With the growing use of artificial intelligence disrupting jobs in many sectors, securing entry-level jobs can be tricky, and job security might be increasingly tenuous.
Amid fierce competition for jobs, young adults may need to juggle various gig economy roles or pursue postgraduate degrees to try to get an edge.
Also, some young people might take several years trying out different jobs before finding what they like doing.
Given the above backdrop, should young adults who qualify to buy an HDB BTO flat go slow in trying to secure a unit?
I think not. On the contrary, with the difficult job market situation, subject to being able to find the required funding, eligible young people should move expeditiously to get a BTO flat.
Fortunately, first-time applicants have a good chance of landing a BTO unit because of the priority first-timers get and the ramp-up in supply of BTO flats by the HDB.
In the February BTO exercise, the median application rate among first-timer families for three-room and bigger flats was 0.9 times.
BTO income ceiling
Waiting till one is more settled career-wise or is in a stronger financial situation before applying for an HDB BTO unit is risky.
A local couple who bust the monthly household income ceiling of S$14,000 cannot buy a flat at a subsidised price directly from the HDB.
A couple who is ineligible to buy a Standard four-room BTO flat might need to cough up over 50 per cent more for a comparable resale unit nearby.
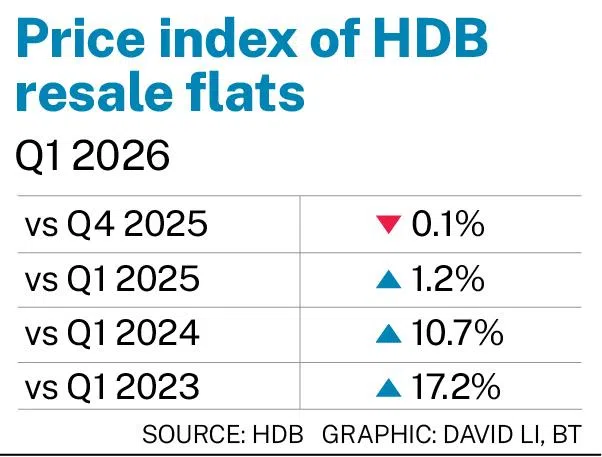
In perspective, HDB resale flat prices rose by 54.7 per cent between Q4 2019 and Q1 2026. In Q1, the HDB resale price index dipped by 0.1 per cent quarter on quarter. Nevertheless, there are many pockets of strength in the HDB resale flat market.
In addition, there are grants available for buying HDB flats where the qualifying criteria includes household income.
For example, an eligible household whose monthly income does not exceed S$14,000 can receive a CPF housing grant to buy an HDB resale flat. An eligible first-timer couple comprising two Singapore citizens can receive S$80,000.
Meanwhile, a first-timer applicant may qualify for the enhanced CPF housing grant to help with a new or resale HDB flat purchase. Subject to meeting other criteria, a first-timer household with an average monthly household income of up to S$9,000 can receive this grant.
The amount of grant is higher for households whose income is lower. For example, a first-timer household with average monthly income of S$1,500 or less can receive the maximum grant amount of S$120,000, while a first-timer household with average monthly income of S$4,501-S$5,000 can get S$65,000.
Capital gains and rental income
Besides obtaining a good space for living, BTO flat owners have a safe and profitable investment. One might achieve gains of a few hundred thousand dollars by selling a Standard BTO four or five-room flat in the resale market after the minimum occupation period (MOP) of five years.
While Plus and Prime flats have a 10-year MOP and tougher restrictions govern who can buy a resale Plus or Prime flat, owners of Plus or Prime BTO flats should likewise stand to make sizeable capital gains. Plus and Prime units are in more desirable locations than Standard flats.
With the HDB building well-designed homes, HDB towns islandwide boasting comprehensive amenities as well as good transport connectivity, and town councils assiduously managing, maintaining and improving the common property of HDB flats, demand for HDB resale homes is well-supported.
Arguably, hardly any investment will produce a virtually guaranteed sizeable return which can match that generated by buying a flat directly from the HDB.
In turn, an HDB homeowner could use the gains from selling a BTO flat post MOP to fund a business venture or upgrade his home among others.
Importantly too, an owner of a larger BTO flat gets both a home for living and the ability to generate income from renting out spare rooms.
Owners of HDB three-room or bigger flats can rent out spare rooms.
Facing rising inflation and job market insecurity, young persons could find the income earned from renting out a spare room in an HDB home invaluable. Rental income collected can be especially useful when individuals retrain for new opportunities, embark on an entrepreneurial venture or take a prolonged absence from work to attend to family needs.
Buying a home is a big ticket item. For young persons starting out in their careers, taking on a multi-year housing loan can be scary especially with rising anxiety over job security.
Still, buying an HDB flat at a subsidised price should largely be a no-brainer for eligible young people.
Sure, there are questions over whether private homes here make great investments given high entry prices today and an ageing as well as slow-growing population.
However, while private homes transact at market prices, HDB BTO flats are sold at subsidised prices.
Buying a high-quality product at a substantially discounted price in safe-haven Singapore in the form of a BTO flat has been a proven wealth creator for many older Singaporeans.
While the world is fast changing, young adults here can still confidently count on buying a BTO flat to build wealth. Ultimately, the wealth generated from owning a BTO flat matters even more as young people face a tough job market and rising life expectancy.
TRENDING NOW

Simba admits exceeding spectrum limits amid failed M1 deal; parent company Tuas’ full-year profit surges 277%
‘Our bread and butter’: Family-run Loo’s Hainanese Curry Rice hands reins to third generation

StarHub, Keppel confirm talks over potential M1 deal

Grab executives buy back shares after stock hits 3-year low on Atome deal

