You can fix rare earths for the price of one White House ballroom
The amount of government spending needed to bullet-proof most of the world’s supplies of these elements is tiny
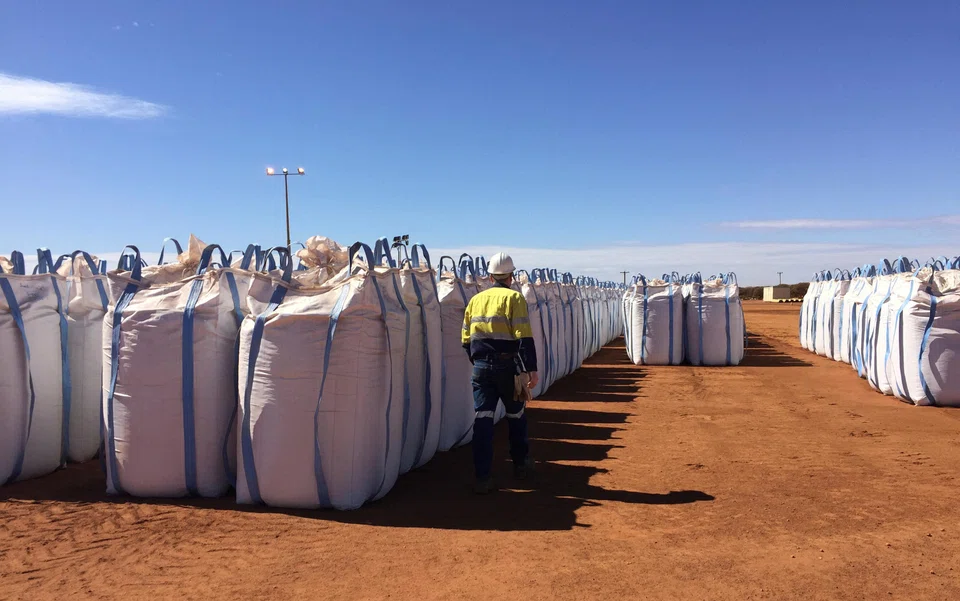
GIVEN the ability of the words “rare earths” to bring the leadership of the world’s largest economy to its knees, it is tempting to think that establishing a supply chain to produce the minerals outside China is a challenge on the scale of putting a man on the moon.
In fact, that is a vast overestimate. The amount of government spending needed to bullet-proof most of the world’s supplies of the elements – essential for high-strength magnets used in military aircraft and munitions, as well as electric cars and wind turbines – is tiny. It is probably on the order of a single White House ballroom (US$200 million), or six hours of spending on AI data centres by Silicon Valley’s hyperscalers (US$350 million). By some measures, governments might even turn a profit on the transaction.
What has been missing until very recently is sustained attention and follow-through from officials in Europe and the US. Beijing’s latest export controls appear to have changed that for good. In thinking that rare earths were a geopolitical weapon equal to developed democracies’ hold over the semiconductor supply chain, China has vastly overplayed its hand.
That is because minerals processing is not rocket science. Nor is it the 3-nanometre chip design enabled by extreme-ultraviolet-lithography machines – a true moonshot innovation that has involved decades, and tens of billions of dollars, of research and development (the machines themselves change hands for US$400 million apiece).
Almost every mined element in common use is extracted by the same basic set of processes – grinding, roasting, leaching, separating – at sites where engineering expertise is typically more focused on minimising costs and safety hazards, rather than fundamental challenges of physics or chemistry. China’s dominance of rare-earth production probably gives it a technological edge, but in this industry, it is a minimal one that is easily erased.
Consider Lynas Rare Earths. Some 15 years ago, the miner was one of the first beneficiaries of the current era of resource nationalism, when China cut off supplies of rare earths to Japan in a stand-off over disputed islands north-east of Taiwan.
Tokyo’s response was swift. In partnership with Japanese trading house Sojitz, its mineral-security agency JOGMEC provided Lynas with US$250 million in discounted funding in 2011 to help advance its plans to mine rare earths in Australia, process them in Malaysia, and then distribute them via Sojitz.
Another US$200 million was added in 2023 to start production of so-called heavy rare earths such as dysprosium and terbium, the main focus of China’s threatened export controls.
For Japan, that US$450 million of far-sighted capital turned rare earths into a mostly solved problem. Thanks to its secure supply of raw materials, the country now has about three-quarters of the world’s rare-earth magnet production capacity outside China.
Assume that each dollar of government funding can mobilise US$4 of private money, and the whole programme has probably cost US$90 million or so to the public purse – about one hundredth of one per cent of Tokyo’s annual budget spending.
Japan is not alone. Mountain Pass, a mine in the Mojave Desert in California, was for decades the world’s biggest producer of the elements. It was also in the market for cheap finance in the early 2010s. Unlike Lynas, it was turned down for a government loan in the US and financed itself with junk bonds instead, just before a surge in Chinese supplies crashed prices and sent it careening into bankruptcy.
Revived under current owners MP Materials, it stayed on stronger footing by holding net cash to protect itself from downturns in the market. Thanks to rising worries in Washington, this year it managed to extract US$550 million in loans and equity from the US government, along with purchase and price guarantees, to advance its heavy rare earths plans.
Back in Australia, Iluka Resources – mainly known for producing the titanium oxide pigment used in white paint and toothpaste – noticed there was money to be made from its waste dumps. By reprocessing its discarded tailings, it could turn itself into yet another rare-earths producer, and even have the capacity to purify other companies’ ore.
With A$1.65 billion (S$1.38 billion) in government loans, it is aiming for first production in 2027. By acting as banker, Canberra should get back hundreds of millions more than it put in.
It is common to argue that handling of the low-level radioactive thorium and uranium waste, which commonly occurs alongside rare earths, is a prohibitively difficult problem in environmentally minded democracies.
Not so: MP Materials and Iluka plan to handle their tailings on site, in dumps protected from groundwater intrusion and dust release. Similar waste is a common by-product of the phosphate fertiliser industry.
These facilities, and others scrounging around for a few hundred million in concessional loans, are together more than capable of meeting the world’s needs for rare earths, even if Beijing were to employ the nuclear option of an all-out embargo. The current US war on wind energy and electric vehicles – the biggest consumers of rare-earth magnets – makes it far more costly to support this supply chain, but even now, it is not impossible.
China may have the biggest reserves, but it only got its current dominant-producer status by presenting itself as the cheapest, and most stable, source of long-term supplies. The geopolitical sabre-rattling of recent months appears to have permanently immolated that reputation. Dozens of rival miners and processors are now stepping up to take its place.
As long as developed democracies do not forget the lesson of this moment, Beijing will come to regret thinking that it could ever hold the world to ransom over a pile of dirt. BLOOMBERG