

FCT posts 2.6% higher H2 DPU to hit new full-year record payout
Revenue is up 8.7% at S$223 million for the half-year, from S$205.2 million before
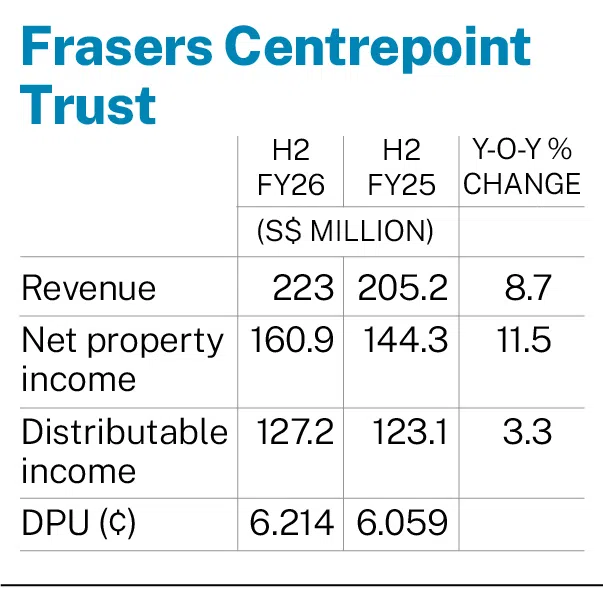
[SINGAPORE] Frasers Centrepoint Trust (FCT) on Thursday (Oct 22) posted a distribution per unit (DPU) of S$0.06214 for the second half of the year ended Sep 30, up 2.6 per cent from S$0.06059 in the previous corresponding period.
This brought full-year DPU to S$0.1235, a record high.
Distributable income for H2 rose 3.3 per cent to S$127.2 million, from S$123.1 million in the same period the year before.
Revenue was up 8.7 per cent at S$223 million for the half-year, from S$205.2 million before.
Net property income (NPI) rose 11.5 per cent to S$160.9 million for H2 FY2026, from S$144.3 million in the year-ago period.
The increases in revenue and NPI were driven by contributions from Northpoint City South Wing, which was acquired in May 2025, as well as higher passing rents in most malls.
For the full year, distributable income rose 8.2 per cent year on year to S$252.2 million. Revenue increased 14.2 per cent year on year to S$444.9 million, while NPI grew 15.7 per cent on the year to S$321.7 million.
Richard Ng, CEO of FCT’s manager, said the trust’s FY2026 performance was underpinned by healthy operating metrics, its capital-recycling strategy and asset enhancement initiatives (AEIs).
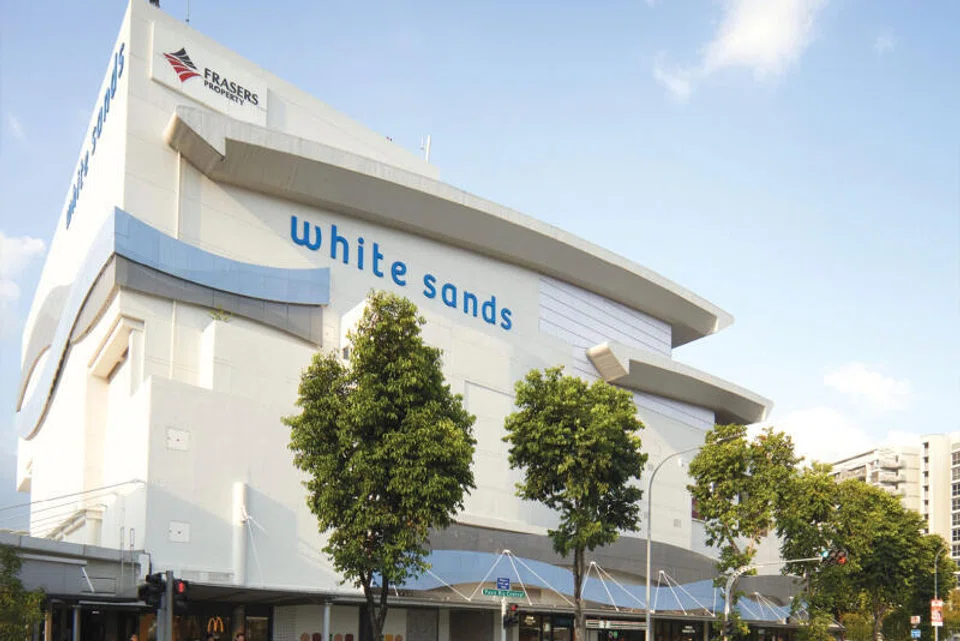
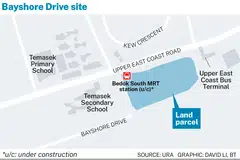
He said the S$467 million divestment of White Sands created debt headroom for FCT to reinvest part of the proceeds in the joint development of the Bayshore Drive site, providing a new growth driver and potential future acquisition opportunity.
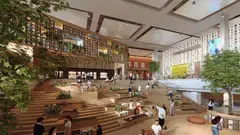
The trust also completed enhancement works at Hougang Mall in September, with 99.7 per cent in committed occupancy and a return on investment of about 8 per cent.
The first phase of the AEI at Nex is scheduled for completion by end-2026. It has achieved 98 per cent leasing pre-commitment. The second phase will start in January 2027, with completion expected in the first quarter of 2028.
Enhancement works at Causeway Point are expected to begin in the second quarter of 2027.
Aggregate leverage fell to 38.7 per cent as at Sep 30, from 40.4 per cent as at Jun 30. Gearing would stand at 36.8 per cent after repaying borrowings with divestment proceeds from White Sands after the close of the financial year.
Group short-term borrowings fell to S$111 million from S$404 million. The average cost of borrowing was 3.1 per cent in the fourth quarter of FY2026, with a full-year cost at 3.2 per cent compared with 3.8 per cent in FY2025. The interest coverage ratio improved to 4.37 times as at end-September.
The manager expects Singapore’s suburban retail market to remain resilient, where positive demand and supply dynamics underpin organic DPU growth through healthy rental reversions and high committed occupancy.
FCT’s retail portfolio recorded committed occupancy of 99.7 per cent as at end-September, while rental reversions averaged 6.6 per cent for FY2026. Shopper traffic and tenants’ sales rose 1.8 per cent and 1.3 per cent year on year, respectively. Average occupancy cost remained largely stable at 16.3 per cent, providing capacity for rental growth.
Jefferies analysts Geraldine Wong and Wilson Ng expect Singapore retail growth to moderate in 2027, with the launch of the Johor Bahru-Singapore Rapid Transit System (RTS) Link in February 2027.
They said: “Cross-border retail sales leakage is expected to increase by 3 to 4 per cent post-RTS, overlapping with the tapering off of SG60 government vouchers. Headline tenant sales could continue to moderate, but (be) supported by the lack of new retail supply in the coming years.”
Jefferies thus expects softer retail conditions and AEI disruptions to temper near-term growth.
As at end-September, FCT’s weighted average lease expiry stood at 1.8 years by net lettable area and 1.7 years by gross rental income.
In FY2026, the trust brought in 107 new brands in its malls, including Korean gelato Tofu G and fashion retailers such as Setirom and 2nd Street.
FCT’s H2 distribution will be paid on Nov 27, after books closure on Oct 30.
Units of FCT were trading 1.5 per cent or S$0.03 higher at S$2.09 as at 10.58 am, after the release of the results.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.






