

A Hong Kong property billionaire with a big family dilemma
FROM CK Asset’s Li Ka-shing to Henderson Land Development’s Lee Shau-Kee, Hong Kong’s fabulously wealthy tycoons have for decades dominated the city’s property and retail sectors. Now, these families face a big existential crisis.
Their founders are either really old or have passed away. The younger heirs need to prove that the original rags-to-riches business acumen is still in their DNA, at a time when the economy and the financing world are rapidly changing.
Out of the four biggest dynasties, the most vulnerable seems to be the Chengs, whose empire spans property flagship New World Development and retail jeweller Chow Tai Fook Jewellery Group. After a brutal sell-off this summer, bonds issued by New World are yielding double digits – hardly befitting the image of a family that is, by one estimate, worth almost US$30 billion.
Leverage is the worry. Once we consider perpetual bonds as debt, New World’s net gearing reaches an elevated 80 per cent, according to UBS. This is much higher than that of its peers Henderson Land, CK Asset or the Kwok family’s Sun Hung Kai Properties. In fact, its balance sheet looks more like those of the city’s smaller builders, or even – gasp – mainland Chinese developers.
Since becoming New World’s chief executive in 2020, Adrian Cheng – the Harvard-educated eldest grandson of founder Cheng Yu-tung – has been, in his own words, not “trying to preserve it and hold it tight”, but “disrupting and rejuvenating it to create a new business model”.
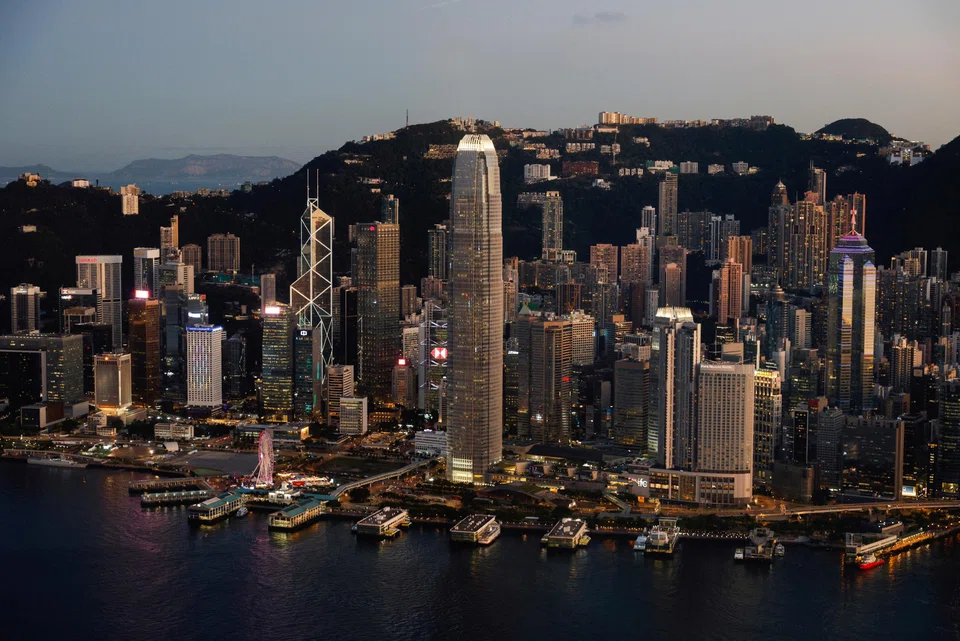
To that end, as his first signature project, the HK$20 billion (S$3.5 billion) Victoria Dockside complex – across the harbour from Causeway Bay, one of the world’s most expensive retail districts – boasts artistic, innovative designs throughout. Rosewood Hong Kong, a new luxury hotel run by his younger sister Sonia, another Harvard graduate, is also located there.
Meanwhile, Adrian is building 11 Skies, a HK$20 billion retail and entertainment complex near the airport, betting that mainland Chinese will continue to crowd into Hong Kong and splash money.
Another project, the HK$30 billion Kai Tai Sports Park, is on the site of the city’s old airport. This area is being developed into a second commercial hub that rivals Central, albeit with snags and delays.
All that ambition comes at a cost, even for the Chengs. As a way to inject capital into New World, the private family office plans to buy its 61 per cent equity interest in NWS Holdings, a separately listed subsidiary with operations in construction, insurance and toll roads. Upon completion of this deal, New World will likely receive HK$17.8 billion in net proceeds.
This deal is a double-edged sword. On the one hand, it will help ease New World’s liquidity needs. The developer has about HK$39 billion in short-term debt, and capital expenditure has been elevated in part because of 11 Skies.
On the other hand, there is now a perception in the market that the developer may no longer be able to get financing below 6.7 per cent, which is NWS’ dividend yield. It is a reputation hit the family has to accept.
As such, in late August, when a little-known blogger accused New World of “disguising equity as debt” and pledging away three commercial projects – said to be valued at HK$20 billion – for financing at 11 per cent to 12 per cent interest, the market response was immediate and brutal.
The builder had to release a statement on the Hong Kong stock exchange, denouncing such “untrue and unfounded statements”. But think about it: When was the last time a tycoon family had to come out defending itself against anonymous social media users or short-sellers?
It is certainly a sign of changing times. Despite having billions of dollars outstanding, New World’s bonds are not rated by any of the big three agencies – perhaps because it thought there was no issue with demand, and its name brand alone spelled prestige and creditworthiness. But with the city’s interest rates on the rise, and after China’s property blow-ups, investors get cold feet easily. They are starting to worry about Hong Kong’s real estate sector, too.
Can Adrian’s faith in the city and his artistic, luxury bets pay off? Investors are sceptical. BLOOMBERG
TRENDING NOW

UOB found ‘grossly negligent’ over Stamford Land rights issue advice, to pay S$1.9 million

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

NoMad Singapore marks brand’s arrival in Asia

