

Net demand for Singapore office space doubles in Q3 as central region rents rise 0.8%
A 775,000 sq ft withdrawal of stock also helps push islandwide vacancy rate down to 10%
[SINGAPORE] Islandwide net demand for office space in Singapore hit 182,986 square feet (sq ft) in the third quarter of this year, up from 86,111 sq ft in the previous quarter and taking the tally for the first nine months to nearly 549,000 sq ft.
This is the best first-nine-month showing since 2023’s 796,529 sq ft.
The net demand – as reflected by the change in occupied space – in the first nine months of 2026 has already exceeded the 96,875 sq ft for the whole of 2025, based on property consultants’ analysis of Urban Redevelopment Authority (URA) data released on Friday (Oct 23).
The strong demand came from sectors such as professional services, tech, including artificial intelligence, and financial services, including insurance companies.
While net demand surged, net supply – the change in available office space – shrank by about 775,000 sq ft in Q3 2026.
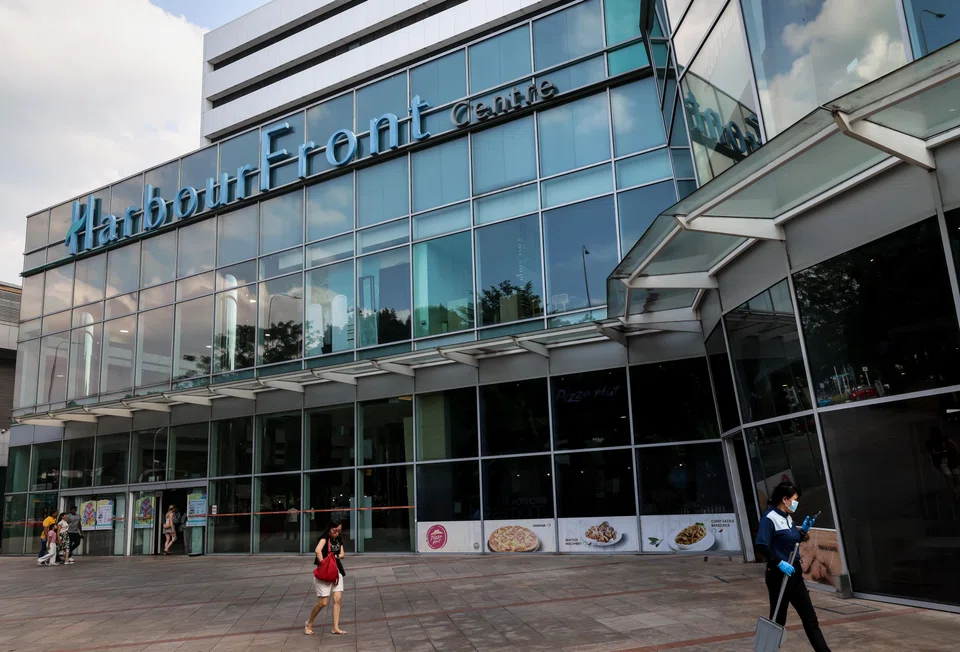
CBRE said that the contraction reflected withdrawals of office stock likely linked to the redevelopments of HarbourFront Centre and 79 Anson.
Summing up, Wong Xian Yang, head of research for Singapore and South-east Asia at Cushman & Wakefield (C&W), said: “The combination of positive net demand and shrinking supply pushed islandwide office vacancy down to 10 per cent as at end-Q3 2026, from 11 per cent a quarter earlier and to its lowest level since Q1 2024.”
The strong demand for offices in Q3 was concentrated in the Downtown Core planning area, which includes places such as Marina Bay, Raffles Place, Shenton Way, Anson Road and part of Beach Road.
It recorded 96,875 sq ft of net demand in Q3 2026, or about 53 per cent of islandwide net demand of 182,986 sq ft for Q3 2026, noted Wong.
“This marks the sixth consecutive quarter of positive net demand for the Downtown Core, likely supported by higher take-up at new developments such as Shaw Tower and Keppel South Central, particularly from technology occupiers,” he added.
Newmark head of Singapore leasing June Chua highlighted that private-sector office vacancy in the Downtown Core tightened to 9.4 per cent at the end of Q3 2026, from 9.9 per cent as at end-Q2 2026. “Vacancy in the Downtown Core has begun to stabilise and edge lower as space in recently completed buildings such as Shaw Tower is gradually absorbed, amid a tight supply of Grade A office space,” she noted.
URA’s latest data also showed that office rents in Singapore’s central region rose 0.8 per cent quarter on quarter in Q3 2026. This was the same as the quarter-on-quarter gain for Q2.
Taking a deeper dive into the URA numbers, Newmark pointed out that the monthly median rent for Category 1 offices – which cover better-quality office buildings in the city area – increased 0.8 per cent quarter on quarter to S$12.80 per square foot (psf) in Q3 2026.
Year on year, the increase was 10.9 per cent from S$11.54 psf in Q3 2025. The analysis was for leases of more than 5,382 sq ft up to 10,764 sq ft.
In the same lease size range, but for Category 2 offices – which refer to the remaining office space in Singapore that is not in Category 1 – the median rent rose 7.8 per cent quarter on quarter to S$8.30 psf in Q3 2026. Year on year, the increase was 5.5 per cent from S$7.87 psf in Q3 2025.
Newmark’s Chua observed that larger occupiers seeking space in the core Central Business District will face fewer options, given the limited supply completion before 2028.
What will happen post-2027?
“Upcoming developments such as One Comcentre, together with improved transport links, could strengthen established office hubs outside the core CBD, giving occupiers more choices and making these locations stronger alternatives to a traditional CBD address,” Chua added.
CBRE Research said that while AI companies featured prominently in Q3, financial services occupiers remained the largest source of Singapore office leasing demand in the first nine months.
Tricia Song, CBRE research head for Singapore and South-east Asia, noted that following the completion of Shaw Tower in Q2 2026, the next notable new supply in the CBD will be Newport Tower in 2027. “With limited new supply completion on the horizon, occupiers are increasingly targeting projects due from 2028 onwards – including One Comcentre, The Clifford and The Skywaters,” she added.
In a similar vein, Wong of C&W said: “Market activity suggests occupiers are planning for future space requirements, with developments such as One Comcentre, The Clifford and Union Square Central reportedly attracting leasing interest ahead of completion.”
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Singapore’s central gas buyer affirms Indonesia’s role as ‘important partner’ amid export review warning

Why the biggest business decision about AI isn’t which model to choose

Is Manila Asia’s new dining hot spot?

KKR founders among investors buying 42% of Peter Lim’s Valencia; club valued at US$1.4 billion

