

New private home prices to hit new highs in 2026 as supply tightens
Fewer project launches and higher land costs could provide a boost, even as sales volumes ease
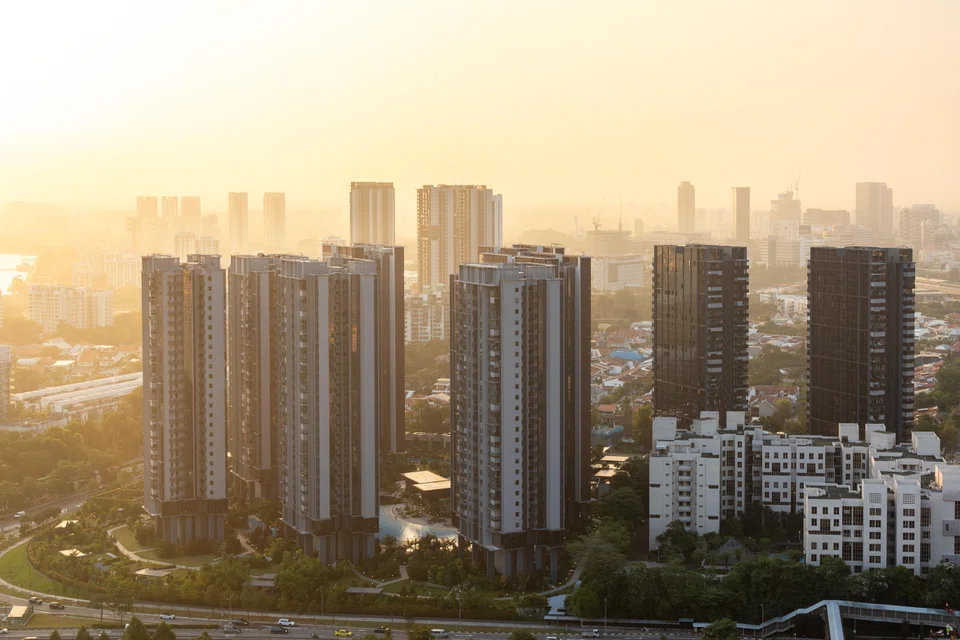
[SINGAPORE] Prices of new private homes are poised to reach fresh highs in 2026, as supply tightens amid still-firm demand and growing cost pressures.
This follows a banner 2025, with strong sales across 25 newly launched projects, excluding two executive condominium (EC) developments.
The new launch pipeline will thin in 2026, with about 19 private residential projects – including one landed development – and up to five EC launches, said ERA chief executive officer Marcus Chu.
These include the 875-unit Chencharu Close mixed-use project; Sing Holdings and Sunway’s 1,055-unit Chuan Grove; and the 1,240-unit project at the former Thomson View condominium.
In the EC market, potential launches include Coastal Cabana at Jalan Loyang Besar, Rivelle Tampines, and others at Senja Close, Woodlands Drive and Sembawang Road.
Altogether, Lee Sze Teck, Huttons Asia senior director of data analytics, expects around 9,500 new private homes, excluding ECs, to hit the market in 2026 – 17 per cent lower than the 11,500 units launched for sale in 2025.
PropNex chief executive Kelvin Fong said developers remain mindful of buyers’ price sensitivity and keeping prices “palatable”, especially during launch weekends.
Around 64 per cent of new units to be launched will be located in the Outside Central Region (OCR), marking a 55 per cent increase from 2025’s 4,040 units.
Lee noted that there will also be a 68.9 per cent rise in the number of HDB flats reaching their five-year minimum occupation period next year.
Slightly over one-fifth (21 per cent) of new private homes are in the Rest of Central Region (RCR), and 14 per cent are in the prime Core Central Region (CCR).
With fewer projects coming to market, primary sales could ease to around 7,500 to 9,000 units next year.
New launch prices are projected to rise by up to 5 per cent, setting fresh benchmarks across market segments.
SRI head of research and data analytics Mohan Sandrasegeran pointed out that, in the CCR, average land rates rose 7.9 per cent to S$1,521 per square foot per plot ratio (psf ppr) in 2025.
Benchmark bids were recorded at government land sales (GLS) sites such as Holland Link (S$1,432 psf ppr) and Bukit Timah Road (S$1,820 psf ppr).
Based on these costs, Sandrasegeran said CCR prices could reach around S$3,500 psf next year.
In the RCR, average land bids rose 8.3 per cent to S$1,234 psf ppr, with rates crossing the S$1,300 psf ppr for GLS sites at Dorset Road (S$1,338 psf ppr) and Telok Blangah Road (S$1,326 psf ppr).
Sandrasegeran said this could result in average new launch prices of about S$2,600 psf in 2026, broadly in line with 2025 levels.
The steepest land price growth was recorded in the suburbs, where average land rates jumped 26.6 per cent to S$1,140 psf ppr.
“This reflects stronger competition for mass-market sites, supported by resilient first timer buying demand and a tighter supply of well-located parcels,” said Sandrasegeran.
Meanwhile, Cushman & Wakefield (C&W) research head Wong Xian Yang said cuts in interest rates, stabilising construction costs and robust new launch performance have fuelled developers’ interest in acquiring land, driving costs even higher.
Average launch prices in the OCR are therefore predicted to reach around S$2,400 psf in 2026, up 6 per cent from the 2025 average of S$2,263 psf.
That said, CBRE research head for South-east Asia Tricia Song noted that some of the higher land bids this year were a recovery from the low base of 2023 and 2024, particularly in the CCR.
PropNex’s Fong added that many new homes sold in 2026 are likely to remain anchored below S$2.5 million, similar to 2025, when about 67 per cent of private non-landed new homes were transacted at that level and close to the 68 per cent seen in 2024.
Huttons’ Lee said developers’ balancing act between competing for land and buyer affordability has squeezed margins into single digits.
C&W’s Wong noted that construction costs, though stabilising, remain 33.4 per cent above 2019 levels.
Combined with high labour costs, developers’ margins are expected to stay tight even as borrowing costs ease, Fong said.
Race for land
Developers have been active in recent state land tenders.
Fong said that, on average, GLS sites excluding ECs drew around five bids and a land rate of S$1,244 psf ppr in 2025, up from 2.7 bids and S$1,127 psf ppr in 2024.
The latest tender at Bedok Rise attracted 10 bidders, the highest since 2021, Lee noted.
CBRE’s Song explained that developers are “hungry to replenish their depleted land banks following strong take-up at recent launches”.
She added that robust 2025 sales – with new home transactions reaching a four-year high of 11,430 units – reflect ample liquidity and positive buyer sentiment, boosting developer confidence.
Tariff-related uncertainty has also eased since early 2025, following the de-escalation of US-China trade tensions, giving developers greater certainty, Song said.
Nicholas Mak, Mogul.sg chief research officer, said active participation by developers at state land tenders is likely to continue in 2026, especially since several sites on the confirmed list of the H1 2026 GLS programme have strong location attributes.
These include an integrated mixed-use development at Bayshore Drive, which could yield 1,280 homes and 22,500 sq m of commercial space, and a 2.54-hectare plot on the former Keppel Club site, which will house some 415 units.
Christine Sun, chief research and strategist at Realion (OrangeTee & ETC) Group, added that there also “seems to be an increase in participation from foreign and smaller developers”.
Sales blockbuster
The projections follow a “blockbuster year” for developers, with over 10,600 new homes, excluding ECs, sold in the first 11 months of 2025, which Fong noted was the first time in four years that sales crossed the 10,000-unit mark.
The CCR, in particular, witnessed a “dramatic recovery” this year, with developers selling nearly 1,900 new homes in that period, on track to its strongest showing since 2021, he said.
Alan Cheong, Savills Singapore executive director of research and consultancy, said Singaporeans are willing to buy prime CCR homes at median prices of S$3,000 psf or S$2.35 million, and a median size of 730 sq ft.
Fong attributed the upturn to a narrowing price gap between the CCR and RCR, which has “reshaped value perceptions among buyers”. Based on caveats lodged, the difference between the median price of new non-landed private homes in the CCR and RCR was just 10 per cent – the narrowest on record since 1995.
Also, Huttons’ Lee highlighted that household wealth has grown “tremendously” since 2023. As at Q2 2025, the currency and deposits of households stood at S$680.2 billion, up 15.4 per cent or S$90.6 billion from Q1 2023.
“This increase in wealth can be used to purchase 9,000 private non-landed homes worth S$10 million each,” said Lee. “Despite the cooling measures… buyers were not deterred, adopting a mid-term to long-term view on their investments.”
ERA’s Chu noted that of around 25 private housing projects launched this year, 10 sold at least 80 per cent of units on launch day, with five achieving over 90 per cent. Only five projects surpassed an 80 per cent take-up rate at launch in each year from 2020 to 2024.
Fong added that, since their respective launches, 14 projects had sold at least 70 per cent of units as at late November. These include Lentor Central Residences, which is fully sold; LyndenWoods and Skye at Holland, which are both nearly sold out at 99 per cent; and Parktown Residence, which has moved 93 per cent of its 1,193 units.
“We have not seen so many new projects achieving such high take-up rates all within the launch year in recent memory,” said Fong.
On the supply side, C&W’s Wong noted that total unsold inventory remains below the decade-long average of 22,451 units, and is likely to tighten further in Q4 2025 due to robust new-home sales.
Beyond that, CBRE’s Song said supply has been constrained by fewer collective sale sites in recent years.
The GLS confirmed list supply, including ECs, was also subdued between 2020 and 2021, bottoming out at 3,100 units in FY2020 before picking up from H1 2021, Song said.
But unsold inventory could rise in 2026 as demand normalises and supply from GLS sites sold in 2023 and 2024 come on stream.
Still, Song said developers are unlikely to offer discounts, as homebuying demand is expected to remain firmer than the lows of 2022 to 2024 amid more “conducive” interest rate conditions.
She predicts private home prices will grow 2 to 4 per cent, versus 2025’s 3 to 4 per cent increase.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

