

Pictet sees more special-situation opportunities in European property
Capital shortages are creating openings to buy assets below market value, says real estate head
[SINGAPORE] A shortage of fresh capital flowing into real estate is making it harder for property owners to sell assets, creating opportunities for investors to acquire properties below market value, said Zsolt Kohalmi, global head of real estate and deputy CEO of Pictet Alternative Advisors (PAA).
Broken sale processes, strained capital structures and expiring loans have created openings for investors to step in. Against this backdrop, PAA’s recent real-estate transactions have all involved special situations, which include deals on attractive properties going at below market value.
“What I think is paramount for any investor that wants to make the right returns from today’s market is to really focus on special situations,” Kohalmi said.
PAA would typically come across two to three such opportunities in a year, but heard of three deals within just two weeks recently.
For a deal to qualify, the underlying property must be “attractive” and there needs to be a “truly broken process”, noted Kohalmi.
This comes as liquidity is being drawn away from real estate, with money flooding into artificial intelligence infrastructure and governments seeking to finance deficits. Meanwhile, investors seeking current income are eyeing money market funds and fixed-income products as alternatives.
As a result, pricing has become a more important consideration in PAA’s acquisition strategy. Investors would need to buy properties in Milan at around 10 to 15 per cent below market value, while in London they would need a discount of more than 20 per cent, he said.
European real estate may also be nearing the bottom of its cycle, although valuations could still fall further. Investors who wait for sentiment to improve risk missing the better buying opportunities, he cautioned.
“When others aren’t there, that’s when you get the special deals.”
On financing, European banks were less aggressive in their lending than US lenders and still need to deploy capital. This has allowed PAA to secure loans at favourable rates for its transactions, Kohalmi added.
Looking beyond AI trade
Kohalmi noted that, while the effects of AI on offices, retail and the logistics space remain uncertain, residential, student and senior housing could offer a potential diversifier from the AI trade. PAA groups these assets under the theme of “beds”.
“What we definitely know is that we’re going to need to sleep somewhere,” he said, adding that AI could also give people more time for experiences, supporting demand for hospitality.
Europe remains an attractive place to spend time, with demand for hospitality and living in its cities coming from a global pool, he noted.
But the region also faces widespread housing shortages, with Finland a notable exception, he said. In gateway cities such as Berlin, Copenhagen and Geneva, residential vacancy rates are below 1 per cent.
Supply is further constrained by lengthy planning processes. Obtaining a building permit takes an average of five to 10 years in Europe, compared with six months to a year in the US, he pointed out.
Scandinavia remains a preferred market for rental residential properties. Also on PAA’s radar are Madrid and Milan, where year-round sunshine and lower taxes have drawn people from other parts of Europe.
PAA is also looking at data centres in Europe, although the region faces a significant constraint: power supply. Scandinavia is better positioned in this regard because its reliance on hydropower means it faces fewer grid constraints.
But he noted that Europe lags behind the US in the data centre investment cycle.
Creating value through repositioning
For investors assessing real-estate deals, simply waiting for interest rates to fall or valuations to recover may not be enough.
Kohalmi said that investors should focus on creating value through the assets themselves, rather than relying solely on movements in interest rates.
“We have to go back to old-school value-add… The real value-adding is independent of the broader market.”
One example is a former Ministry of Justice building in Madrid, which PAA acquired about a year ago. The vacant office building is being converted into high-end residential apartments.
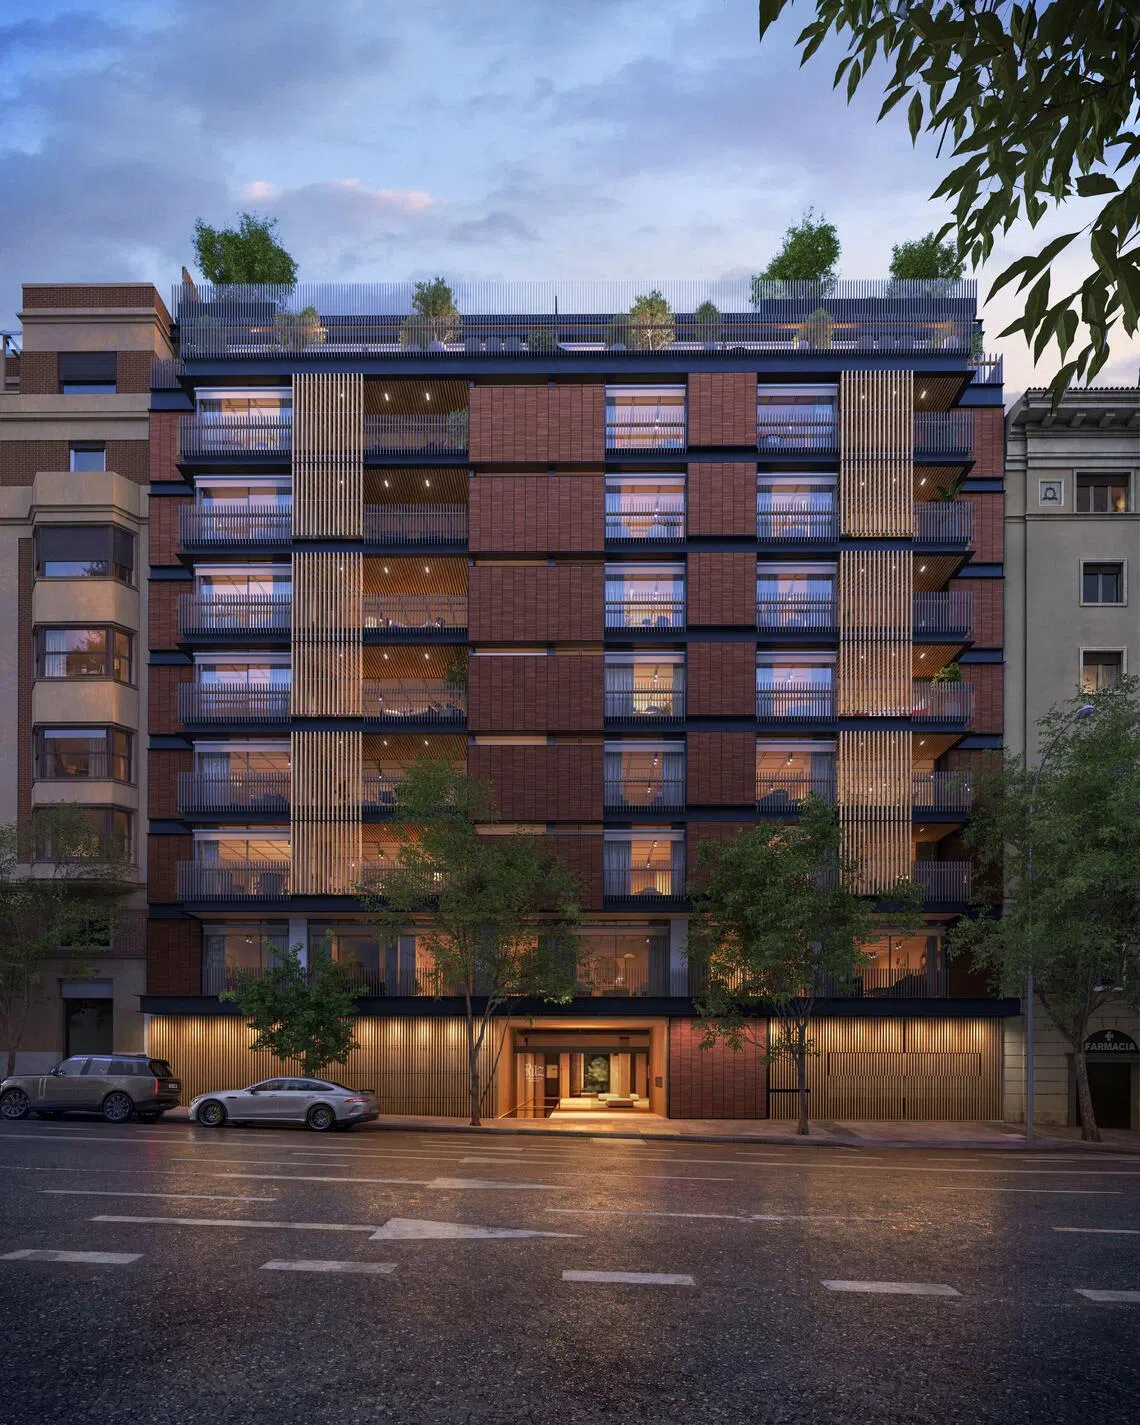
In Italy, PAA’s direct real-estate strategy, in partnership with Kryalos SGR, acquired seven historic residential buildings across prime central Milan. The portfolio spans about 26,000 square metres of gross area and comprises around 150 residential units, alongside ground-floor retail space.
The planned improvements include upgrading apartments and common areas, enhancing resident amenities and modernising selected spaces, while preserving the buildings’ architectural character.
Hospitality is another area where PAA sees scope to enhance existing assets.
In June, the acquisition of the 266-room Zurich Marriott Hotel involved a direct real-estate vehicle and PAA-advised capital, with Vertell Asset Management as operating partner.
A guestroom renovation programme is under way and will be completed by the owner to keep the hotel in line with evolving five-star standards. Marriott will continue to operate the hotel.
But identifying an asset’s potential is only one part of the process.
About 70 per cent of PAA’s deals are sourced off market, and such planning can take anywhere from six weeks to four months, Kohalmi said.
One example is a former printing facility in Stockholm that was converted into a data centre. The team had to determine whether its 16-metre internal height could accommodate three levels of data centre facilities, identify a potential operator and establish that no building permit was needed.
This preparation time is crucial, Kohalmi pointed out, as such assessments would be difficult within the tight bidding windows of a typical competitive sale.
Exits become less certain
Even after that work is completed, finding an eventual buyer is no longer a given. Real-estate exits have slowed, Kohalmi said, making it harder for investors to rely on established exit routes.
Investors previously expected to spend three to four years on value-add work, stabilise income and sell to a core investor or sovereign wealth fund. With this route less certain, they need to accelerate their business plans while leaving more time to find the right buyer.
At PAA, the firm reviews every asset in its real-estate strategies quarterly to assess whether changes in a property’s location, tenant outlook or other conditions could warrant an exit, Kohalmi said.
For assets it intends to retain, PAA looks to buy properties with long-term leases, typically around 10 years, strong tenant covenants and locations that are difficult to replicate.
The aim, Kohalmi added, is to own properties that can continue to perform even if the wider market or economic environment is disrupted.
TRENDING NOW

South-east Asia has lost Nvidia’s best salesman
UN says Singapore’s Penguin International broke Libya arms embargo; company disputes panel’s findings
Is Singapore still South-east Asia’s headquarters haven?
CapitaLand, Far East, Sing Holdings team up for S$1.82 billion bid for Jurong Lake District site

