

Singapore's Q Investment Partners gets set for Japan housing foray
Aims to enter Japan market next year with initial focus on multi-family housing and student accommodation, while doubling down on UK student dorm, US co-living properties
Singapore
Q INVESTMENT Partners (QIP) will soon dip its toes into the Japanese residential scene, while doubling down on its key markets of UK purpose-built student accommodation (PBSA) and US co-living properties.
The Singapore-based private equity real estate firm plans to enter Japan next year, with an initial focus on multi-family housing and student accommodation, its chief executive and co-founder Peter Young said.
Speaking to The Business Times, he also noted that in the months ahead QIP will expand its global headcount as it fully integrates its execution capabilities across development management and asset management.
The 5-year-old group, which develops and operates properties, focuses on residential real estate that is up for rent. Dubbed the beds or "living assets" sector, that includes housing for students, young professionals, multiple families and seniors.
QIP favours developed countries; the UK is its primary market. "We like the UK and US bed sectors because they are deep and offer the opportunity to get value and incremental growth through rental increases, providing predictable income and an inflation hedge," Young said.
The firm has some US$300 million of assets under management, and its funds have generated 13 to 20 per cent internal rates of return. For the core-plus UK PBSA strategy, QIP's portfolio value amounts to about £100 million (S$182 million).
In terms of deal sizes, its investments hover around £30 million to £40 million in transaction value for each single-asset development project in the UK PBSA sector, and about US$100 million for US co-living.
Young described QIP as a nimble player that is able to start by investing in smaller doses before scaling up over time, and also "help institutional investors invest alongside us".
A large portion of its investor base comprises North Asian and South-east Asian capital. By investor type, participants have included financial intermediaries working with private clients and family offices, as well as real estate-focused corporates and institutional investors.
On the upcoming foray into Japan, he noted that while some aspects of the country's residential market may be poles apart from those in the US and the UK, it has the potential to offer the same main characteristics most investors are seeking.
Pointing to the predictable, recurring and strong rental income from the Japanese beds sector, he likened such assets to fixed-income plays in a safe-haven market. "It's a very deep and liquid market, with plenty of predictability in its attributes such as the rent and leasing structures, and just knowing that a particular building in a particular location will be able to secure a certain level of income."
That being said, rental increases in Japan may not be as compelling as in the US and the UK, where exponential growth is more likely to occur. "For US co-living or UK student housing, there may be inferior products elsewhere in the market, which means you can raise rents if you're able to create a better product," he told BT. Some areas in Japan are also especially tenant-friendly, limiting the landlord's ability to increase rents.
QIP is also eyeing a few sub-segments unique to Japan, including company dormitories - that is, corporate-anchored residential properties typically for office workers.
Overall, QIP caters to a variety of real estate investment strategies, which differ in risk and return characteristics, Young said.
"We're involved at the development stage, through to buying and holding assets for income, and also increasing capital values."
Much of the firm's initial focus had been on ground-up developments, though it has since evolved to invest across the whole spectrum. Buying land plots, obtaining planning permission and then building the assets from scratch, fall under the opportunistic strategy, which is considered the riskiest. "Typically, we don't bring investors in at that stage, because it's very, very opportunistic," he noted.
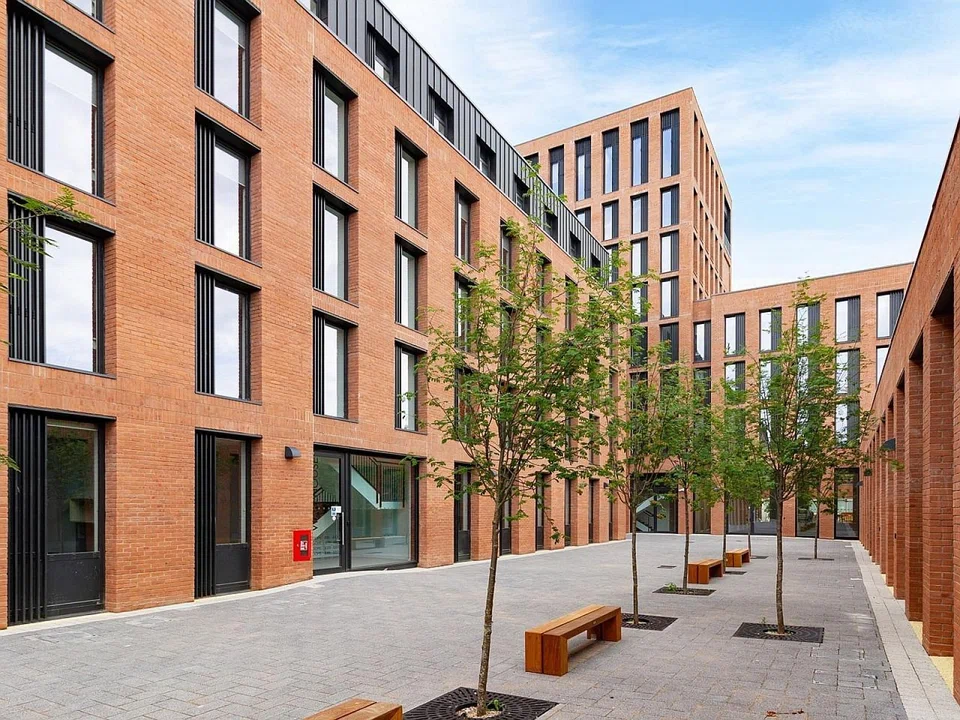
Where QIP usually starts to actively engage investors is when it can start developing the underlying real estate product. "That's after the site has obtained planning consent and is essentially ready for groundbreaking, when we know we're building, for example, a 400-bed scheme in Nottingham that will be funded by debt, and so on," Young added.
The strategy shifts towards core-plus - with a low to moderate risk profile - after the property is completed and becomes fully operational. At this stage, QIP tends to see ample interest from investors.
Another growing area of focus for QIP is in acquiring existing buildings before conducting extensive refurbishment. This tends to fall under the value-add strategy. "These opportunities definitely exist in UK PBSA, particularly in the so-called first-generation student housing assets," he told BT.
In the early days of the UK PBSA sector, projects were fairly simple and straightforward and could be built in locations around top-tier universities. But the quality and features of newer student housing have substantially improved over the years, in tandem with changing user requirements and expectations. Some of the well-located properties built more than a decade ago are thus run-down, outdated and "need a bit more than just a fresh coat of paint and facade changes", he said.
QIP thus evaluates whether the building sits on "a good site where there will be uplift with sensible amounts of capital expenditure and we can get a predictable income going".
Young said students today want affordable, flexible, good-quality housing suited for the way they work, live and play. That also means their space requirements have evolved; instead of each person taking up a room, an individual may want two rooms now, and a couple may lease three rooms. First-year undergraduates new to the city may opt to live alone, but a group of friends in their subsequent academic years could rent and share an entire floor.
"It's about making demand 'sticky' by creating a product tailored for the users so they are happy to stay. It'll be a big positive if you can retain them for 3 to 4 years, versus the average rental duration of 6 months to 2 years for most housing assets," he said.
UK student housing typically sees year-on-year rental growth of 2 to 4 per cent, Young added. He also highlighted the uptick in local and international student applications and enrolment as indicative of the resilience in demand for PBSA beds there.
The operational UK student housing assets in QIP's portfolio had an average occupancy rate of 96 per cent for the 2021/2022 academic year.
Young said what sets the firm apart is it "lives and breathes" the beds sector. He is confident residential assets will continue to produce robust risk-adjusted returns, "as long as you create the right product in the right location for the right user".
READ MORE:
- Singapore firm QIP launches £30m fund for student accommodation in the UK
- International students flocking back to London find themselves in a race for scarce housing
- Singapore property players can still score from student housing in overseas markets






