

Is the UK student-housing party over? Singapore players face divergent prospects in PBSA market
Shrinking demand and new supply are leading to lower occupancies and falling rental growth
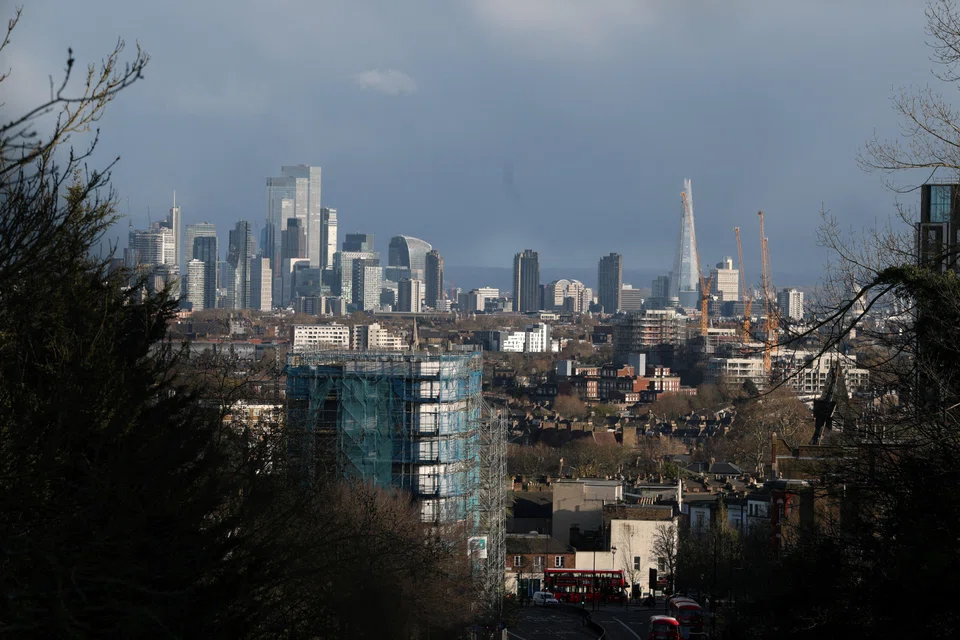
[SINGAPORE] A boom that lifted all boats in the UK student housing sector is slowly fizzling out, with growth fading in a market where several Singapore players have made major bets.
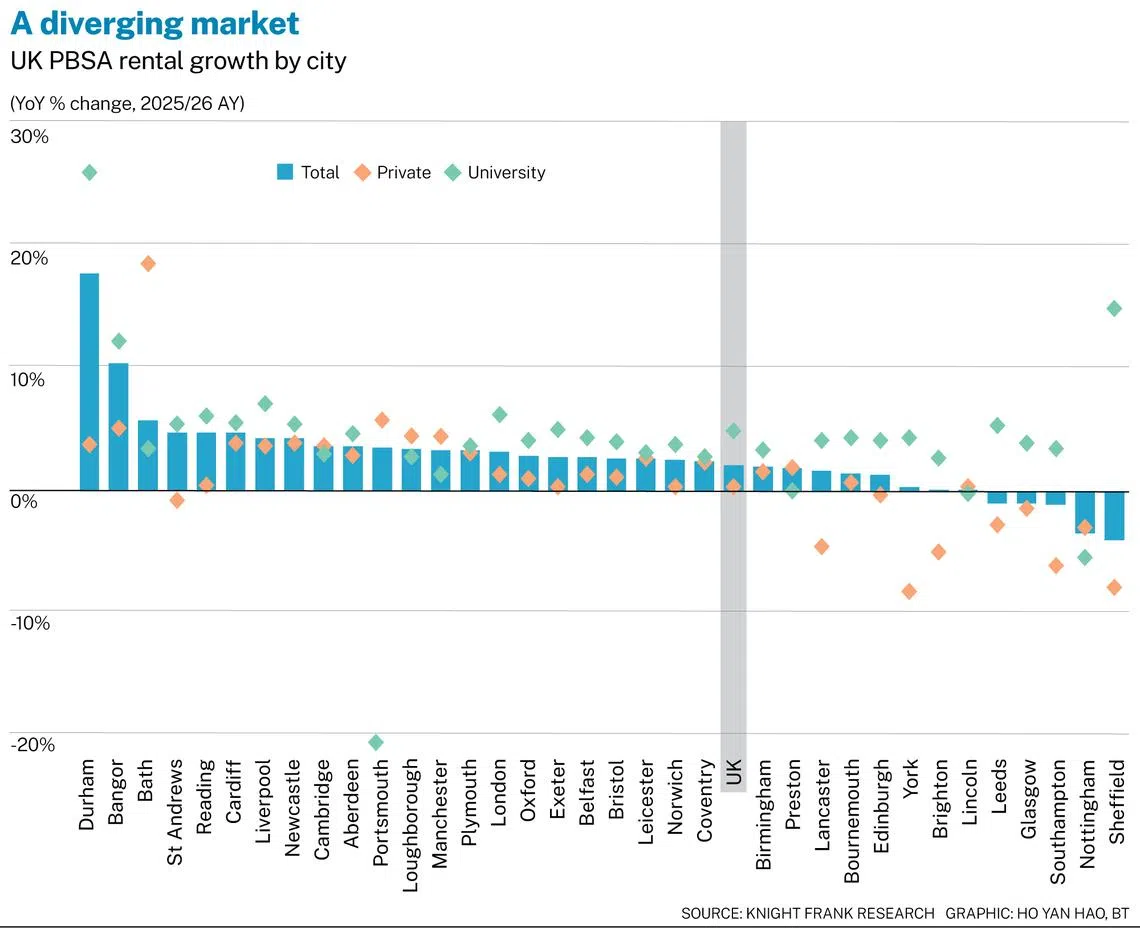
After years of broad-based expansion stemming from an undersupplied market, the purpose-built student accommodation (PBSA) sector is entering a more selective phase. Persistent bed shortages continue to support rents and occupancy in some cities, while affordability pressures, softer demand and new supply are posing a challenge in others.
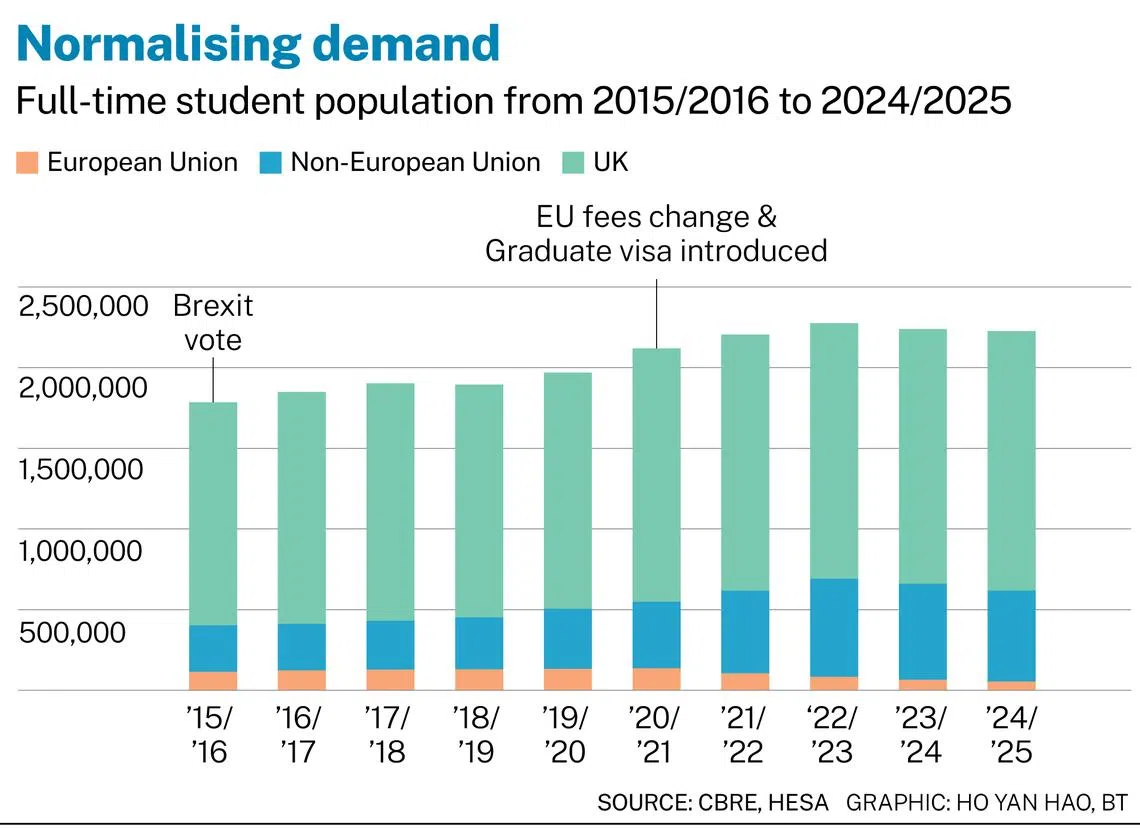
The shift comes as overall student demand begins to normalise after a post-pandemic surge, at a time when new supply from market players expanding is coming on stream.
In Nottingham, for instance, it is estimated that demand for first-year undergraduate accommodation fell from a Covid-era peak of 46,295 beds in the 2022/2023 academic year to 42,290 beds in 2025/2026, according to Martin Blakey, the former chief executive of student housing charity Unipol.
During that period, PBSA supply in Nottingham increased by more than 7,700 beds, accounting for 13.8 per cent of all new-build beds in the UK.
Some EU students are choosing to study elsewhere due to changes in their tuition fees, said property consultancy CBRE. Under post-Brexit rules, EU students pay the same tuition fees as international students when studying in the UK, which left the European Union in 2020 after a vote in 2016.
More students are also choosing to live at home. In an article published in April, Blakey noted that the share of first-year students intending to live at home rose from 32.9 per cent in 2016 to 35.2 per cent in 2025.
“Although this does not seem like a large shift, this alone would account for a decline in demand of around 24,000 bed spaces,” he said. He estimated that this could translate to a reduction in demand for around 72,000 beds, if applied across a typical three-year undergraduate cohort.
The changing dynamics are already showing up in operating performance.
Far East Orchard (FEOR) is positioning to be one of the largest players in the UK via a phased acquisition of UK operator HFS, which manages some 55,000 beds. FEOR currently owns 84 per cent of HFS, and aims to acquire the remaining 16 per cent stake by 2030.
It also owns 13 assets with over 3,700 beds. For its owned portfolio, occupancy fell to 88 per cent for the 2025/2026 academic year, lower than the 92 per cent recorded in the previous year, according to FEOR’s first-quarter update. Pre-leasing for 2026/2027 is tracking “slightly ahead” of the same period last year.
Unite Group, the UK’s largest PBSA provider with around 71,000 beds across 29 university towns and cities, said in February that a record number of UK 18-year-olds started university in the 2025/2026 academic year, with new undergraduate student numbers growing 2 per cent.
But this was offset by weaker sales to international postgraduate students and more students choosing to live at home, which have weighed more heavily on lower-ranked universities, it added.
For Unite, occupancy fell to 95.2 per cent for the 2025/2026 academic year, from 97.5 per cent a year earlier. Rental growth has also slowed to 4 per cent, from 8.2 per cent over the same period.
Unite expects occupancy for the 2026/2027 academic year to come in towards the lower end of its 93 to 96 per cent guidance range. Rental growth is also expected at the lower end of its 2 to 3 per cent range, translating to like-for-like income growth of 0 to 2 per cent, compared with 0 to 4 per cent previously.
The group said vacancies were concentrated in three regional cities – Leicester, Nottingham and Sheffield – where “weaker demand combined with high levels of existing and new supply”.
It also saw lower occupancy in new buildings and those where major capital projects had been carried out, which were slower to lease in a more competitive market.
Mapletree Investments, which now owns around 17,000 beds across 27 cities in the UK, noted “more balanced” conditions emerging in certain larger regional markets, where new delivery has been active and the student base is less internationally diversified.
“This is most evident in parts of Birmingham and Liverpool, as well as some secondary university markets such as Nottingham and Sheffield, where supply has caught up more quickly with demand,” a spokesperson said.
The group is in the process of divesting a portfolio of UK and US assets totalling some 14,000 beds at inception, as part of the end-of-fund-life winding down of a closed-end fund invested in global student accommodation.
The spokesperson said Mapletree remains committed to student housing, which it has identified as one of four core sectors, and is not exiting from the sector. The group also plans to structure a UK student housing fund comprising a portfolio of premium assets serving the Russell Group universities. The fund is targeted to close by the end of the year.
Mapletree sees the strongest long-term fundamentals in globally recognised university cities, such as Oxford, Cambridge, Bristol, Edinburgh and Durham. “These markets continue to exhibit undersupply… where demand remains structurally deep and supply is constrained.”
Singapore-listed Centurion Corp has a UK portfolio of 10 assets with 2,782 beds spanning Manchester, Nottingham, Liverpool, Newcastle and Bristol.
“Nottingham and Bristol are examples of cities where new supply has come on in recent years, bringing the market closer to balance,” said chief executive Kong Chee Min.
While rental reversions have been strong in the past two years, Kong expects rental growth to moderate “as the broader sector normalises”.
For City Developments Ltd (CDL) , average occupancy of its portfolio has fallen to 82 per cent for the 2025/2026 academic year as at March 2026, from 90 per cent in the prior year. CDL owns six PBSA properties with 2,368 beds across Birmingham, Canterbury, Coventry, Leeds and Southampton.
Over the past three years, Centurion’s UK PBSA portfolio has maintained financial occupancy of more than 90 per cent, reaching 98 per cent in FY2024, FY2025, and the first quarter of FY2026.
Centurion Accommodation Real Estate Investment Trust (Reit) , its pure-play living sector trust, also recorded 99 per cent occupancy across its eight UK PBSA assets.
Money talks
Affordability is a key pressure point, after several years of rising rents and wider cost-of-living pressures.
These pressures are pushing students to book accommodation later in the cycle and look for incentives, which operators are increasingly offering, CBRE said. These range from local food vouchers and bike hires, with up to £1,500 (S$2,575) cashback upon completion of booking.
Students are also looking elsewhere for cheaper accommodation.
A report by the British Property Federation showed that students accounted for 30 per cent of tenants in build-to-rent (BTR) multi-family housing across the UK, and up to 40 per cent in some urban areas such as Leeds.
Nick Hillman, director at independent think tank Higher Education Policy Institute, said in February that “the party’s over” for student accommodation providers, “even if the hangover has yet to sink in”.
Higher build and regulatory costs, and interest rates have raised the price of new accommodation, making other countries or options such as co-living and BTR look more attractive, Hillman noted.
Cardiff is one market where some investors still see scope for growth.
The city has around 40,000 students across its universities and about 20,000 beds, but much of the existing stock is older. Around 17,500 beds are more than 10 years old, and only about 3,000 beds are newer than that.
New stock is limited. According to investment company Harris Associates, Cardiff’s broader pipeline stood at 1,287 beds at various stages of planning and approval, including Singapore-listed Elite UK Reit’s planned 348-bed facility in Newport Road.
Operators are now concentrating capital in cities with deeper university catchments and more resilient student demand.
Unite aims to increase the share of its portfolio weighted towards high-tariff universities from the current 67 per cent, to 80 per cent over the medium term. “This realignment is a key enabler of our return to higher occupancy,” it said.
At the same time, Unite noted that new PBSA supply was down 50 per cent from pre-pandemic levels, reflecting viability challenges from higher construction and funding costs, as well as delays in approvals.
“Weekly rents now need to be at least £230 for new PBSA development outside of London to be viable, meaning there is little prospect of new PBSA supply in many markets,” it added.
While Centurion continues to look for opportunities in the UK, “in an environment where high financing costs compress yields, and PBSA assets continue to be highly pursued by institutional funds, we may choose to defer acquisitions”, Kong said.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

What role can Japan play in Asean’s future?

