

Singapore’s factory output growth accelerates to 15.4% in August, but undershoots estimates
Economists note unevenness across sectors, with electronics and precision engineering driving expansion
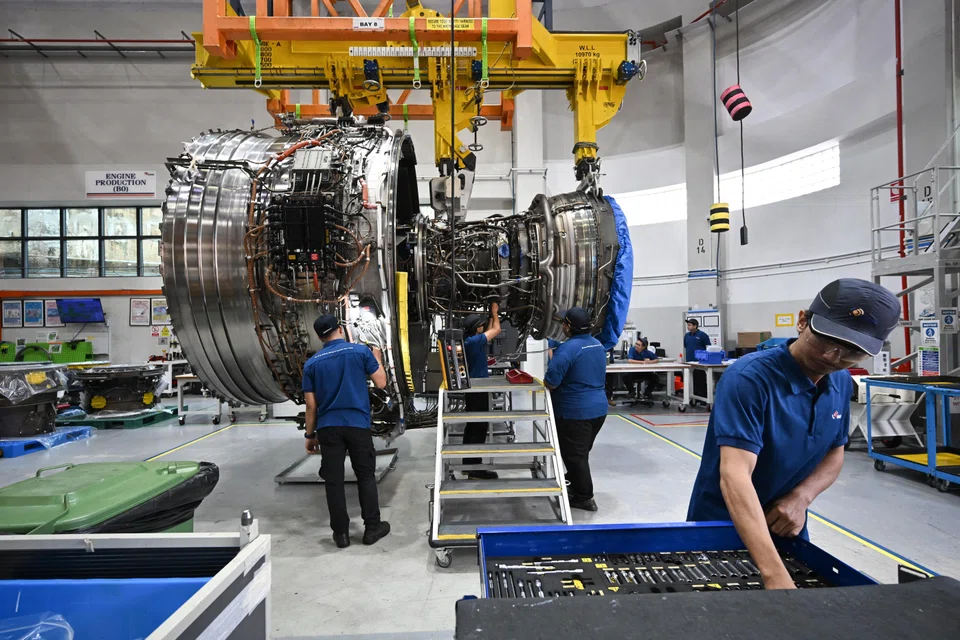
[SINGAPORE] The Republic’s factory output surged 15.4 per cent year on year in August, picking up from July’s revised 6.9 per cent growth – but falling below consensus estimates for a median 18.3 per cent expansion in a Bloomberg poll.
Excluding the volatile biomedical manufacturing cluster, output grew 17 per cent year on year, extending the 8.2 per cent increase recorded in July, data from the Economic Development Board (EDB) showed on Monday (Sep 28).
On a seasonally adjusted monthly basis, factory output slipped 0.5 per cent in August, marking a reversal from July’s 2.3 per cent gain. Excluding biomedical manufacturing, output grew 5.8 per cent, compared with an 0.8 per cent rise in the previous month.
Year on year, the latest headline print is boosted by base effects, economists agreed, with DBS senior economist Chua Han Teng pointing out that August 2025 marked the lowest monthly reading of that year.
Analysts also highlighted that artificial intelligence-related tailwinds continued to underpin Singapore manufacturing, with electronics and precision engineering benefiting.
Precision engineering marked the largest jump, up 33.9 per cent year on year, compared with the preceding month’s 18 per cent expansion.
This marked the strongest growth since January 2011, said Maybank analysts Chua Hak Bin and Brian Lee. They attributed this to the higher production of semiconductor equipment as the global expansion in chip fabrication capacity buoys demand.
Production in the linchpin electronics cluster expanded 28.5 per cent from the corresponding year-ago period, extending July’s 11.1 per cent growth and hitting a three-month high.
EDB noted that this was supported by the strong production of servers and related products, semiconductors and data storage products amid robust AI-related demand. Within the cluster, the other electronic modules and components segment reported a fall.
But Standard Chartered chief economist Edward Lee and senior economist Jonathan Koh noted: “The strong performance is concentrated in AI-related demand, and the spillovers to other industry clusters are not yet evident.”
DBS’ Chua also flagged the “uneven” performance across clusters, saying: “Biomedical and general manufacturing registered weak, low single-digit year on year increases, and chemicals contracted, although transport engineering was resilient.”
Transport engineering grew 9.5 per cent, down slightly from July’s 11 per cent, led by the land and aerospace segments.
General manufacturing industries grew 1.5 per cent in August, slower than the previous month’s 5.5 per cent, supported by higher production of beverage products, commercial printing, and metal doors and windows.
The volatile biomedical manufacturing cluster’s output edged up 0.4 per cent, led by a higher output of medical devices in the medical technology segment amid stronger export demand, partially offset by a decline in the pharmaceuticals segment.
In contrast, chemicals manufacturing continued to fall, down 12.7 per cent, weighed down by the petroleum and petrochemicals segments. This extended July’s 10.5 per cent decline.
EDB said that petroleum output was affected by plant maintenance, while petrochemicals production continued to be constrained by softer demand and feedstock supply disruptions.
UOB associate economist Jester Koh also said the intensification and broadening of the Middle East conflict, alongside the curtailment of cargo ship traffic through the Strait of Hormuz and Bab el-Mandeb, led to severe supply shortages of key petroleum refining by-products.
AI-related tailwinds prevail
Considering Singapore’s role as a “critical node” in the semiconductor supply chain, DBS’ Chua expects it to continue to benefit from strong global demand for AI-related hardware amid the ongoing global AI infrastructure build-out dominated by hyperscalers. But he warned of continued unevenness in the manufacturing sector as certain clusters grapple with rising energy and input costs, as well as supply chain disruptions.
Given the AI boom, Maybank’s team estimated that flash third-quarter gross domestic product remained resilient at 5.5 per cent (against Q2’s 5.9 per cent), “even though growth has been uneven with cost pressures and a cooling labour market dampening traditional manufacturing, consumer-facing industries, logistics and hospitality”.
“There may accordingly be upside to our base case GDP growth forecast of 5.2 per cent in 2026, which is at the top end of MTI’s (Ministry of Trade and Industry) 4.5 to 5.5 per cent forecast range,” they said.
The duo think the Monetary Authority of Singapore (MAS) will tighten “very slightly” at the mid-October meeting, by increasing the slope of the Singapore dollar nominal effective exchange rate appreciation by 25 basis points, amid rising inflation and resilient growth.
StanChart’s team said that the industrial production data “reinforce the case that growth is holding up strong but do not, on its own, make another tightening necessary (as we do not see the economy firing on all cylinders)”.
“Our call for the MAS is to hold in October, but it is a close one,” they said, noting progressive tightening moves at the last two policy reviews.
“Price pressures are rising and showing signs of broadening, but may not yet be sufficiently pervasive to change our baseline,” they added. “The risk remains tilted towards another ‘very slight’ tightening, however.”
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Can CDL become a powerhouse in fund management?

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

Data centre energy demand from Asean telcos not a ‘big risk’, says industry group

