


Financing growth: How SMEs can tap digital banks for working capital
Such lenders can streamline processes and speed up approvals, say panellists at a MariBank and BT event
[SINGAPORE] Faster access to working capital through digital banks could help small and medium-sized enterprises (SMEs) seize growth opportunities, business leaders said at a recent panel discussion.
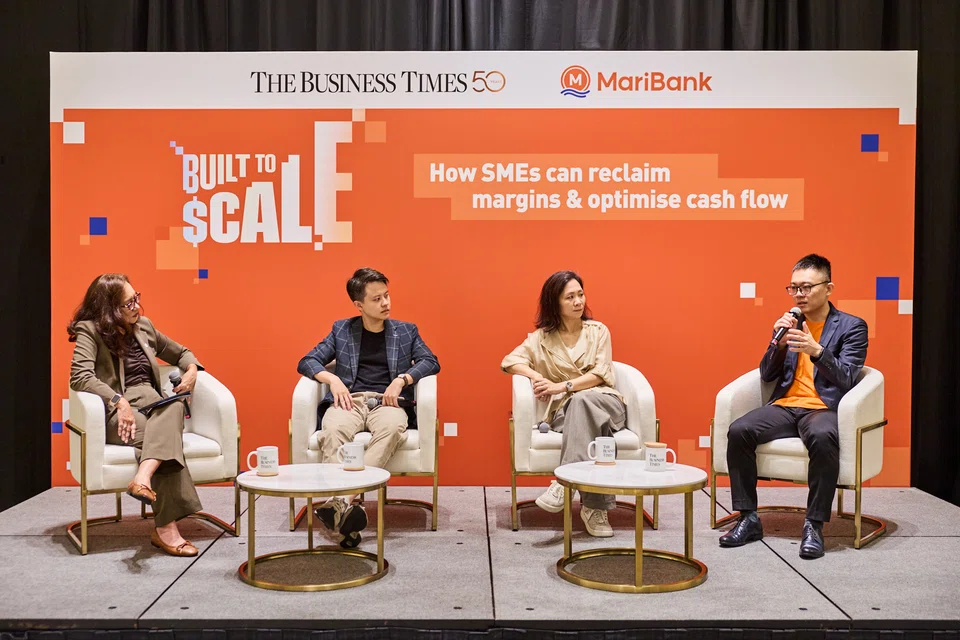
At an event organised by MariBank and The Business Times at The St Regis Singapore, they explained how digital lenders can help SMEs meet their financing needs by streamlining lending processes and accelerating credit assessments and approvals.
Such moves will allow businesses to access funds more quickly when opportunities arise, they noted.
Titled “Built to scale: How SMEs can reclaim margins and optimise cash flow”, the panel on Oct 15 explored how SMEs could leverage a digital bank’s offerings.
For Tan Yee Hern, assistant managing director of Capstone Aluminium, the importance of timely financing became clear during the Covid-19 pandemic.
The family-owned company, which supplies architectural windows and doors for Housing & Development Board (HDB) Build-To-Order projects, saw a chance to take on more orders when disruptions to regional supply chains affected its competitors.
While many of its peers faced difficulties sourcing products from East Asia, Capstone could continue operations through its factories in Malaysia, as Singapore maintained the flow of goods needed to keep construction projects moving.
“Thankfully, our projects did not get delayed, but this gave us a very big opportunity... to double down and take on more projects,” said Tan. “Now we have the advantage, and in HDB’s eyes, we can deliver.”
With its supply-chain edge, the company was able to take on four times its usual volume of orders, he added. However, the surge in business also meant a greater need for working capital.
SEE ALSO
Capstone had to procure materials, manufacture the products, deliver them to construction sites and complete installation before receiving payment. From procurement to receivables, the shortest cycle was at least 180 days or half a year, Tan said.
And as order volumes increased, so did the amount of financing required to fulfil them. For businesses operating on such long payment cycles, speed in securing financing can be critical, he added.
“Finance is very important in having things processed (quickly), especially when there’s an opportunity presented to you,” said Tan. “If you don’t have speed, you don’t have efficiency, and you might just miss the boat.”
He highlighted that this is where digital banks could have an advantage over traditional banks – in areas such as account opening and credit-line approvals.
Adopting digital banking
While speed and cost savings may appeal to SMEs, switching banks is not necessarily a priority for those accustomed to traditional banking arrangements.
Fellow panellist Sharon Teo, CEO and co-founder of Inspire-Tech, said her software company has continued to bank with a traditional lender despite the frustrations she faced with minimum-balance requirements in the business’ early years.
“Cash flow is always a challenge, and it is very frustrating seeing that we are almost reaching or below that balance,” she noted, adding that the requirements distracted the business from its operations.
Despite these issues, familiarity and convenience have kept the company from switching banks, she said. “I do not want to do a lot of work as I am busy, and after a while, you become ignorant of what is ‘cool’ out there.”
Similarly, Capstone’s Tan said businesses may not realise what they are missing by sticking with traditional banks.
These remarks came after panel moderator Claressa Monteiro, BT’s head of audio, asked about the perspective of a business that has yet to adopt digital banking.
“We don’t know what we are missing out until we explore and find out,” Tan said. He noted that traditional banks have long been the default choice for businesses, leaving some SMEs unfamiliar with what digital banks can offer.
Sharing that he learnt about such differences in services only after engaging with MariBank, Tan said that businesses could be paying more than necessary in banking fees simply because they have not explored the alternatives.
Reducing costs
Tiger Wang, consulting director for SME business solutions at MariBank Singapore, said on the panel that newer banking solutions could help SMEs reduce costs that they traditionally have had little bargaining power to negotiate.
“We try to make it a little better with the technology, make the approval a little faster so whenever the customers need it, they can get access to it faster,” he said.
Banks typically charge account fees, impose minimum-balance requirements and levy transaction fees, he noted. Foreign exchange mark-ups on overseas remittances can also add to costs, sometimes without businesses being fully aware of them.
Some banks charge about half a dollar per transaction after a monthly free quota is used up, while foreign exchange mark-ups can range from 20 to 40 basis points, Wang said.
He added that some newer banks, including MariBank, do not charge account fees regardless of account balances or foreign-exchange fees on overseas remittances. These features potentially help SMEs reduce hidden banking costs.
Teo of Inspire-Tech noted that SMEs often lack the transaction volumes needed to negotiate favourable rates with banks and suppliers. This leaves them with little choice but to accept the terms they are offered.
For the home-grown software company, where manpower is one of its largest expenses, banking charges can appear relatively minor but still add up.
“When I look at the last few lines of my accounting book, I see that my banking charges are actually quite huge,” Teo said, adding that even modest savings could make a difference to an SME’s bottom line.
Beyond fees, Wang said digital banks can use technology to streamline lending processes and shorten the time required for SMEs to obtain financing.
At MariBank, tools are used to digitise the reading of bank statements and other submitted documents, automatically generating information for credit assessors and cutting the time needed for credit assessments, he said.
For SMEs facing urgent working-capital needs, MariBank also offers a revolving credit facility under which interest is incurred only when funds are drawn down.
“In every process or every product we build, we always think about where we can make it better, what technology we can use to simplify this part of the process, and what additional data we can use to help with underwriting so we can better position (ourselves),” said Wang.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.






