

Are you well covered by health insurance?
It is essential that you manage your personal and company insurance plans and employee medical benefits
IF YOU are an employee, chances are your company provides some form of group health insurance as part of your benefits package. This is a valuable perk that offers basic protection, often at no extra cost.
But don’t be lulled into complacency. It is prudent to check if the company’s hospitalisation plan and benefits are portable, that is, you can bring them with you even if you stop working or change employers.
It is important to have a personal hospitalisation and surgical plan so that we are assured of cover even if we switch jobs and leave the workforce one day. As it is, both our present and past companies do not offer portable health plans.
So if you own personal health insurance policies, you might wonder if there is any overlap with your company insurance. And more importantly, how can you optimise both plans and ensure you are fully protected?
Some firms no longer provide group hospitalisation plans. Instead, they offer a specific cash amount per year as part of employee flexi-benefits, which the staff can use to fund their personal insurance plans or riders.
Nevertheless, with some planning, personal and company insurance can work hand in hand to provide comprehensive and cost-effective protection.
Understanding what companies provide
Most employers offer a base level of company insurance to all staff. This includes hospitalisation and surgical coverage for inpatient stays and day surgery, as well as outpatient medical benefits. Some organisations go further, covering specialist consultations, dental services, and alternative treatments such as traditional Chinese medicine, chiropractic care or physiotherapy sessions.
Basic life insurance is also commonly offered to employees with the specific coverage amounts usually determined by seniority. This typically provides a lump sum payout to your family in the event of death and may sometimes include critical illness coverage for major conditions, such as cancer or heart attack, during your employment.
The insurance premiums for these policies are typically paid for by the employer. Some companies may also offer the option to buy supplementary coverage at group rates, which can be a cost-effective way to enhance protection while you remain in the company.
However, most company insurance is not portable. This means coverage ends when you leave the organisation – whether due to a job change, a career break, retrenchment, or retirement.
Understanding the required level of cover
Before reviewing your company insurance, it’s helpful to understand how much protection you should ideally have.
Death and total permanent disability: A useful benchmark is coverage worth nine times your annual income, as recommended in the MAS Basic Financial Planning Guide. This ensures your dependents can maintain their lifestyle and settle major financial obligations.
Critical illness: Aim for around four times your annual income. This helps to offset lost income during recovery and cover out-of-pocket treatment costs.
Hospitalisation: Your ideal level depends on the type of ward and hospital you prefer – whether it’s a private hospital or a government hospital (with A, B1, or B2/C class wards).
Reviewing your company insurance coverage
Once you’ve assessed your needs, take a closer look at what your company insurance provides.
Request the latest policy summary from your HR department and review it carefully. Check the types of insurance included, coverage amounts, and pre-existing condition coverage. Be aware of any exclusions, sub-limits, and waiting periods.
For example, some plans exclude maternity benefits, while others may impose waiting periods for certain conditions. Knowing these details upfront helps avoid unpleasant surprises when making claims. Furthermore, confirm whether dependants are covered, and take note of caps and panel requirements for outpatient or alternative therapies.
Compare the scope of your company insurance with your personal insurance. Some corporate plans are broad, while others are more basic. Understanding these differences is key to spotting gaps or overlaps.
Optimising your company insurance and personal insurance
Here are four considerations.
1. Identify gaps and overlaps: Your personal insurance plays a crucial role in ensuring long-term protection, especially after you leave your employer. For core areas such as hospitalisation, life and critical illness, make sure your personal insurance provides sufficient coverage. Your company insurance can then act as additional support while you are employed.
2. Maintain strong base of personal insurance coverage: Personal insurance allows you to maintain your preferred standard of medical care and insurance coverage consistently, regardless of job changes. Company insurance alone cannot guarantee this continuity.
3. Customise coverage: If your employer allows you to customise your company insurance, select options that reduce duplication. For instance, if you already have a strong personal hospital plan with co-insurance features, you may opt for a company plan tier that focuses on covering out-of-pocket costs rather than duplicating inpatient benefits.
4. Be strategic with claims: Should you be hospitalised, which insurance plan should you claim from first? There are a few avenues.
You can ask the hospital to obtain a letter of guarantee (LOG) from your company’s health insurer. At the same time, the hospital can e-file the invoices to your personal insurer and MediSave. By doing so, the hospital will automatically send the final itemised tax invoice to the company’s insurer to work out how much you can claim. Do note that for company hospital plans, the LOG is typically capped at S$10,000.
Another way is to claim from your personal insurance first and then seek reimbursement for the expenses that are not covered by your insurer, from your employer’s or your other insurer’s hospital plan if you are eligible. Your company’s insurer can also reimburse your personal plan, although it may not be a full reimbursement depending on the company plan’s coverage and the claim amount.
Doing so helps to preserve the annual benefit limits of your personal plan for any future claimable expenses. And the premiums can be kept affordable for all in the long run.
Lorna’s example
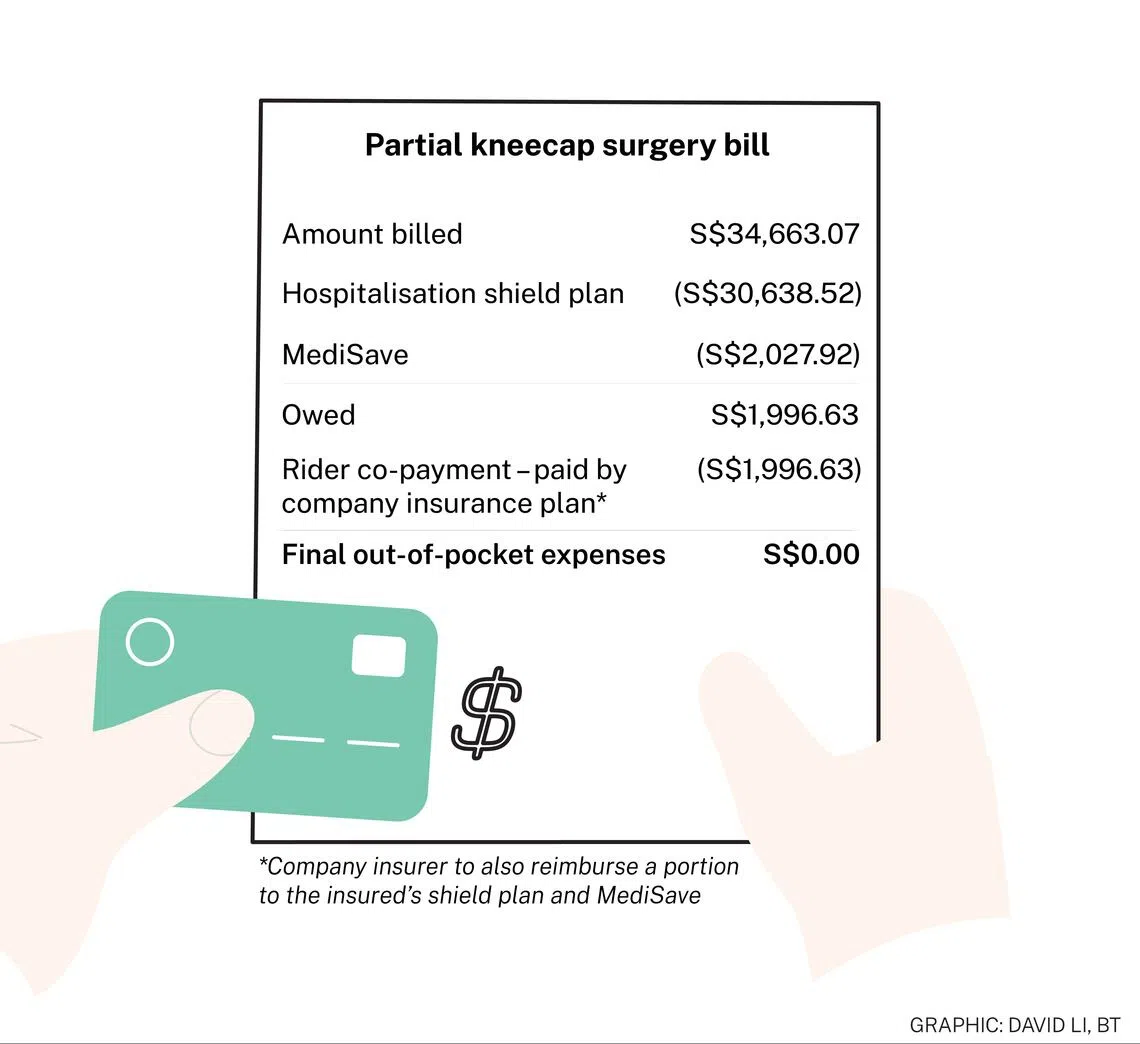
This May, I underwent a partial kneecap replacement surgery at National University Hospital (NUH). The surgery bill amounted to S$34,663.07 of which S$32,635.15 was payable by my hospitalisation shield plan, and S$2,027.92 came from my MediSave. Of the $32,635.15, I had to fork out a rider co-payment amount of S$1,996.63 in cash.
In my case, I got NUH to e-file to my insurer as I have a comprehensive shield plan. I then applied for reimbursement from my company’s health insurer for my out-of-pocket expenses of $1,996.63. The company’s insurer also worked out how much it can reimburse to my personal insurer and my MediSave. By doing so, I would enjoy zero out-of-pocket expenses.
A smarter way to protect yourself
Company insurance provides valuable protection while you are employed, but it shouldn’t be your only safety net. Personal insurance ensures that coverage continues seamlessly, no matter where life takes you.
A good practice is to review both sets of insurance at least once a year, ideally when your company renews its benefits package for employees. Coverage terms can change, and this provides an opportunity to ensure your company insurance and personal insurance remain well-aligned.
By understanding what your employer provides and your coverage needs, and by using your personal insurance strategically, you can build a robust, efficient protection plan that supports you at every stage of life.
Lorna Tan is head of financial planning literacy at DBS Bank, and author of bestsellers Money Smart and Retire Smart. Shawn Lee is a financial literacy specialist at DBS Bank.






