Buying term insurance is not so that you can ‘invest the rest’
Term insurance is simply the most affordable and suitable way to adequately and immediately insure yourself.
TWO months ago, I wrote a column revisiting the age-old debate on term vs whole life insurance. The conclusion was that in most situations, term insurance is the most suitable. As expected, not everyone agreed with that position. The crux of their objections was that when you buy term insurance instead of whole life plans, there is no cash value. So, let’s look at five of the common objections associated with having no saving component to an insurance policy
“You are wasting your money because you get nothing back”
For every premium dollar you pay for your whole life plans, a portion goes into paying the cost of insurance and the rest of it is invested into the insurer’s life fund. The cost of insurance portion is never returned to you. The only reason why you get money back from a whole life plan after a period of time is because you gave the insurers extra money to invest in their life fund. But when you buy a term plan, you are effectively paying only the cost of insurance, and that is why you get no money back at the end of the term. So while the claim that there is no cash value is true, it is only a half-truth.
“You are not saving towards your retirement”
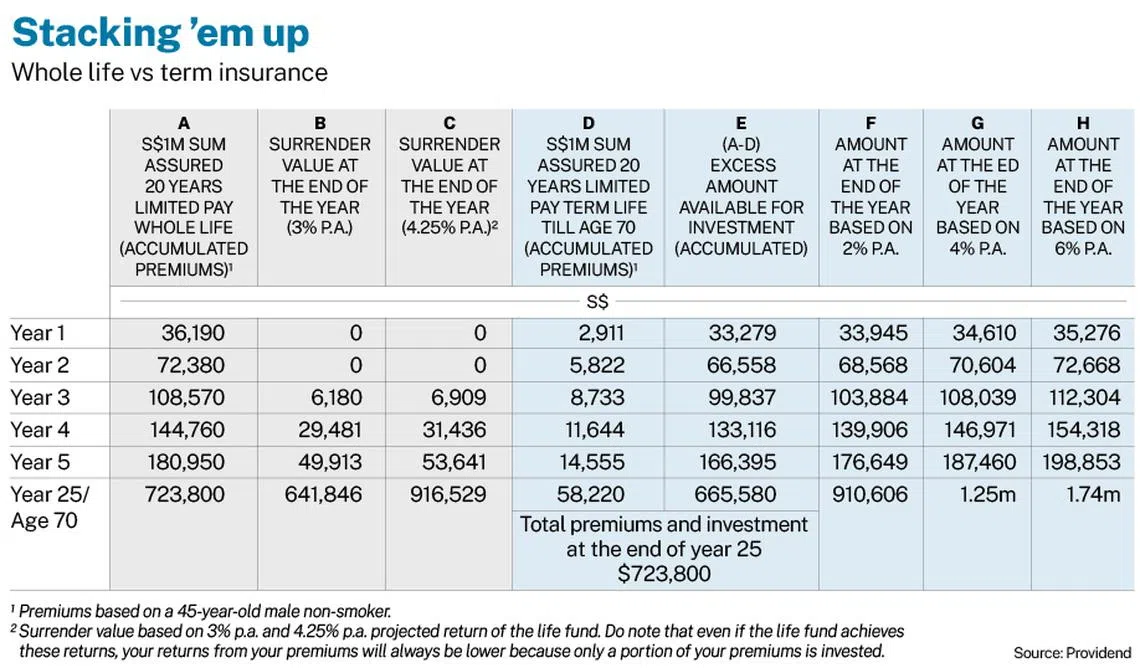
With term insurance, because you are buying only pure insurance with no extra money given to the insurers to invest for you, you are not saving towards your retirement, so the argument goes. But from column B and C of the accompanying table, you will see that even after 25 years, your whole life policy has barely broken even from the total amount of premiums paid. Yes, you might have accumulated a sum of money, but with nil or almost no returns. Instead, if you simply buy a term plan and invest the amount saved from buying a whole life plan (column E), even at 2 per cent p.a. (F), you would have done better.
In addition, there is flexibility when you “buy term and invest the rest”, in at least two ways. One, if a better and lower premium term plan comes along in the future, or for some reason you no longer need the insurance coverage, you have the option to change or terminate your term plan without affecting your savings. Two, if you need money in the short term, you can sell some of the investments you have made separately, without affecting your term protection.
“Your policy will lapse if you forget or cannot afford to pay premiums”
The argument is that this would not happen in the case of whole life plans because under the non-forfeiture clauses of whole life plans, you can service the premiums of your policy by using the accumulated cash values. But the question is, are you willing to pay S$33,279 a year more just to solve this problem? There are more cost-effective ways to mitigate this risk. Firstly, you can set up a direct debit arrangement or standing instruction with your bank to automatically pay your premiums. Even if your account has no money, you still have a 30-day grace period. If you have a good agent, he would be informed of your non-payment and should remind you to do so. On the issue of affordability, I think you have a higher chance of not being able to afford the expensive premiums of whole life, than the cheaper premiums of term plans. And if you really cannot afford the premiums due to, say, a temporary loss of job, you can always dig into any personal accumulated savings and investments. So I find this objection to be the most absurd.
“Not everyone knows how to buy term and invest the rest”
This is true. But if the person who wants to sell you a whole life plan claims to be a competent financial adviser, surely, he should also be competent enough to advise you on investing. If he is not competent or unwilling, you might want to find another adviser. But getting just 2 per cent a year is not that difficult. I believe this objection is an excuse rather than a valid reason for not recommending term plans.
“A term plan does not mitigate inflation”
This is because a term plan does not have cash value and even after 20 years, the death benefit remains the initial sum assured. But since the premiums of term insurance are more than 10 times cheaper than whole life plans, this is easily solved by insuring yourself slightly more than you need at the onset. Again, an invalid objection.
But buying term insurance is not so that you can “invest the rest”. You buy term insurance simply because it is the most affordable and suitable way to adequately and immediately insure yourself. How many people are able and willing to pay premiums of S$36,190 a year? Even if you were willing, the cash outlay would eat into your surplus, and you would have less resources to live on and to save towards future goals
But with a term plan, you can pay for coverage only till age 70 (because you do not need life coverage for most situations), and you only need to pay S$2,911 a year. So the irony of buying whole life plans for the dual purpose of protection and savings is that you achieve neither. The premiums for whole life plans are so expensive that you are unlikely to be able to afford sufficient coverage, and the returns from the policy is insufficient to fund your goals. You are better off separating protection from savings and investment.
The writer is CEO of Providend, Singapore’s first and probably sole fee-only comprehensive wealth advisory firm. He can be contacted at chris_tan@providend.com