

Investing in nuclear energy, a quiet backbone for the AI-powered economy
Governments are rediscovering that net zero needs dependable baseloads, not just intermittent generation
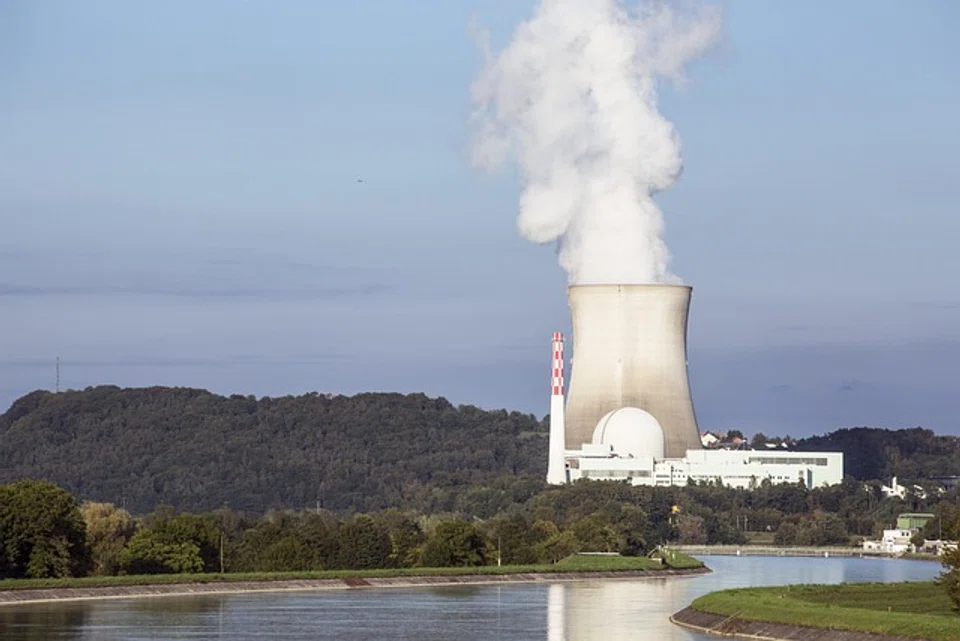
AFTER many years of studying the markets, I’ve observed that the most abiding equity stories are not those that frequent the headlines, but companies of vital importance working behind the scenes – the quiet plumbing that lets everything else scale.
Two in particular are hiding in plain sight: accelerating artificial intelligence (AI) adoption is a demand shock for electricity; and nuclear energy is a proven, low-carbon supply that can meet it at scale.
Beyond the historical headlines of fear and fallout, nuclear’s narrative is changing as policy has caught up with physics. Governments are rediscovering that net zero needs dependable baseloads, not just intermittent generation. The shift is now visible in signatures, not slogans.
Thirty-one nations have pledged to triple nuclear output by 2050; the EU has included nuclear in its sustainability taxonomy; the US Inflation Reduction Act has issued tax credits for advanced reactor manufacturing; and around 65 reactors are under construction across 15 countries. That policy floor extends to uranium, a primary fuel for nuclear reactors, where demand is projected to rise 28 per cent by 2030 and 98 per cent by 2040.
Investors know “return on investment” (ROI) as the return per dollar of capital over time. A similar concept, energy return on investment (EROI), applies to power generation, measuring energy output versus energy input across its life cycle. For instance, producing a barrel of oil consumes energy for extraction, transport and refining, but remains viable because the energy gained far exceeds what’s spent.
By this metric, nuclear power vastly outperforms fossil fuels. On engineering and economic grounds alone, it deserves far greater attention in energy transition debates. Just as coal and oil powered the industrial revolutions that shaped modern society, a nuclear renaissance, with its superior EROI, could unlock transformative productivity gains. Energy revolutions precipitate industrial revolutions.
Opportunities from fuel to fission
For investors looking to gain exposure to the theme, physical uranium remains the cleanest expression. Since end-2019, prices have surged by around 162 per cent, eclipsing the performance of energy-related commodities such as oil and natural gas, as well as precious metals such as gold and silver. Uranium’s over-the-counter market structure makes it less volatile than uranium equities, and access vehicles exist via uranium futures, exchange-traded funds and listed holders of physical inventory.
Then there are uranium miners, which sit at the very top of the supply chain of equity plays. Their specialisations span exploration, development and production. As is typical with commodity miners, those in exploration and development are higher beta plays due to the larger execution risks of the projects, while producers have generally more predictable cash flows based on underlying commodity prices and margins.
Nonetheless, uranium miners would clearly be beneficiaries under a nuclear energy revolution. Notably, miner performance has been no slouch against the backdrop of the strong equity bull markets of 2023 to 2024.
Utility companies which have considerable nuclear power generation share of electricity production offer another route for exposure. But the utilities sector remains sensitive to external factors such as interest rates and general electrical consumption demand, both tied to economic conditions. Policy risk also looms, with the Trump administration seeking to roll back parts of the Inflation Reduction Act, potentially removing tax credits that have supported renewables under former US president Joe Biden.
Even so, nuclear power enjoys bipartisan backing and is likely to retain incentives, shielding it from major cuts. Independent power producers, in particular, have shown resilience in 2024, supported by strong AI-driven demand as data centres and tech giants pursue nuclear-powered supply agreements.
In a fractured geopolitical world rebuilding coverage and contemplating strategic energy stockpiles, small modular reactors (SMRs) emerge as an interesting proposition. With SMRs, locations previously deemed unsuitable for larger nuclear power plants are now potential sites, and at a lower startup cost.
In addition, they are designed for scalability, rapid deployment, safety and cost-efficiency, but have wider dispersions in energy production capacity (up to 300 megawatt per unit) to cater for different commercial or industrial use-cases.
While the investable set is still thin – Rolls-Royce has a proprietary SMR design in development, and NuScale is the only publicly listed pure-play with a Nuclear Regulatory Commission-approved design but it remains pre-profit as it invests in research and development – the private pipeline is swelling and should broaden public-market access over time.
Powering AI’s growing demand
Where the themes of nuclear energy and AI converge is where the alpha lies: underwriting the contracted kilowatt. The International Energy Agency (IEA) projects that electricity demand from data centres will more than double by 2030 to roughly 945 terawatt-hour (TWh), a load comparable to Japan today, with AI-optimised data centres the principal driver. Even before then, IEA opined that consumption from data centres, AI and crypto could double by 2026.
Driven by digitalisation, AI, electric vehicles (EVs), manufacturing reshoring, defence needs and climate change, the ever-expanding demand is now bringing nuclear energy into sharp focus.
Perhaps the most conspicuous demand for nuclear energy comes from defence technology and operations. From powering sophisticated digital information networks, military bases, transport and battlefield systems, the US Department of Defence (DoD) consumes about 30 TWh of electricity annually on top of about 10 million gallons of fuel daily.
In recognition of the insurmountable power consumption, DoD embarked on the development of 1-5MW nuclear microreactors under Project Pele, with the goal of generating continuous power remotely in an easily scalable and capex-efficient manner.
The risks in nuclear bets
In nuclear, we’re wary of enrichment bottlenecks and geopolitics, policy reversals, and the permanent temptation to confuse promise with pipeline. In the realm of AI, we remain cognisant of capex cyclicality and policy intervention on power allocation. But the macro signals are aligned: Policy is clearing the runway for nuclear deployment; data-centre demand is outpacing incremental efficiency; and the demand for stable, clean power is rising.
Put simply, the scarce input to the AI economy is shifting from chips to kilowatts, and the hedge for that scarcity lies within the nuclear value chain, from the elemental atoms of uranium itself to the innovative producers behind next-generation nuclear reactors.
The winners in the next decade will either secure long-dated, clean megawatts or sell the equipment that makes those megawatts usable at scale – and nuclear will be the quiet backbone of that system.
The writer is senior investment strategist, DBS Bank.
TRENDING NOW

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures

Things to know about DBS’ incoming chairman Anthony Lim

Wealthy Indonesians snap up government bonds as yields near 8%: OCBC
From local AI partnerships to global opportunities: How MNCs help Singapore firms scale

