

A ‘portfolio life’ as the answer to the longevity challenge
Human capital can generate long-tail dividends far beyond the technical retirement age
[SINGAPORE] This year, around 1,500 Singapore residents are 100 years old or older, up from 1,200 in 2015, and just 700 in 2010.
What is the probability that we will live to 100? In 2018, UBS Global Watch, a survey of high-net-worth (HNW) individuals, found that more than half believed they would live to 100.
I am also convinced that I will become a centenarian. While my father passed relatively young in his late 60s, my mother is now 92, albeit frail.
It is hardly a coincidence that multiple longevity services have sprung up to cater to Singaporeans’ desire to remain in good health for as long as they can.
Running parallel is an evolving definition of retirement. Discussions around “portfolio careers”, or even broader, “portfolio lives” as reflected in a new survey of HNW individuals by Manulife and FT Longitude, are germane to the challenge of longevity.
With the prospect of decades in retirement, how should we marshal our talents and resources – not just financial – to go the distance and live fulfilling lives?
A portfolio approach to work is shaping up as a key enabler, taking a vastly different perspective on career and retirement.
Careers are traditionally regarded as a linear progression: employment lasting three to four decades, and then a hard stop at retirement.
Increasingly, however, some eschew the path of long-term employment, either by choice or because of the structure of the market. Instead, they pursue a portfolio of work and pursuits that may or may not pay an income.
As for retirement, even that is unsettled, and for good reasons.
Manulife and FT Longitude’s study, The New Fluidity, is based on a survey of 1,000 HNW individuals in the Asia-Pacific and Middle East, between the ages of 18 and more than 80, and with net worth ranging from US$3 million to over US$50 million.
HNW individuals, said the study, are routinely planning for lifespans that extend to 100. Greater wealth, in addition to longevity, is reshaping approaches to retirement.
Retirement, the study found, is being redefined as a period of “extended productivity”.
“Most are embracing ‘portfolio lives’ by dividing their time and income across multiple roles and ventures. This approach demands multi-phase wealth management instead of linear retirement planning,” said the study.
A second finding is that “adaptability is seen as the new accumulation”. Nearly two-thirds of respondents said that “adaptability and optionality are more important to long-term financial security than wealth accumulation alone”.
The study also noted: “This is encouraging a shift towards so-called wealth fluidity, where portfolios are built around changing scenarios, liquidity and resilience rather than just returns.”
What does it take to build a portfolio life? For those keen to transition, how much of a hurdle is age? How do you approach the management of your wealth to afford you the cushion and flexibility needed for a long, meaningful life?
Value of human capital
The first step is to realise the value of your personal human capital, which has both tangible and intangible aspects.
Human capital behaves like a bond. In one’s youth and well into middle age, it generates an income. A 2005 paper by academics Roger Ibbotson, Peng Chen and associates posited a portfolio asset allocation taking into account human capital and insurance.
Broadly, the approach is intuitive. Young adults start with more human than financial capital. Hence, as they pursue careers, younger people should invest more in higher-risk assets such as stocks.
Human capital declines as one nears retirement, however. By then, financial capital should have grown substantially to a level that is able to sustain living expenses, with perhaps even excess funds for legacy purposes. Insurance helps to hedge the risk of premature death.
But in a portfolio life, your talents and abilities are nurtured far more dynamically than a single employment affords. This raises the intriguing possibility that your human capital could generate long-tail dividends – financial and non-financial – far beyond the technical retirement age.
The book, The 100-Year Life: Living and Working in an Age of Longevity by academics Lynda Gratton and Andrew Scott, was published in 2016. Even then, it envisioned a portfolio life.
I first read the book in 2019. Two principles continue to stand out.
First, in order to sustain a long life, we should banish the notion of a life in three stages: education in the first 20-odd years; then a long career; and then retirement which could last 30 years or longer.
Instead, think of life as malleable and fluid. Education can take place now and again in midlife, and work can also be pursued in retirement.
Second, treat your personal and intangible attributes as assets, and develop them as assiduously as you would your financial assets.
There are three types of personal assets. Productive assets include your skills, knowledge and professional capital or network and reputation.
Second is “vitality” assets, or your physical and mental health. Third is “transformational” assets, such as self-knowledge and openness to new experiences.
These personal assets compound over time and pay dividends in spades, particularly in retirement.
In fact, as Gratton and Scott write, older people and senior executives who have built a “well established foundation” of skills and personal networks are well-placed to embark on a portfolio life.
They could devote two or three days a week for paid work, leaving ample time for other pursuits.
Holistic advice versus silos
How, then, should one approach the management of personal wealth?
Whether one pursues a portfolio life earlier or later, longevity means we need to build up ample financial resources to last decades, with an eye on inflation and future medical expenses.
The key principles of investing early and regularly in a diversified portfolio and keeping costs low do not change.
But it is important to plan for the phase when regular employment ceases, even if you successfully parlay your talents and network to earn an income at the pace you choose.
The Singapore edition of JP Morgan Asset Management’s guide to retirement suggests a bucket approach: cash and equivalents for short-term spending needs, and higher allocations to equities and alternative assets for needs that have a longer horizon, such as legacy.
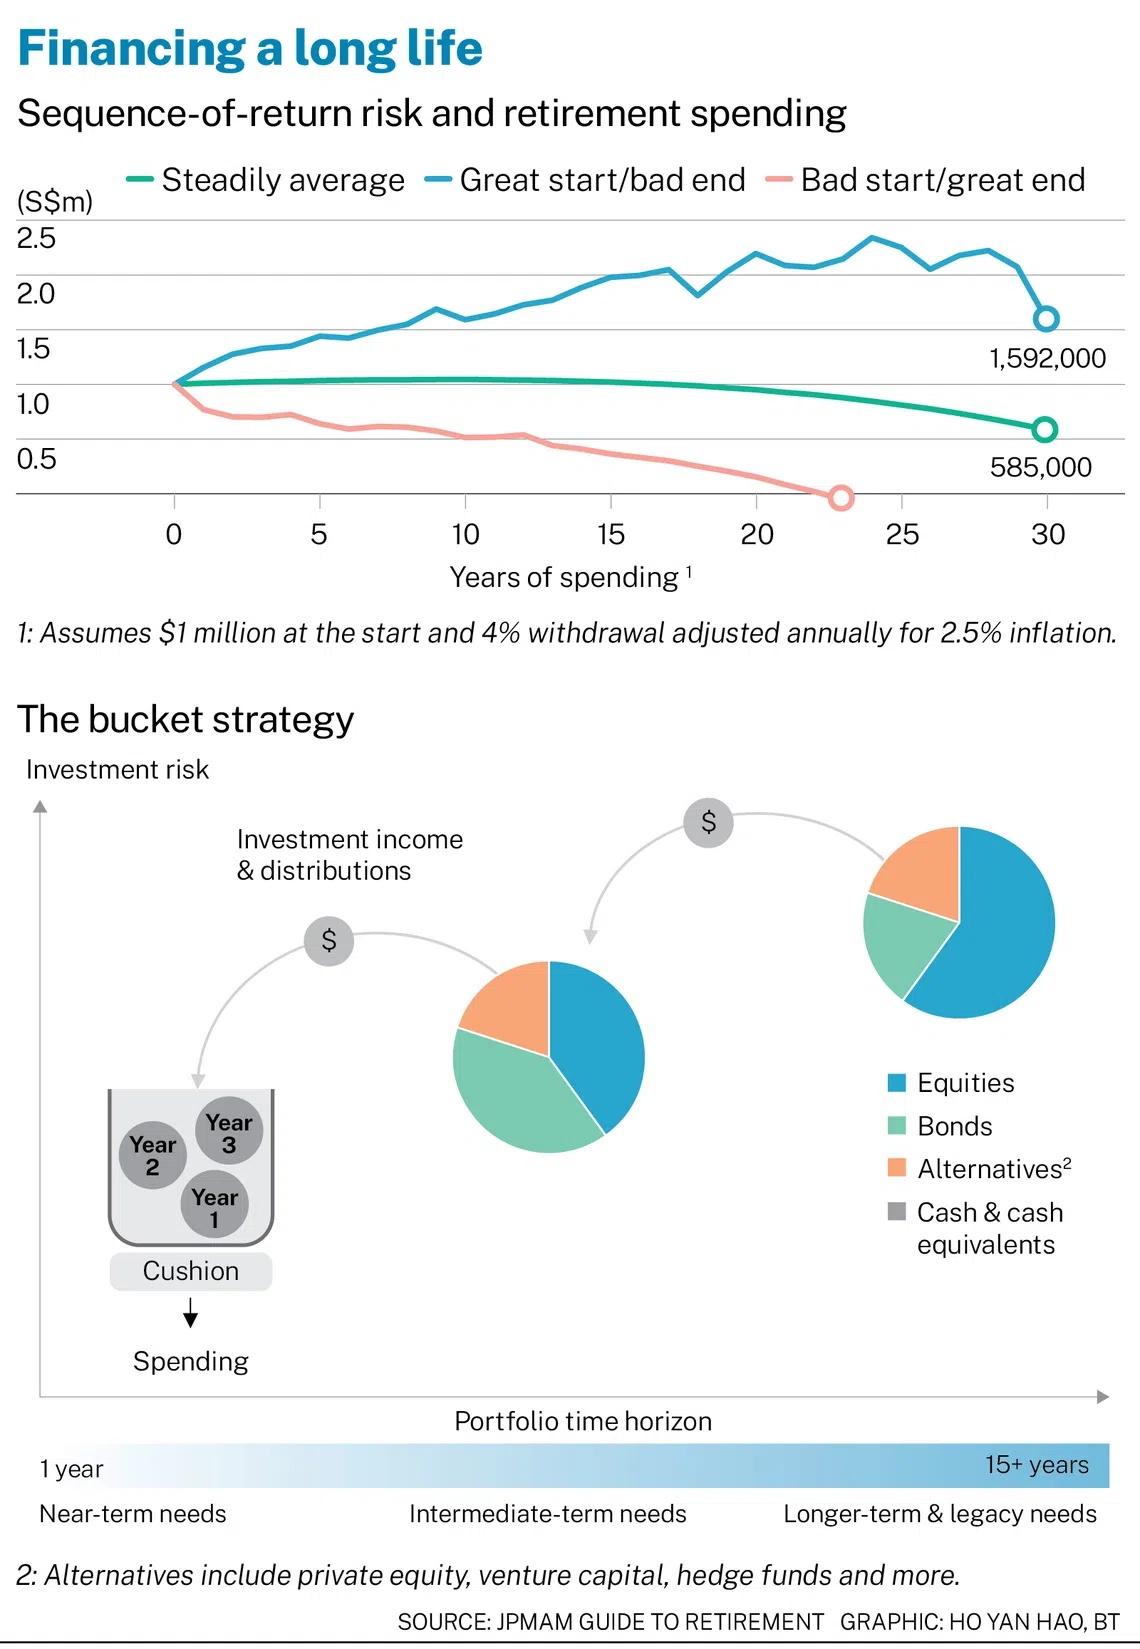
As you reach the phase when you will need to draw on your portfolio for expenses, it would be sensible to begin to dial down the higher-risk exposures to mitigate the sequence-of-returns risk.
This is the risk that a sharp downturn at the start of the withdrawal phase could significantly affect a portfolio’s capital.
Manulife’s survey indicates a gap, however.
Only 17 per cent of respondents have an integrated plan covering investment, tax, succession, legal and family governance. Instead, service providers tend to work in “silos”, which can give rise to “blind spots and conflicting strategies”. This is something to be mindful of.
Ultimately, a holistic wealth plan enables the pursuit of a portfolio life which can be richly rewarding. If your skills and talents can still earn an income in your senior years, that is icing on the cake.
TRENDING NOW
‘Not trying to solve world hunger’: GoTo takes pragmatic approach to AI

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Malaysian developer Eco World tops bids for Sin Ming area housing plot with S$1,612 psf ppr bid

Singapore’s new data centres must use renewables. Can they overcome the hurdles?

