

Analysts split on Venture’s outlook, even as share price hits one-week high
DBS and RHB upbeat on improving order momentum, CGSI flags valuation risks from weaker US economic outlook
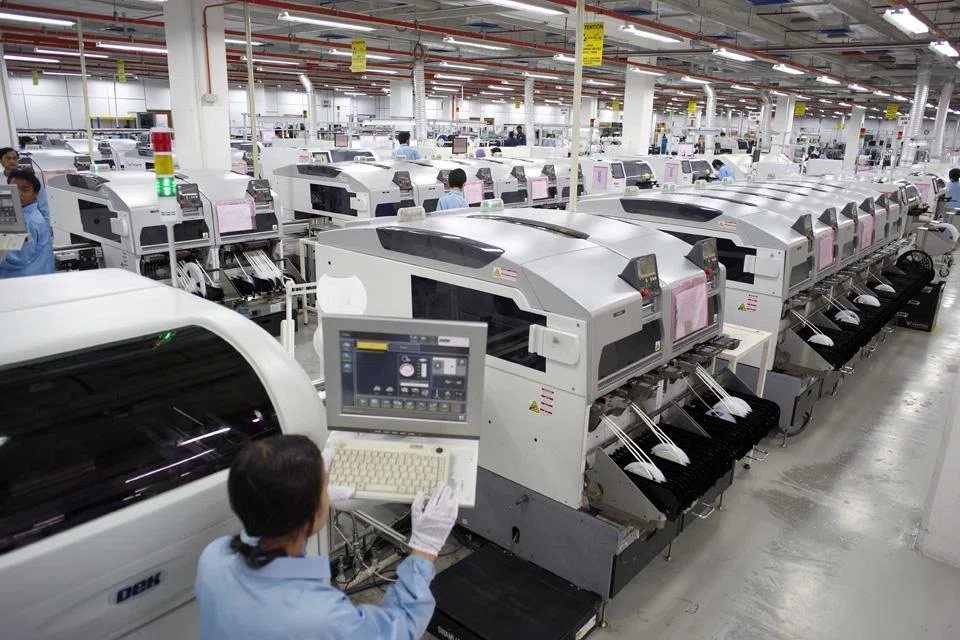
[SINGAPORE] Analysts remain divided on the outlook for Venture , even as its shares rebounded on Wednesday (Nov 11) to hit a one-week high, tracking a broader recovery in technology stocks.
As at the midday trading break on Wednesday, the counter was up 6.5 per cent at S$15.49, its highest level this week.
Its gains follow that of other technology counters the day before, with AEM , UMS Integration and CSE Global among the counters to recover after last week’s sell-off.
The Singapore Exchange had attributed the weakness to concerns over artificial intelligence spending, regulation and investment returns that weighed on semiconductor, technology hardware, software and telecommunications stocks.
Venture had also reported a stronger third-quarter performance on Nov 6. Its net profit for the three months ended Sep 30 rose 21.9 per cent year-on-year to S$67.8 million, amid higher revenue contributions from its key technology business.
Revenue for the period, meanwhile, rose 26 per cent to S$790.4 million. The gains were boosted by a ramp-up in production, as well as market share gains in its test and measurement instrumentation, networking and communications, and semiconductor-related equipment businesses.

Analysts remain upbeat
At least two brokerages remained optimistic on the outlook for Venture.
RHB raised its target price for the counter to S$21.97 from S$20.78 in a note on Tuesday, even as it maintained its “buy” recommendation.
Its analyst, Alfie Yeo, raised his FY2026, FY2027 and FY2028 earnings forecasts by 2 per cent, 3 per cent and 5 per cent respectively, following stronger-than-expected customer order momentum in the third quarter.
He expects this momentum to sustain growth in the subsequent quarters.
While near-term net margins could remain under pressure, RHB expects improvement over the longer term, as the firm benefits from its differentiated solutions and R&D.
Similarly, DBS analyst Lee Keng Ling said Venture offered investors “an attractive value proposition” following the recent tech-sector sell-off, even as the brokerage maintained its target price of S$22.90.
In a note on Nov 10, she cited the counter’s improving earnings momentum, a strong net-cash balance sheet and a “compelling” dividend yield of around 5 per cent as reasons for her optimism.
She noted that the company’s net margin eased from 8.8 per cent in the first half of 2026 to about 8.6 per cent in Q3, partly reflecting higher component procurement costs amid supply shortages.
Ling added that the company’s recovery was supported by sustained customer demand, new product introductions and market share gains in its technology portfolio.
Beyond semiconductor equipment, DBS also estimates opportunities for Venture in AI data-centre networking and photonics.
The shift towards faster optical network connections – from 800 gigabits per second to 1.6 terabits per second (Tbps) and eventually 3.2 Tbps – is driving demand for higher-bandwidth, energy-efficient optical solutions, she added.
Life sciences is also showing signs of recovery, with longer-term opportunities in genomics, precision medicine, healthy longevity and advanced scientific instrumentation. Overall, Ling expects FY2026 to mark a return to growth for Venture after three years of contraction.
CGS International (CGSI), however, took a more cautious view on the valuation outlook, cutting its target price for Venture to S$18.10 from S$18.94, while maintaining its “add” recommendation.
Analyst William Tng said component shortages and higher component prices could weigh on gross margins by 0.7 to 0.8 percentage points, offsetting the benefit of higher revenue forecasts.
He also expects concerns over the US economic outlook and a potentially higher interest-rate environment to continue weighing on valuations.
Nevertheless, the brokerage raised its FY2026 to FY2028 revenue forecasts for Venture by 7.2 to 9.3 per cent, while raising its FY2026 earnings per share (EPS) forecast by 4 per cent, citing an improved demand recovery.
It highlighted potential rerating catalysts, including new product launches by customers and more revenue opportunities as companies diversify their production from China to Malaysia.
However, it flagged several downside risks, including supply chain disruptions and a weaker global economic outlook reducing customer orders.
Venture last closed at S$14.55 on Tuesday, up 1.8 per cent.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Singapore commits S$143 million to fund R&D for industrial decarbonisation
Sheng Siong has fallen from its highs. Can its defensive appeal endure?
DBS, OCBC or UOB? Investors urged to be selective as Q3 reveals widening performance gap
Nvidia, CEO Jensen Huang sued over disclosures related to suspected Chinese spy

