

China emerges as source of cheap global funding as Beijing lets more yuan flow offshore
Shift echoes Japan decades ago, when rock-bottom yields and a glut of domestic savings sent capital pouring overseas
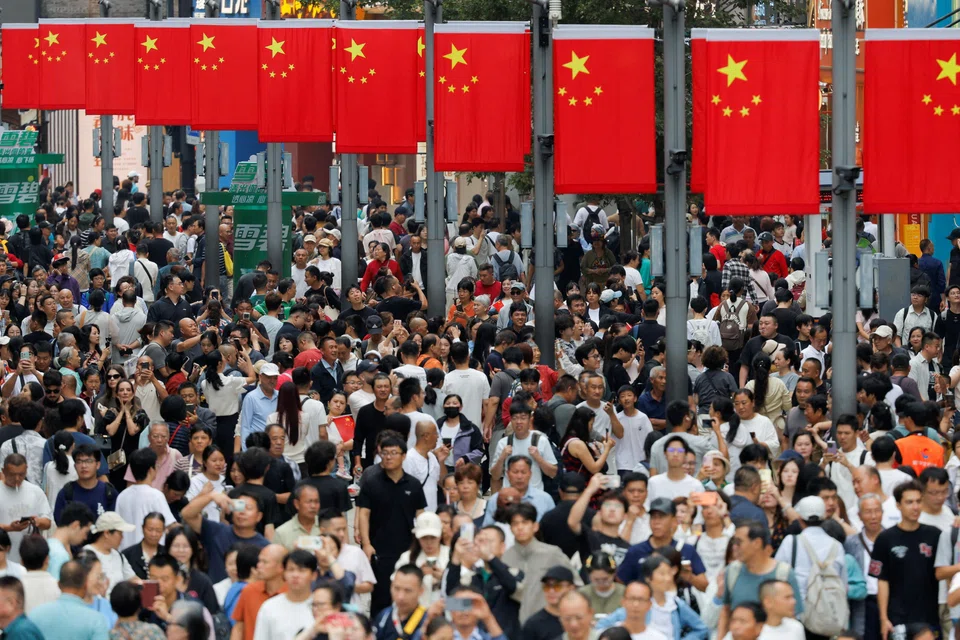
CHINA is letting a wave of cheap money flow across its borders, turning the country into a rare source of low-cost funding for foreign borrowers.
Regulators have approved the proceeds from more than 40 per cent of panda bonds sold so far in 2026 to be taken offshore, the highest share on record, according to data compiled by Bloomberg. That amounts to as much as 130 billion yuan (US$19 billion), also an all-time high. Panda bonds are yuan-denominated bonds issued in mainland China by overseas borrowers.
The shift echoes Japan decades ago, when rock-bottom yields and a glut of domestic savings sent capital pouring overseas – though China’s flows remain a tiny fraction of that. Subdued inflation and a weak economy have pushed rates lower as borrowing costs rise elsewhere, while Beijing is also loosening its grip on cross-border flows as it seeks a bigger global role for the yuan.
“Panda issuers are simply finding borrowing costs in the onshore renminbi market increasingly competitive versus those elsewhere,” said Dariusz Kowalczyk, head of cross-asset strategy for Asia at Banco Bilbao Vizcaya Argentaria. Beijing has also eased restrictions on taking the proceeds offshore as part of its push to boost the renminbi’s international use, he added.
The gap in borrowing costs is wide. China’s 10-year government bond yield stood at 1.68 per cent as of Thursday (Oct 8), compared with 5.23 per cent for US Treasuries and 3.09 per cent for Japanese government bonds of the same maturity.
New players
A few years ago, the panda bond market was dominated by the offshore entities of Chinese companies and foreign carmakers funding their China operations. Now the market has gone global, drawing Belt and Road partners including Hungary, Slovenia, Kazakhstan, Pakistan and Indonesia, as well as lenders such as Deutsche Bank, Morgan Stanley and Credit Agricole.
Foreign issuers raised 115.5 billion yuan through Oct 8, twice as much as in all of 2025, according to data compiled by Bloomberg. They now make up 47 per cent of the market, up from 13 per cent three years ago.
More are on the way. Australia’s Fortescue is weighing a 3 billion yuan debut, while Brazilian iron ore giant Vale is considering a similar move. UBS Group raised 2 billion yuan at just 1.78 per cent in August, the lowest coupon on record for a five-year panda bond from a foreign financial institution.
Demand is growing offshore as well. Sales of dim sum bonds – yuan-denominated debt issued outside mainland China – have already surpassed 2025’s record, reaching 1 trillion yuan, while non-Chinese issuers’ share has risen to 35 per cent from 23 per cent, data compiled by Bloomberg show.
It’s not just bonds. Chinese banks are also extending cheaper yuan credit across borders, competing more aggressively with global lenders. State-owned financial institutions from Kazakhstan and Uzbekistan are currently in talks to raise fresh yuan-denominated loans, according to people familiar with the matter, who asked not to be identified discussing private matters.
Beijing’s approval
None of this happens without Beijing’s approval. Regulators announced rules in late 2022 allowing panda bond issuers to convert their proceeds into foreign currencies, whether for use in China or abroad.
Part of the motive is Beijing’s effort to internationalise the renminbi. A deeper yuan financing market gives foreign borrowers another source of funding while encouraging more trade, investment and financing in the Chinese currency, helping reduce China’s reliance on the US dollar-based financial system.
Another reason is China’s persistent trade surplus. The country earns more from exports than it spends on imports, resulting in a large pool of domestic savings that needs somewhere to go. Panda bonds provide an outlet, allowing Chinese investors to lend to foreign companies and governments in yuan.
“Panda bonds are meant to recycle China’s current account surpluses,” said Timothy Tan, a Bloomberg Intelligence strategist. The market is still small, but Tan expects it to grow as China pushes for more trade to be settled in renminbi. That would boost demand for yuan reserves and leave companies with more of the currency to invest, he added.
A strong currency makes that easier to allow. The yuan’s more than 6 per cent gain against the US dollar over the past year has eased fears of capital flight that previously made regulators wary of letting money leave the country. But it also raises repayment costs for borrowers who swap yuan proceeds into foreign currencies. Hedging that risk costs about 3 per cent, eroding much of the saving.
Borrowers using yuan for Chinese trade can avoid that cost. The currency settled 29 per cent of China’s goods trade in the first half, up one percentage point from a year earlier.
“If you are genuinely raising yuan to settle yuan-denominated trade, you could save the hedging cost,” said Samuel Tse, senior economist at DBS Group Holdings. “You raise yuan, you use yuan, and suddenly that extra cost stays in your pocket.”
Japan
Japan offers a glimpse of where cheap currency funding can lead. Tokyo opened its financial markets and promoted wider use of the yen in the 1980s. Years of ultra-low interest rates later turned the yen into a major source of cheap global funding. China is taking a more controlled route, promoting wider yuan use while keeping restrictions on capital flows and managing the exchange rate.
With China’s borrowing costs well below those in the US, the appeal could persist. And as its trade ties deepen, more borrowers will have a natural use for the yuan.
“This could gradually strengthen China’s role from a major trading nation that mainly operates within a dollar-centered system into a provider of global funding, settlement and investment alternatives,” said Li Wei, head of multi-asset investments at BNP Paribas Securities (China). BLOOMBERG
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

Prima to move out of historic Keppel Road flour mill building in 2028
Temasek-related Azalea, SeaTown, Seviora Capital to merge in 2027
Family offices see more tailored products, leverage ‘collective firepower’ for direct deal access
Singapore room rates soar, but hotels seeing mixed demand from F1 race and events

