

Chairman’s role in spotlight with raft of proposed new rules for Singapore boards
New guardrails are put forward for board independence, director accountability and capital management disclosure
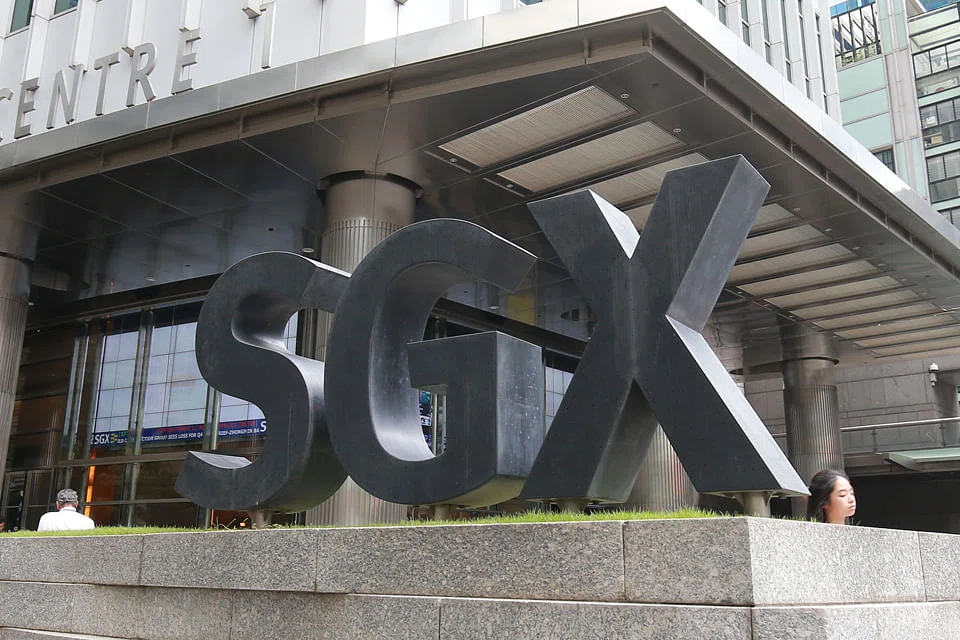
[SINGAPORE] The role and influence of a board chairman is coming under scrutiny in Singapore, with plans for new rules on board independence casting a spotlight on companies led by a chairman who is not independent.
Singapore-listed companies will face stricter requirements on board leadership, firstly with a proposed rule requiring companies whose chairman is not independent to appoint a lead independent director, as regulators seek to strengthen board oversight and accountability.
Companies will also have to ensure that their key board committees are led by independent chairmen and staffed by a majority of independent directors, if the proposals are passed.
In addition, directors will be limited to a cap of five directorships, in a move aimed at ensuring board quality and effectiveness.
The rule changes concerning chairmen, in particular, could cause significant ripples through Singapore’s corporate landscape.
In 2025, 70 listed entities, or 11.4 per cent of the total of 615 entities, did not appoint a lead independent director despite having a non-independent chairman.
In 2024, 25 directors held more than five SGX-listed board seats, and 49 companies or 8.1 per cent of 604 companies had directors with more than five Singapore Exchange (SGX)-listed board seats.
The proposals are part of a broad review put forward on Tuesday (Oct 27) by the Corporate Governance Advisory Committee (CGAC) and Singapore Exchange Regulation (SGX RegCo).
The measures aim to strengthen corporate governance, support long-term value creation and sustain investor confidence. They complement initiatives from the Equities Market Review Group to strengthen Singapore’s equities market.
Tan Boon Gin, CEO of SGX RegCo, said: “The proposed amendments to our rules would add structure to how boards think about leadership and accountability, thus fostering a culture of strong board governance.”
Under Singapore’s regulatory framework, compliance with the SGX Listing Rules is mandatory, while the Code of Corporate Governance follows a comply-or-explain approach.
Best practice dictates that the chairman and CEO roles be distinct, and that the chairman should be independent.
A chairman is considered not independent if he has ties to the company’s executive management, substantial shareholders or commercial dealings, is related by family to the CEO or key executives, or has served on the board for an extended tenure.
The CGAC observed in its review that some jurisdictions build in strong expectations of independent board leadership. Under the UK and Australian corporate governance codes, the chairman is expected to be independent.
Where this is not the case, companies are expected to provide for additional independent leadership arrangements, including through a senior or lead independent director.
The CGAC said it has decided against proposing a mandatory independent chairman for all listed companies, citing Singapore’s market landscape.
Instead, it is proposing that an existing Corporate Governance Code provision – on appointing a lead independent director where the chairman is not independent – be solidified into the SGX Listing Rules.
Where the chairman is also the CEO, a new code provision would require companies to explain how the chairman’s responsibilities are effectively fulfilled and disclose the safeguards in place.
These could include separating the responsibilities of the roles and excluding the chairman from decisions concerning his or her performance or remuneration.
The changes governing board independence extend to key committees. Under the proposed changes, the audit, nominating and remuneration committees of listed companies would each be required to be chaired by an independent director and comprise at least a majority of independent directors.
The code separately recommends that all nominating committee members be non-executive directors, while the audit and remuneration committees are recommended to comprise only non-executive directors.
Five-directorship cap
The CGAC is also proposing a limit of five directorships in listed entities for each director at any one time, including the company in which the individual serves as a director.
The proposed count would include directorships in companies listed on SGX or overseas exchanges, as well as directorships on the boards of managers of listed real estate investment trusts or business trusts.
Proposed changes to SGX Listing Rules
1. Multiple listed directorships will be capped to a maximum of five.
- Issuers will be required not to appoint or reappoint a director who, upon appointment or reappointment, would hold more than five directorships across all issuers listed on SGX or any other overseas securities exchange;
- Directors are expected to ensure at all times that they do not exceed this limit; and
- If a cap on multiple directorships is supported under the Corporate Governance Code but not the listing rules, the requirement will operate on a comply-or-explain basis.
2. Where the board chairman is not independent, the company must appoint a lead independent director.
3. Key board committees must have an independent chairman and a majority of independent directors. This will apply to the company’s audit committee, nominating committee and remuneration committee.
4. More explicit disclosure of the selection criteria, rationale, board diversity considerations and the search and nomination process for each director appointee. It must also be stated whether the nominating committee supports a proposed appointment or re-appointment; where it is not, reasons are to be provided.
5. Issuers are to state in their annual reports whether directors underwent professional development activities relevant to their board roles during the financial year, and provide a description of those activities.
6. Issuers are to maintain a capital management policy, of which dividend policy forms a part, and to describe that capital management policy in the annual report. Issuers are required to explain any deviation from their capital management policy, just as they are required to explain deviation of their recommended or declared dividend from the dividend policy.
However, the committee is seeking views on whether the cap should be introduced as a mandatory Listing Rule or through a comply-or-explain provision in the code.
The CGAC said directors’ existing responsibilities require them to devote sufficient time and attention to their roles, with nominating committees expected to consider their other board appointments and principal commitments when assessing their capacity.
To ensure board quality, the proposals also require companies to provide more explicit disclosures on the selection criteria, rationale, board diversity considerations and nomination process for each appointment. Companies would be expected to state whether the nominating committee supports a proposed appointment or reappointment, and explain its reasons if it does not.
Companies would also have to state in their annual reports whether directors undertook professional development activities relevant to their board roles during the financial year and describe those activities.
Stronger focus on capital management
The CGAC further proposed that listed companies maintain and disclose a capital management policy beyond existing dividend policy disclosures. This could cover capital allocation priorities, shareholder returns, capital structure and balance sheet management.
SGX RegCo introduced a new rule in September, requiring issuers to maintain a dividend policy and describe it in their annual reports for financial years commencing on or after Jan 1, 2027.
A broader capital management policy would put dividend decisions in the context of a company’s other uses of capital, including reinvestment in the business, acquisitions, debt reduction and maintaining financial flexibility. The aim is to give investors a clearer understanding of how companies prioritise competing uses of capital.
It is also seeking views on whether this should be a code provision operating on a comply-or-explain basis or a mandatory Listing Rule.
The CGAC’s review, which began in 2025, is part of broader efforts to strengthen Singapore’s capital markets. In developing its recommendations, the committee said it had gathered feedback from directors, CEOs and chief financial officers of listed companies, as well as retail and institutional investors.
Discussions highlighted the need for clearer guidance on implementing the code, improvements in board quality and more meaningful engagement with investors on companies’ long-term plans.
Other proposed changes by the CGAC include:
- Risk disclosures: Introducing a code provision requiring companies to disclose the board’s assessment of principal and emerging risks, and how these are managed or mitigated. The Practice Guidance would be enhanced to cover risk identification and disclosure, including emerging risks related to artificial intelligence and sustainability.
- Long-term value creation: Reflecting the board’s responsibility for setting strategic direction and overseeing long-term value creation.
- Investor engagement: Emphasising proactive and regular engagement with investors on companies’ strategies and plans, and encouraging companies to provide the investment community with timely and accessible assessments of their performance, financial position and prospects.
- Strengthening corporate disclosures: Introducing a new code provision requiring companies to publish up-to-date financial and corporate governance information on their websites.
Together, these proposals seek to give investors better insight into the risks companies face and how boards oversee them, while improving access to information on companies’ strategies, performance and prospects.
The consultation is open for feedback until Jan 27, 2027.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Director of PR firm sacked for secretly recording internal meeting loses wrongful dismissal claim

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status

If Europe goes to war, the fallout will be felt in East Asia

China’s market is tougher than ever. Where can Singapore firms still find room to grow?

