

SGX enhances disclosure rules to build a ‘value creation culture’ among issuers
SGX RegCo CEO says the rule changes ‘strengthen disclosure standards while preserving flexibility for issuers’
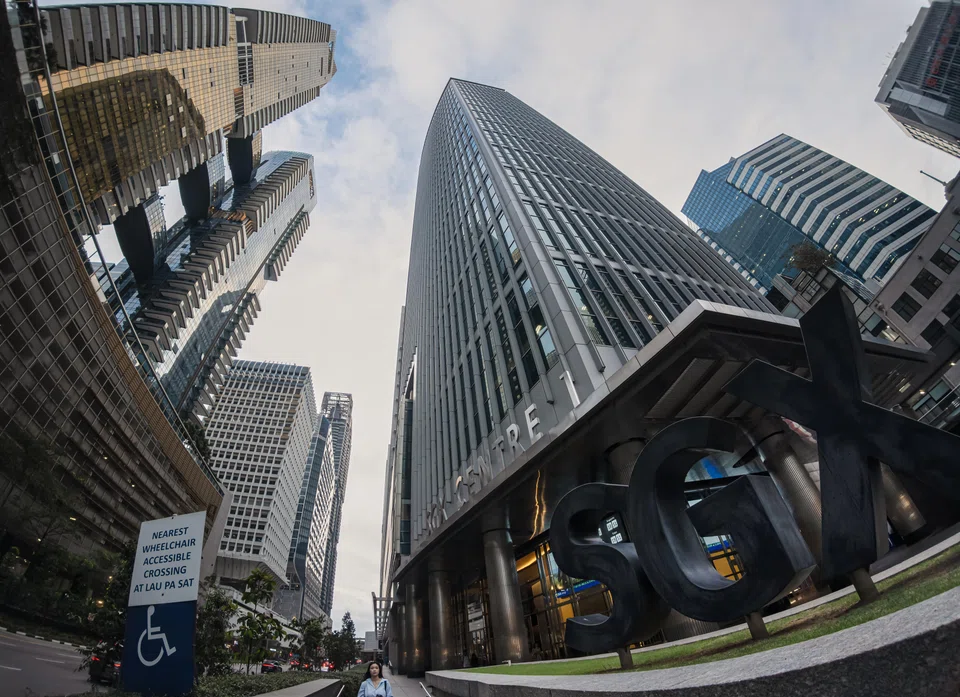
[SINGAPORE] Listed companies will be required to give investors a clearer view of how they pay top executives, manage dividends and engage shareholders under new disclosure rules taking effect from Jan 1, 2027.
Singapore Exchange Regulation (SGX RegCo) announced on Wednesday (Sep 23) that it is updating its listing rules to require enhanced disclosures on remuneration, dividend policies and investor relations. The changes are meant to “foster a value creation culture among listed issuers”, said the market regulator.
Most Singapore issuers have baseline standards in place, in line with the Code of Corporate Governance, but the new rules target specific communication gaps and are aimed at elevating disclosure quality.
Tan Boon Gin, CEO at SGX RegCo, said the rule changes “strengthen disclosure standards while preserving flexibility for issuers”.
“We encourage issuers to look beyond the minimum requirements, and to provide substantive and meaningful disclosures, such that they can attract global capital and improve valuations,” he added.
Under the rules, an issuer will be required to:
- Describe in its annual reports the key financial and non-financial performance indicators used to determine the remuneration of its executive directors and executive officers, as well as how these indicators are aligned with long-term value creation objectives.
- Include in its annual reports a dividend policy, an investor relations policy, and a description of key shareholder engagement activities within the year.
- Maintain a website for investor engagement, or a dedicated investor engagement section within the issuer’s website, and publish the investor relations policy there. Issuers are also encouraged to publish other information including annual reports, minutes of annual general meetings, investor presentation decks and a calendar of upcoming events.
The changes follow a public consultation the market regulator launched in April this year, aimed at raising baseline standards for transparency and sharpening issuers’ focus on value creation.
In that consultation, SGX RegCo also sought views on whether disclosure of broader capital management practices beyond just dividend policy would be useful to investors, and if so, what aspects should be covered.
The consultation closed in May with input from 32 respondents, including asset managers, service providers, representative bodies, issuers, and market professionals from Corporate Monitor, the GDInstitute, the Institute of Singapore Chartered Accountants, and the Singapore Institute of Directors (SID).
“More disclosure is not necessarily better disclosure”
SID said on Wednesday that it welcomes SGX RegCo’s emphasis that the new requirements should raise the quality of disclosure rather than become a box-ticking exercise.
In its consultation response earlier this year, SID flagged the risk that companies could technically comply with disclosure rules without providing information genuinely useful to investors. It also called for guidance on what meaningful, company-specific disclosure looks like, including for remuneration and dividend policies.
SGX RegCo noted that several respondents had suggested expanding disclosures beyond dividends to cover a wider range of capital management practices. The regulator noted that this feedback will be shared with the Corporate Governance Advisory Committee for consideration on whether such disclosures should be recommended and, if so, whether these should be part of the corporate governance code or the listing rules.
Emily Poon, CEO at SID, told The Business Times that transparency around capital allocation can be valuable, but “more disclosure is not necessarily better disclosure”.
“A broader framework could be useful for larger issuers, but requirements should remain proportionate to the size and circumstances of the company,” she said.
SGX RegCo previously said the intent is not to mandate that companies pay dividends, but to ensure they are transparent about their approach.
These new rules complement SGX’s “Value Unlock” programme by ensuring that capability-building results in long-term improvements to corporate practices.
Under the programme, issuers can apply for financial grants to build capabilities in corporate strategy, capital management and investor relations. In return, grant recipients are expected to step up their corporate practices and disclosures.
“Singapore’s equity market is benefiting from a resurgence of investor interest, but this interest will not last if boards and management do not increase investor engagement and demonstrate greater transparency – particularly transparency about how board or management decisions align with shareholder interests,” said Tan.
Under SGX Regco’s new rules, while annual reports must contain a dividend policy, issuers are not required to commit to a payout. But if they wish to retain capital for growth, for instance, they may say so in their policy.
The investor relations policy, meanwhile, should set out investor engagement channels and the mechanisms by which shareholders can contact the issuer.
While SGXNet remains the primary channel for information dissemination, the company’s website or section for investor engagement will provide an additional touchpoint.
Poon called the website a useful baseline, but not engagement in itself.
“Its value will depend on whether companies use it to provide clear, useful information and make it easier for shareholders to engage meaningfully,” she said.
Based on FY2025 annual reports published up to May 31, 2026, more than 90 per cent of issuers already maintain a website for investor engagement and have established two-way communication channels with investors.
Eight in 10 disclose the objectives and principles of their investor relations policies, though only a minority detail their shareholder engagement activities. Similarly, more than 90 per cent of issuers incorporate financial indicators into their remuneration frameworks, but only 47 per cent disclose which indicators they use.
SGX RegCo said these figures point to room for improvement but also suggest the new rules are within reach for most issuers.
The first batch of annual reports required to comply with the new rules will be issued in 2028, though SGX RegCo is encouraging early adoption. Issuers are also being directed to updated Practice Notes for guidance on the substance of disclosures.
However, David Gerald, founder and chief executive officer of the Securities Investors Association (Singapore), or Sias, said the biggest risk is the new requirements becoming just another box-ticking exercise. A boilerplate dividend policy or a generic statement saying a company “regularly engages shareholders” will achieve very little, he added. The real test, he said, will therefore be whether boards embrace the spirit of the new rules, rather than merely complying with them.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Simba admits exceeding spectrum limits amid failed M1 deal; parent company Tuas’ full-year profit surges 277%

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
What’s on the agenda when Xi and Trump meet in Washington

Ex-execs of CW Group, Allied Tech charged with offences linked to lawyer’s S$76 million misappropriation

