Citi drops target price on Laopu Gold to HK$400 as consumer spending faces pressure
It still has a 19% upside, with strong brand loyalty and high repurchase intent highlighted as positives
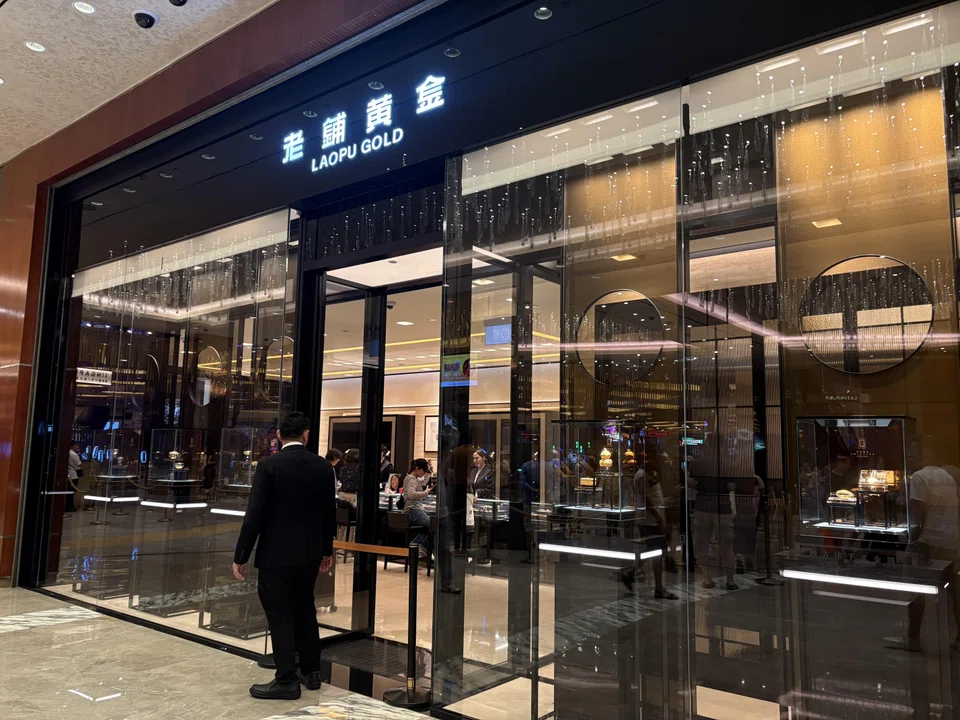
[SINGAPORE] Various Citi analysts have cut their target price on Laopu Gold to HK$400 from HK$507 – while keeping a “buy” rating on the stock – amid changes in consumer sentiment.
This comes as the product price was lowered, noted their Oct 9 report, when spot gold prices also dipped in late-September to US$4,110 levels.
Consumers are hence more likely to wait for better price offerings if they expect gold prices to continue trending downwards, and especially with product discounts, said the analysts.
Therefore, Laopu Gold sales in Q3 are expected to improve “slightly” compared with soft July performance, though operating leverage improvement is “unlikely to be strong enough” to offset gross profit margin contraction after reducing prices.
Revenue is estimated to increase 9 per cent quarter on quarter in Q3 to 3.6 billion yuan (US$537.9 million), but net profit is expected to decline 12 per cent to 589 million yuan.
However, the Citi analysts added that the new pricing strategy could prove to be “a double-edged sword”.
“The more attractive discount is likely to have helped expand the customer base from a small cohort of price-insensitive purchasers to avoid being constrained by customer saturation in the short term.”
The lower target price of HK$400 still has a 19 per cent upside, said Citi.
Strong brand loyalty and high repurchase intent were positives highlighted by the analysts, amid volatile short-term results – though wider spot gold price fluctuations may influence the timing of that recovery.
SEE ALSO
Gold prices have slipped from record-highs earlier this year, after the US Federal Reserve hiked interest rates in September and the US dollar strengthened.
Analysts from State Street Investment Management said bullion markets remain resilient and have absorbed policy and rates volatility in “relative stride”.
“Consumer gold imports in China hit a record 1,141 tonnes in the first eight months of this year, eclipsing seasonal demand comparisons in 2018, 2023 and 2024 despite significantly higher prices,” they wrote in an October report.
Therefore, the analysts maintained their base case gold price forecast of US$4,750 to US$5,500 per troy ounce by the end of Q1 2027 – but reduced the odds from 70 per cent to 60 per cent given the current macro headwinds.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.