Daiwa House Logistics Trust proposes to divest DPL Sendai Port, buy Hiroshima facility
The acquisition consideration for DPL Hiroshima Itsukaichi Port stands at some 8.2 billion yen

[SINGAPORE] The manager of Daiwa House Logistics Trust announced on Friday (Oct 30) its proposal to divest DPL Sendai Port and use part of the proceeds to acquire DPL Hiroshima Itsukaichi Port.
In an evening bourse filing, the manager wrote that the divestment consideration for DPL Sendai Port amounts to 13.5 billion yen (US$85.8 million), representing a premium of 2.7 per cent above the average of two independent valuations of 13.15 billion yen, as at Sep 30.
The acquisition consideration for DPL Hiroshima Itsukaichi Port stands at some 8.2 billion yen, representing a discount of 16.7 per cent from an independent valuation of 9.9 billion yen, also as at Sep 30.
Why divest?
The trust is proposing to divest DPL Sendai Port to its sponsor, Daiwa House Industry, which was said to have made the only offer when the manager conducted an exercise to determine market interest in the property.
Located in Japan’s Miyagi prefecture, DPL Sendai had an occupancy of 31.9 per cent as at Sep 30, down from 100 per cent as at Dec 31, 2024, said the manager.
Occupancy declined further to 23.9 per cent in October.
The property had a weighted average lease expiry by gross rental income of 2.7 years as at Sep 30, and recorded a net property income of 246 million yen in FY2025, down from some 554 million yen in FY2024.
To improve its marketability through asset enhancement initiatives, large capital expenditures would be required, with an extended downtime and minimal contribution expected from the property, added the manager.
For these reasons, divestment was considered.

Why acquire?
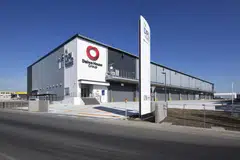
Meanwhile, DPL Hiroshima Itsukaichi Port in Hiroshima is a high-quality modern asset occupied by blue-chip tenants that could enhance the trust’s portfolio quality, said the manager.
As at Sep 30, the property was fully occupied by two large third-party logistics companies. On a pro forma basis, this would improve the trust’s overall portfolio occupancy to 96.9 per cent from 88.5 per cent.
The property had a weighted average lease expiry by gross rental income of 2.3 years, as at Sep 30. It recorded a net property income of 471.2 million yen in FY2025.
The manager noted that it is a freehold logistics facility built with modern specifications, with a ramp for vehicles to get to the second floor, which would enhance cargo handling efficiency and offer flexibility in floor operations.
The property also has solar panels installed on its rooftop, with an aggregate capacity of 1.7 megawatts peak.
DPL Hiroshima Itsukaichi Port is described to be strategically located in a well-developed port industrial district, which makes it suitable for round-the-clock operations, said the manager.
It noted that the supply of large multi-tenanted logistics facilities is tight in the Hiroshima market, with the market-wide vacancy rate having been at 0 per cent since the fourth quarter ended Dec 31, 2023.
Being some 10 km away from the centre of Hiroshima makes the area suitable to serve consumption centres. It also offers proximity to a pool of labour, which is an important factor for tenants, added the manager.
Other benefits
The proposed transactions are expected to boost the trust’s net property income for FY2025 by 4 per cent, and that for the first half of FY2026 by 7.9 per cent.
Accordingly, the distribution per unit of the Reit is estimated to improve by 5.5 per cent for FY2025 and by 11 per cent for H1 FY2026.
After the transactions, aggregate leverage as at Jun 30, 2026 is expected to improve from 40.1 per cent to 38.3 per cent on a pro forma basis.
Said the manager’s chief executive Jun Yamamura: “The proposed transactions are expected to be distribution-per-unit accretive, and will also strengthen the balance sheet while providing (the trust) with financing flexibility to pursue further growth in future.”
The counter ended Friday at S$0.41, up 1.2 per cent or S$0.005, before the announcement.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.