

DBS remains analysts’ pick ahead of Q3 earnings after Singapore banks’ share slump
Still, the lending environment remains ‘favourable’; calls on OCBC and UOB are mixed
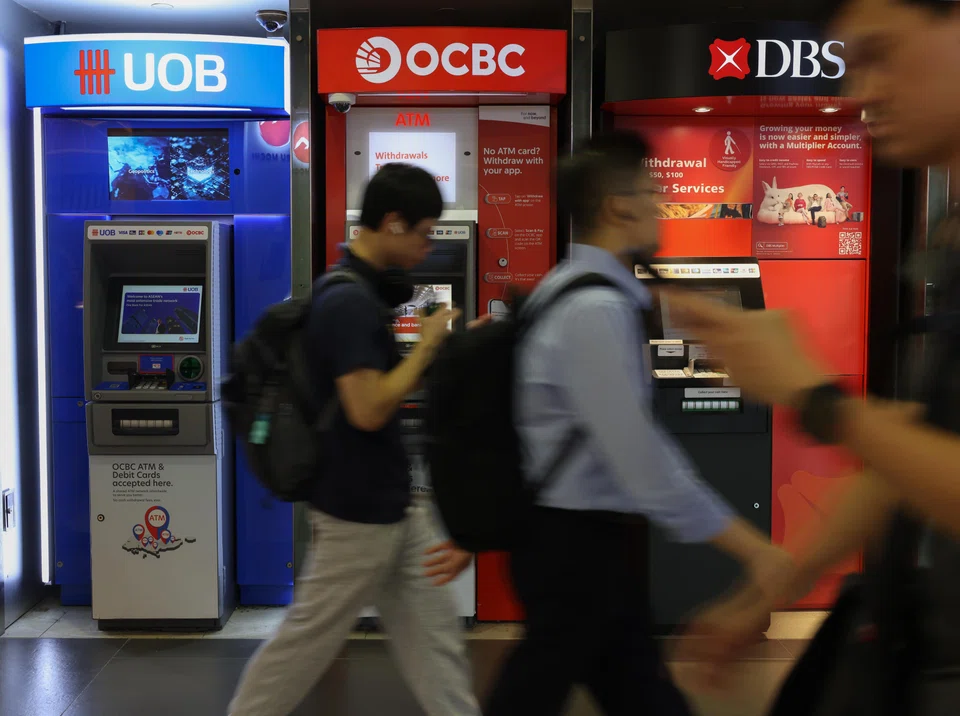
[SINGAPORE] Analysts remain upbeat on DBS , even after a sell-off in the trio of local banks led to more than US$22 billion in market value being shed last week alone.
The slump began on Oct 7, after Citi downgraded its call on OCBC from “hold” to “sell” and reiterated a “sell” rating on UOB .
DBS shares closed at S$74.11 on Friday (Oct 16), up 0.5 per cent on the day. OCBC ended the day almost flat at S$29. UOB, meanwhile, fell 0.2 per cent to close at S$41.61.
Analysts have flagged that the lenders’ third-quarter earnings might miss market forecasts and that higher interest rates could squeeze margins. Their debt holdings are also coming under pressure from rising bond yields.
Still, there is an upside for the banks as the lending environment remains “favourable”, said Jayden Vantarakis, head of Asean equity research at Macquarie Group, pointing to statistics from the Monetary Authority of Singapore that showed loan growth was up 16 per cent year on year in August.
“We assume flat quarter-on-quarter net interest margins (NIMs) for the banks in Q3, slightly below what our interest rate model predicts, due to lagged fixed rate loan repricing,” he added.
Maybank Securities analysts Thilan Wickramasinghe and Amirul Rusydy said that earnings should be supported by record loans and how asset yields typically price up during a rate hike.
“Hence, we believe risks are low for guidance downgrades… (and remain) positive on the sector for long-term investors,” they wrote in a Wednesday report.
UOB will report its Q3 earnings on Nov 4; DBS on Nov 5; and OCBC on Nov 6.
DBS still favoured
CGS International (CGSI) analysts Tay Wee Kuang and Tan Jie Hui on Monday upgraded their call on DBS to “add” from “hold”. They also raised their target prices on the counter to S$79.50 from S$77.10.
“We believe DBS recorded 2.9 per cent year-on-year growth in non-interest income for Q3, underpinned by 7.4 per cent growth on the year in wealth-management fees due to continued net new money inflow,” the analysts said.
DBS is also Maybank’s top technical pick, given its “most resilient” uptrend among the trio of lenders since the latest correction.
Citi has a “buy” rating on DBS as well, with a target price of S$86.80. Analyst Tan Yong Hong described the bank as an “Asia wealth proxy” in a Wednesday report, adding that it benefits from deposit inflows.
CGSI’s Tay and Tan, however, flagged that DBS’ NII is “unlikely to see a turnaround” in Q3, with an expected 2.4 per cent fall year on year and 2.5 per cent decline quarter on quarter. This would be on the back of the bank’s NIM narrowing 10 basis points year on year and one basis point quarter on quarter.
This comes as “DBS continues to replace fixed-rate assets such as mortgages that were still repriced lower compared with interest rates from 2024 to 2025”, the analysts added.
Nevertheless, they noted that DBS “likely recorded loans growth of 1.5 per cent quarter on quarter in Q3, which will partially mitigate the impact of continued NIM compression”.
Macquarie’s Vantarakis added that he expects DBS to “meet expectations” this quarter as the only bank paying dividends in Q3 – estimated at a 4.4 per cent annualised yield.
He has an “outperform” rating on the stock with a target price of S$79.84.
Varied views on UOB, OCBC
Views on UOB, meanwhile, are mixed. Vantarakis noted that the counter trades at a 30 per cent price-to-earnings discount, adding that this “could be partially closed from an in-line or better result”.
He has an “outperform” rating on UOB with a target price of S$45.29, making it his top pick among the local banks.
Citi’s Tan, however, has a “sell” rating and S$38 target price on the counter.
He expects a 9 per cent quarter-on-quarter decline in profit to S$1.35 billion for Q3. While the bank could have “better relative fees growth momentum”, he noted that this would be due to a “low-base effect”.
He added that UOB’s H1 2025 wealth fees growth is likely to come in behind those of its peers.
Some analysts are still optimistic on OCBC, even after the bank shed S$8 billion in value on Oct 7.
Maybank’s Wickramasinghe and Amirul have a “buy” call and S$37.23 target price on the counter.
It is their top pick due to its “whole-of-wealth” proposition to leverage OCBC, Bank of Singapore and Great Eastern to “deepen cross-selling”. This will likely unlock new revenue opportunities and drive a higher return-on-equity trajectory.
“Investments in relationship managers and wealth centres in Hong Kong should further expand the franchise,” they added.
CGSI’s Tay and Tan noted that OCBC benefited in Q2 from its insurance subsidiary Great Eastern’s contributions in Q2.
The unit’s new business embedded value (NBEV) growth came in at 25.2 per cent year on year; it also had 171.8 per cent year-on-year growth in profit from shareholders’ funds.
“We believe Great Eastern’s NBEV, which reflects its business momentum, saw robust Q3 FY2026 growth, resulting in our estimated 28.6 per cent year on year growth in OCBC’s life and general insurance income in Q3,” the analysts said.
“However,” they added, “we believe the rise in long-term yields in the US translated to MTM (mark-to-market) losses for fixed-income assets, mitigating any MTM gains from equities and resulting in muted non-customer flow-related trading and investment income of (about S$20 million in Q3 FY2026).”
Tay and Tan raised their target price to S$30.40 from S$29.80, but reiterated their “hold” call on the stock.
Citi’s Tan, meanwhile, has a “sell” rating on OCBC with a target price of S$27.50. He noted that growth prospects from the bank’s wealth proposition are already “well priced in”.
Vantarakis from Macquarie downgraded his call on OCBC to “neutral” on Tuesday, with a target price of S$30. The bank’s capital position, he said, is “tighter than peers, which could present forward risks to growth and dividends”.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

High Court rules against Julius Baer’s Singapore trust arm in US$50 million family trust dispute
MSCI proposes standalone status for Indonesia; Jakarta stocks plunge 8%

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
No chicken feed: How Malayan Flour Mills built an empire from flour to fowl

