

‘Herd mentality’ seen in private-market fund flows; Asia offers diversification: Lombard Odier
Surge in redemptions this year mirrors the earlier rush to ‘pile into’ the asset class
[SINGAPORE] A surge in redemption requests at evergreen private-credit funds this year reflects a “herd mentality” among wealth investors, rather than broad weakness in their underlying portfolios, said Daniel Matson, global head of private assets at Lombard Odier.
Several major funds hit quarterly redemption limits this year as investors sought to pull money from direct lending. Redemption requests have largely eased in the third quarter of 2026, even as they remain elevated.
In an interview with The Business Times, Matson said that individual investors have been “piling into” the asset class over the last few years, and the subsequent rush for exits mirrors similar behaviour.
“(We) have to distinguish clearly between fundraising... and (the underlying) portfolio,” noted Matson. “What (we) have seen, without a doubt, is a herd mentality on the fundraising side, where individual investors in the last five years have really gone in a lot.”
He attributed this partly to investors buying into the assets to “fill a hole” in their portfolios.
Recent years have also seen a “benign market environment”, leading to high leverage, optimism and heavy fundraising – conditions that could “lay the groundwork for trouble”, he explained.
Asia offers diversification
The underlying portfolios of private assets, however, have remained quite steady, observed Matson. “This is a story more about fundraising... than a portfolio story. I see some movements here and there, but I do not think there is necessarily a huge problem.”
Against this backdrop, diversification – both across sectors and geographies – has become increasingly important.
Asia can be particularly useful for geographic diversification, as its distinct regional markets display low correlation, said Matson. “Asia is really a collection of different markets, because India has really nothing to do with what is happening in China, Japan, South-east Asia and (South) Korea.”
Thus, investors should not see Asia as a single investment exposure, as the opportunities and risks vary across its markets.
Matson also stressed that illiquidity is a key feature of private assets rather than a weakness, as it takes time to realise their value, regardless of whether investors gain exposure through closed-end or evergreen funds.
The need for diversification has also been highlighted by this year’s weakness in software, sometimes dubbed the “SaaSpocalypse” due to the massive sell-off in software-as-a-service, or SaaS, stocks. Software accounts for about 20 to 30 per cent of US direct lending, according to analysts.
Matson added that such episodes ultimately come down to portfolio construction and risk management.
“I think we all have to understand that software is a big part of private assets. That is great, but you also have to have other things in the portfolio.”
Performance will ultimately come down to distinguishing between winners and losers as well as incumbents and challengers, across industries, he said.
A good company is not necessarily a good deal
The same selectivity applies to valuations. Matson noted that a good company does not automatically make a good investment, as high-quality assets can still be overvalued. “It is very important to distinguish between a good company and a good deal,” pointed out Matson, adding that a good company could be a bad purchase, depending on how much the investor paid for it. This would be especially pertinent if the price was elevated due to hype.
Artificial intelligence is an area where that distinction is significant. Even as AI is expected to fundamentally change society in the next decade, not “every single AI company... is going to do well”, he said. “So you have to be super, super selective.”
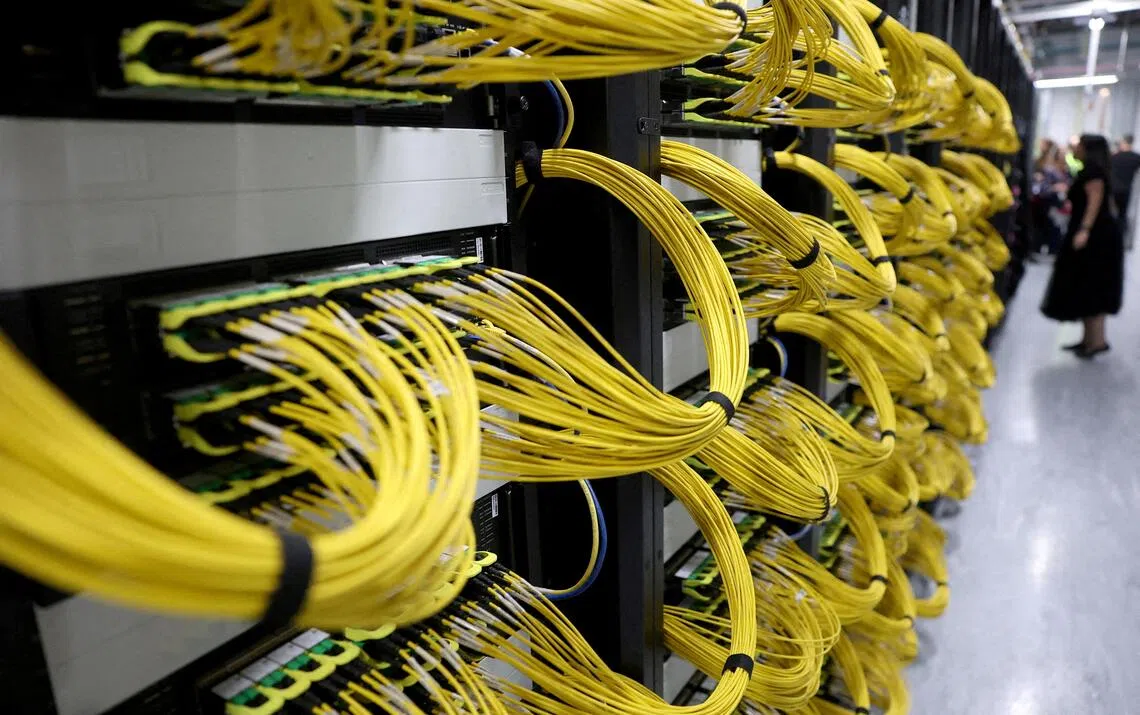
On opportunities in AI, Matson pointed out that his team is focused on “next-generation” infrastructure in private assets, such as data centres.
Looking ahead, he expects higher interest rates to affect not only the cost of debt, but also valuations. “If you have a slightly higher interest rate, all else (being) equal, valuations will have (to be) slightly more modest, and that can be quite interesting because you can buy things again.”
In contrast, prolonged periods of low interest rates, strong earnings and rising valuations can cause market participants to grow complacent and ignore fundamental risks which could be very dangerous, he said.
The ideal condition, he added, lies in between: moderate turbulence, where a “sea that is challenging” lets investors buy quality assets at reasonable valuations.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing
Retrenched PMETs who return on lower pay see median 25% wage cut

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Vietnam’s northern provinces, not Hanoi or Ho Chi Minh City, are powering near 10% GDP growth

