

NTT DC Reit H1 DPU beats IPO projection by 10% at US$0.0432
Tenant expansions at two California data centres lift portfolio occupancy to 97.5%
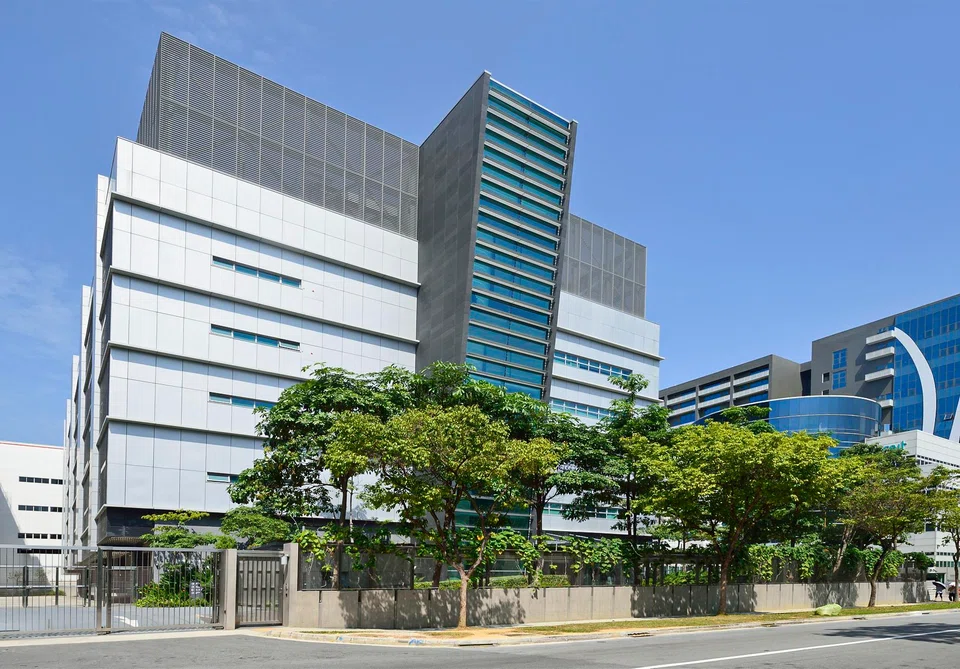
[SINGAPORE] NTT DC Real Estate Investment Trust (Reit) on Wednesday (Nov 11) posted a distribution per unit (DPU) of US$0.0432 for the first half of FY2026/27, 10 per cent above its initial public offering projection of US$0.0393. Net property income (NPI) exceeded forecasts and net finance costs came in lower than expected.
For the six months ended Sep 30, distributable income stood at US$45 million, against the projected US$40.9 million.
NPI was 4.9 per cent above projection at US$55.8 million, while gross revenue came in 2 per cent higher at US$119.8 million. The stronger NPI was attributed to increased tenant fit-out revenue, lower real estate taxes and favourable foreign exchange movements.
Net finance costs were also 5.5 per cent below projection at US$10.4 million, mainly due to lower interest rates.
The Reit’s leasing performance improved during H1, with portfolio occupancy by information technology load rising 1.6 percentage points to 97.5 per cent as at Sep 30, from 95.9 per cent three months earlier.
The increase was largely driven by expansions secured at its CA1 and CA3 data centres in California. Most of the leases commenced in September and are expected to contribute a full quarter of rental revenue from Q3 FY2026/27 onwards. Including leases signed but yet to commence, committed occupancy would rise to 98.1 per cent.

The Reit recorded rental reversion of 11.7 per cent during H1, largely driven by a 23 per cent rental reversion from the renewal of its SG1 NTT Master Services Agreement in the first quarter. It also secured lease renewals with a monthly base rent of US$903,000.
As at Sep 30, the portfolio’s weighted average lease expiry stood at four years, with 11.2 per cent of leases due to expire in the current financial year ending Mar 31, 2027.
The Reit’s aggregate leverage fell to 29.9 per cent as at Sep 30, from 31 per cent at end-June. Total debt stood at US$528 million, while the weighted average all-in interest rate declined to 3.8 per cent from 3.98 per cent.
Some 68.4 per cent of the Reit’s borrowings are on fixed rates, and it has no loan maturities until FY2028/29. Its existing loans also come with two 12-month extension options.
Separately, unitholders approved changes to the management fee structure on Nov 6. Under the revised arrangement, the performance fee will be linked to year-on-year DPU growth instead of NPI, with the new structure taking effect from FY2026/27.
The fee will be calculated at an annual rate of 0.1 per cent of deposited property if DPU growth exceeds 3 per cent but is below 5 per cent, and 0.2 per cent if growth is at least 5 per cent. DPU growth is calculated before accounting for the performance fee but after accounting for the base fee.
Units of NTT DC Reit fell 2.2 per cent or US$0.02 to close at US$0.90 on Wednesday, before the announcement.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Nvidia preparing to oust CEO Jensen Huang who had second affair with exec: reports
8M Real Estate said to be buying about 50 shophouses for around S$500 million
MSCI removes more Indonesian stocks, dealing fresh blow to market amid reform push
Swiftdata, owner of Nvidia-linked Megaspeed, lists address occupied by interior design firm

