

Preparing for climate risks helps companies weather Iran war shocks: SGX RegCo
Incorporating such factors in overall risk management is ‘a more holistic approach’
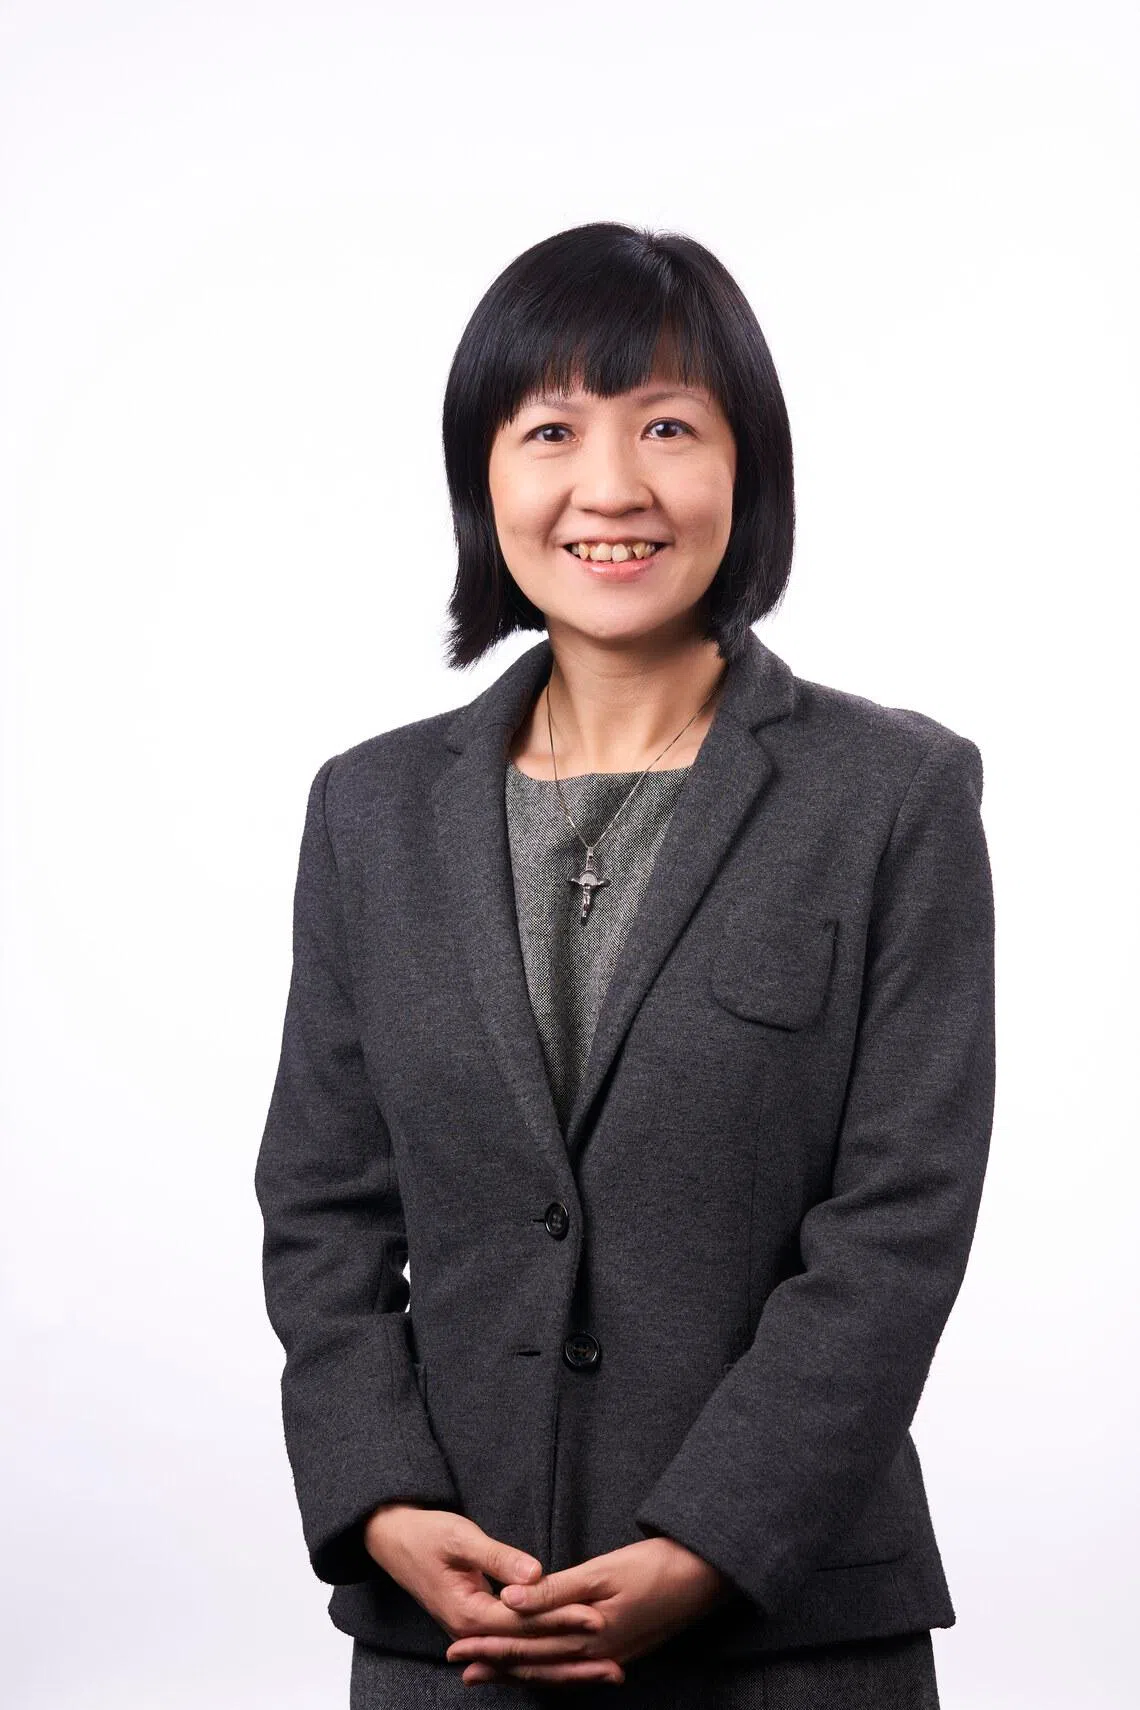
[SINGAPORE] Companies that have already taken steps to manage their climate-related risks are better able to respond to and withstand the energy shocks arising from the Iran war, said Eliza Tan, head of Singapore Exchange Regulation’s (SGX RegCo) sustainable development office.
The war, which began when the United States and Israel attacked Iran on Feb 28, has exposed companies’ reliance on fossil fuel-based energy sources, as well as the extent to which their operations can be disrupted as oil and gas prices surge.
However, those that have integrated climate-related risks into their overall risk-management strategy and adopted energy-efficient measures are better prepared for the latest shocks.
These electricity-demand reduction measures include installing solar panels on manufacturing facilities, or power-purchase agreements with renewable-energy providers.
The ongoing energy crisis has placed renewable energy at the forefront of governments’ and businesses’ agendas once again, after taking a backseat when US President Donald Trump returned to power.
Increasingly, it is being viewed as a main avenue for greater energy security and independence.
To cope with inadequate energy supply, fossil fuel-reliant companies in Asia have had to shut down part of their operations as a short-term measure or even just run part-time.
Several Singapore-based petrochemical and energy companies declared force majeure in March amid raw material supply disruptions caused by the conflict – specifically Iran’s closure of the Strait of Hormuz, a major choke point in the global oil and gas supply chain.
“Arising from this geopolitical development, energy security has become a strategic issue for companies,” Tan told The Business Times in an interview. “It will demonstrate how companies are managing these transition risks and reducing their vulnerability to volatility arising from reliance on fossil fuel-based energy.”
Many organisations could view climate-related risks as less immediate challenges amid the business disruptions arising from the Iran war. But Tan pointed out that incorporating climate considerations – alongside other principal risks such as operational or financial ones – is a more holistic approach to risk management.
For example, extreme weather events can crystallise over the short and medium terms, resulting in impairments to a company’s physical assets, disruptions in operations and, consequently, losses in revenue.
“Climate-related risks don’t pause because you have other pressures,” said Tan, noting that there will always be other critical issues such as supply chain disruptions. “Should I be still concerned about climate-related risk? It goes to the prioritisation of the risk.”
She explained: “When a company determines the magnitude of the impacts arising from climate-related risks, alongside the other principal risks, it will also have to look at the probability of the risk crystallising.”
The latest climate science indicates that physical risks are accelerating, which means that more frequent, high-impact events are expected.
Climate-related disclosures
One way companies can show investors how they are mitigating these risks is through sustainability reporting.
SGX RegCo and the Accounting and Corporate Regulatory Authority have postponed most of the sustainability reporting requirements for all Singapore-listed companies except constituents of the Straits Times Index (STI).
But they must still report data on emissions arising from business operations – called Scope 1 emissions – and their purchase of electricity, which fall under Scope 2.
Only listed companies with a market capitalisation exceeding S$1 billion are required to release sustainability reports aligned with the International Sustainability Standards Board (ISSB) for the 2028 financial year. Those with market caps under S$1 billion will have to do so from FY2030. Previously, all issuers had to report these disclosures from FY2025.
When a company discloses that its emissions are trending downward, it suggests that its business model is evolving as it reduces its reliance on fossil fuels.
“Scope 1 and 2 emissions data provide additional layers in terms of how the companies are managing the underlying exposures,” said Tan. “It shows the long-term resilience of the business model and also the quality of the management.”
She added that it is important for companies to show the connections between their strategies, climate-related disclosures and financial statements “because investors and boards are not looking at climate-related disclosures in isolation”.
“(They have) to tie back to how (they are) embedded into corporate strategy, in terms of risk management, in terms of how the company is leveraging opportunities, and that will eventually translate into financial effects.”
Although companies – excluding the STI constituents – are not mandated to go beyond Scope 1 and 2 emissions in their sustainability reports, Tan said that market forces will compel some firms to disclose more than what is required.
For one, investors will find a way to get the information they are looking for on a particular company even if it has not been disclosed. “As a result, the company will not be in control of the information out there, which may not be painting an accurate picture of what’s happening in the company,” Tan added.
Non-STI constituent issuers will also have to demonstrate progress in their incorporation of ISSB, even though they are not required to fully align their reporting with these standards yet.
“If the stakeholders require additional information by the company, the company will be motivated to provide such disclosures on top of what is required under our reporting requirements,” said Tan.
For example, smaller listed companies that have large multinational corporations as their customers may need to provide their Scope 1 and 2 emissions data to them.
This is because large corporates could be required to report Scope 3 emissions – which refer to indirect emissions from a company’s value chain – in other jurisdictions, such as Malaysia. “If they are not already reporting their Scope 1 and 2 emissions, they are being screened out of the procurement process,” she added.
She believes that the renewed focus on the energy transition by investors and other stakeholders – albeit motivated more by energy security than sustainability – will spur companies to pay greater attention to climate-related disclosures.
“Ultimately, we want companies to produce that decision-useful information… in terms of ‘where do I allocate more resources to? Expanding my business, or my risk management?’” she said.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

