Malaysia’s Big Caring eyes Singapore expansion with YMS buyout ahead of IPO
The pharmacy giant is set to acquire the Singapore medical retailer
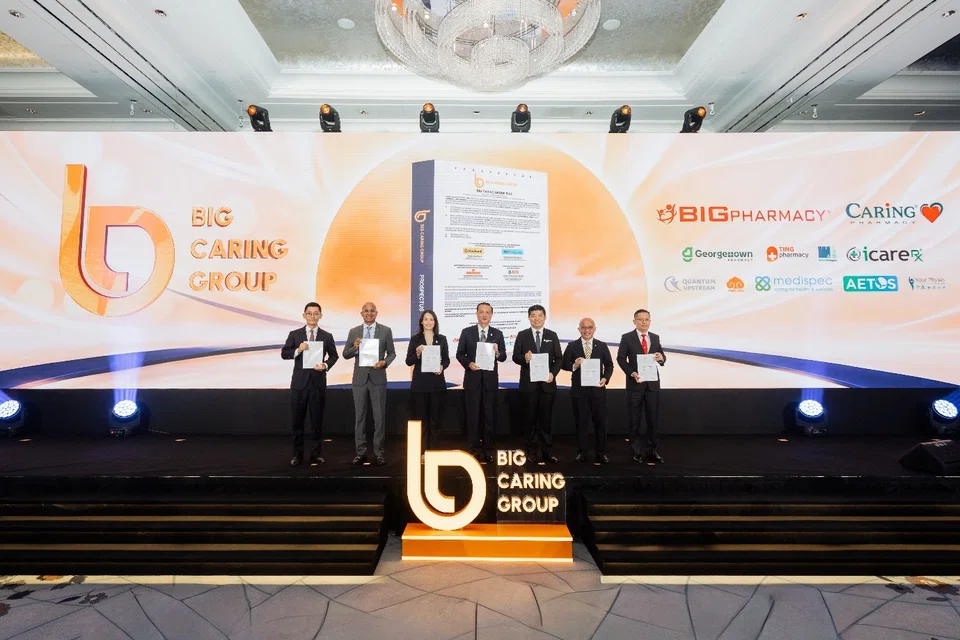
[KUALA LUMPUR] Malaysia’s largest retail pharmacy operator Big Caring Group is targeting an expansion into Singapore through a pending acquisition, even as it prepares for an initial public offering that could value the retailer at RM8 billion (US$1.9 billion).
Big Caring recently signed an agreement to acquire a 96 per cent stake in Yeap Medical Supplies (YMS), a Singapore-based medical goods wholesaler and retailer, its prospectus indicates.
Headquartered in Yishun, YMS is an established distributor and service provider specialising in geriatric care, medical devices and home-care equipment. It operates seven outlets in the city-state through its retail arm, Pharmex Healthcare.
The business was founded by Richard Yeap in 1983 with Pharmex Healthcare. His son, Victor Yeap, later took over operations and formally incorporated YMS in December 2000, in a move to drive its wholesale expansion.
Big Caring’s group managing director and CEO Lee Meng Chuan said that the group believes the deal, when finalised, would enable the company to “expand more rapidly into Singapore”.
“We are still working on it and will make an announcement once everything is finalised,” he added.
Speaking at a media briefing after the launch of the prospectus on Thursday (Oct 29), Lee said overseas opportunities extend beyond running retail outlets.
The group is also seeking overseas business for its manufacturing operations, and opportunities to distribute and sell its own-brand products abroad.
The potential expansion comes as Big Caring prepares to list on Bursa Malaysia’s Main Market on Nov 19, with a retail application price of RM1.08 per share.
SEE ALSO
Second-largest IPO this year
The offering would be Malaysia’s second-largest IPO by funds raised so far this year, said John Chong, Maybank’s group CEO for global banking.
The IPO trails only Sunway Healthcare Holdings, which debuted on Bursa Malaysia in March with a market capitalisation of about RM16.7 billion.
Big Caring’s IPO comprises up to 1.88 billion shares, representing 25.5 per cent of its enlarged share capital. The offering is expected to raise about RM2.03 billion before any over-allotment.
Of that, RM637.8 million would go to the company through the issuance of 590.5 million new shares. The remaining proceeds would accrue to selling shareholders offering up to 1.29 billion existing shares, accounting for nearly 69 per cent of the offering.
The final retail price will be the lower of RM1.08 or the institutional price determined through book building.
The IPO has secured 19 cornerstone investors, including the International Finance Corporation, Fidelity and JP Morgan Asset Management. They have committed to 665.5 million shares, equivalent to 96.2 per cent of the institutional offering.
Big Caring plans to use RM570.7 million, or nearly 90 per cent of its fresh proceeds, to pay down its bank borrowings. Another RM30 million will fund a new distribution centre, while RM37.1 million will cover listing expenses.
Its chief financial officer Chin Shin Yi expects the debt repayment to generate annual interest savings of RM26.3 million, based on its average FY2026 borrowing cost of 4.6 per cent.
Loui Low, head of research at M+Global, sees the group’s debt repayment plan as a strategic positive that will strengthen its balance sheet and lower interest costs.
Based on his preliminary estimates, the interest savings could potentially boost annual earnings by roughly 10 per cent, depending on repayment timing and final financing costs.
“The participation of 19 cornerstone investors also signals strong institutional interest in the offering,” he added.
Expansion plans
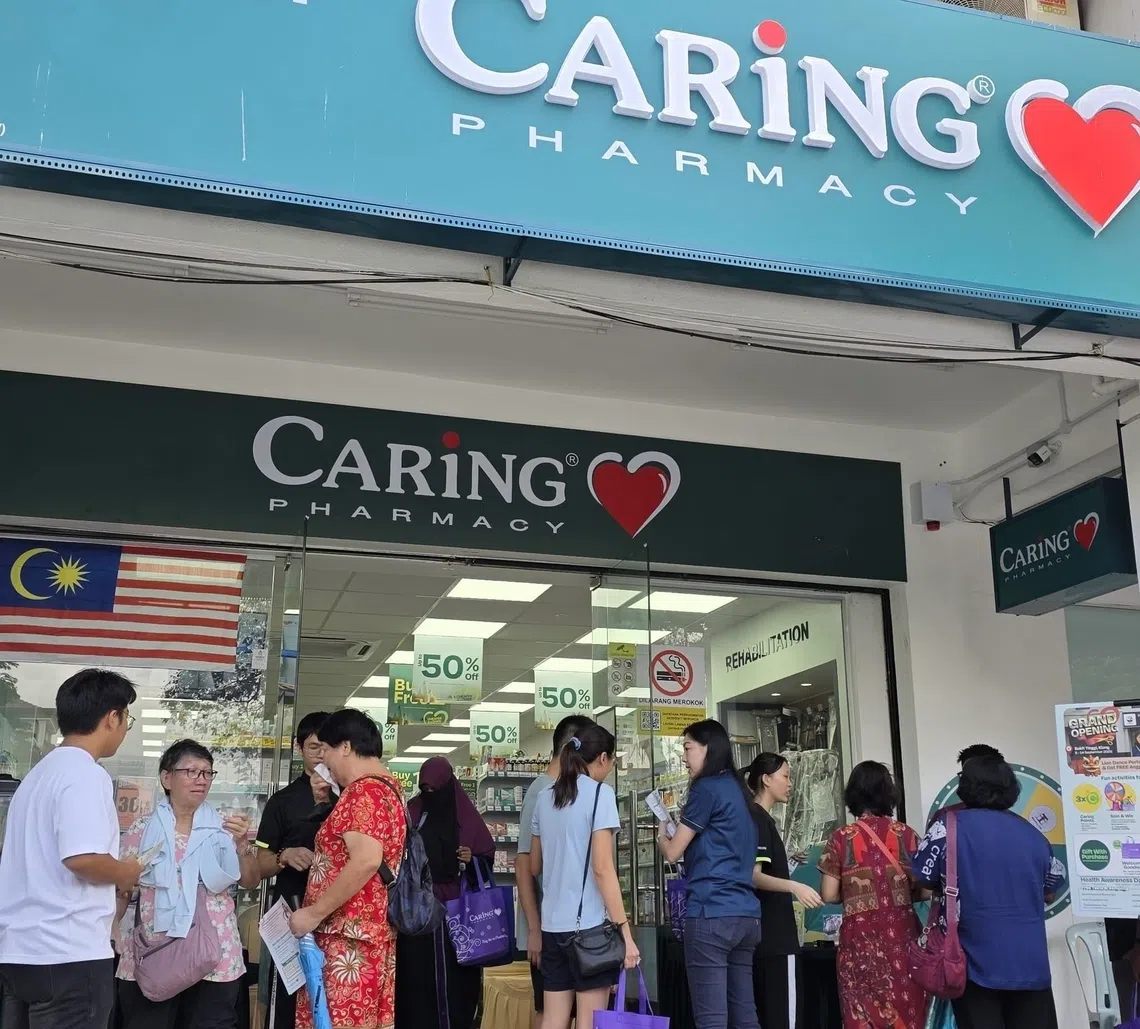
The group plans to open 40 to 50 outlets a year in the next three to five years. Lee noted that new outlets historically hit Ebitda breakeven within a year, with investment payback taking two to three years.
“We will continue to pursue acquisitions with discipline, strengthening our network and capabilities,” he added.
It also sees further opportunities in established markets such as Kuala Lumpur and Johor, with locations and brands selected according to local demand.
Big Caring operated 668 outlets nationwide as at end-September, under brands including Big Pharmacy, Caring Pharmacy, Georgetown Pharmacy and Your Physio Therapy and Rehab Centre.
Lee noted that the new distribution centre would be near its existing Bukit Raja facility in Selangor, although an exact location had yet to be identified. The existing centre was operating at 80.2 per cent capacity at the end of September.
According to 2025 research by Frost & Sullivan, Big Caring held about a quarter share of Malaysia’s retail pharmacy market by revenue.
Its revenue rose 17.9 per cent to RM4 billion in the financial year ended Jun 30, 2026, and profit attributable to shareholders increased 56.7 per cent to RM191.6 million.
Gross margin widened to 30.1 per cent from 24.8 per cent, and attributable-profit margin improved to 4.8 per cent from 3.6 per cent.
The prospectus showed that the retail segment generated 92.9 per cent of total revenue; healthcare, pharmaceutical, and general merchandise accounted for the rest.
Tradeview Capital portfolio manager Neoh Jia Man said: “At an estimated FY27 forward price-to-earnings ratio of 25.6 times, the valuation is reasonable, given the group’s economies of scale and market positioning.”
But he warned that broader market headwinds affecting consumer-related stocks could temper its listing-day performance.
The group targets dividends of up to 50 per cent of attributable profit, although management said acquisition opportunities could result in a lower payout, depending on cash flow.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.