


Analysts see Genting Malaysia offer as low, say upside not priced into bid
Research houses say the RM2.35 offer fails to capture upside from New York casino licence and global expansion plans
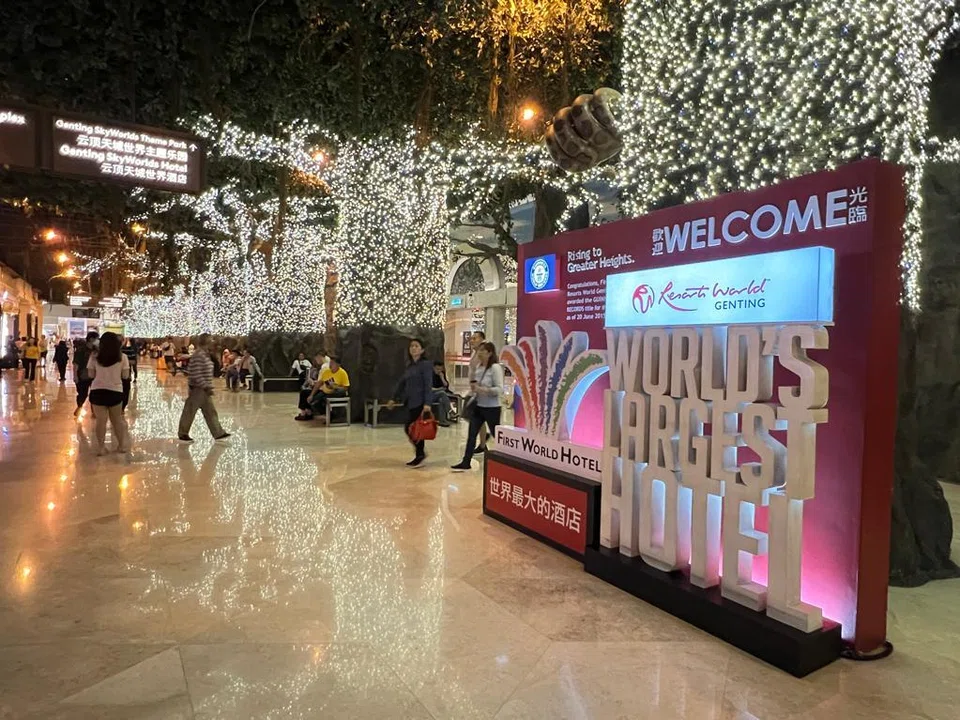
[KUALA LUMPUR] Shares of Genting Malaysia (GENM) and parent company Genting Bhd (Genting) rallied on Tuesday (Oct 14) on news of a massive buyout bid worth RM6.7 billion (S$2.1 billion) that could see the group’s crown jewel delisted from Bursa Malaysia.
Analysts appear mixed on the price tag of RM2.35 apiece under the conditional voluntary takeover offer (VTO) by Genting to acquire the remaining 50.64 per cent or 2.87 billion shares in GENM that it does not already own.
At first glance, the VTO price “appears a tad attractive”, said Maybank Investment Bank.
At RM2.35 a share, the offer price stands at 10 per cent above GENM’s last traded price of RM2.14 pre-announcement and 22.9 per cent above the market prices of the shares over the last 12 months.
“That said, we believe that the VTO price does not reflect three catalysts that could raise our GENM fair value significantly as we have flagged before,” said the research house.
The three catalysts are the potential win of a downstate commercial casino licence in New York; the revaluation of land in Miami GENM acquired in 2011; and the potential sale of the non-gaming assets in New York by its wholly owned Empire Resorts.
“Investors should not accept the VTO, in our view,” said Maybank.
Kenneth Leong, head of research at Berjaya Securities, noted that the VTO price fails to account for the company’s future prospects, specifically its overseas expansion, pending gaming licences and diversified hospitality segment.
To illustrate the potential undervaluation, he pointed to an international precedent. “If we compare it to Crown Resorts in Australia that was privatised at A$13.10 per share – about a price-to-book (P/B) ratio of 1.99 times, Genting Malaysia’s privatisation deal is priced only at a P/B ratio of 1.14 times,” he told The Business Times.
The offer is intended to secure majority control of GENM ahead of the significant capital investment required for the group’s New York commercial casino bid, with announcement expected by Dec 1 and an award by year-end.
TA Securities also advised shareholders to reject the offer, arguing that the privatisation is “not in the best interest of Genting group” given GENM’s future funding needs.
The research house highlighted that this need is particularly acute given GENM’s plan to spend US$5.5 billion to upgrade Resorts World New York City if it secures the critical New York casino licence.
TA Securities estimates the current offer price implies an undemanding 6.4 times EV/Ebitda (enterprise value over earnings before interest, taxes, depreciation and amortisation) multiple based on FY2026 earnings, compared with a regional peer average of 8.4 times, signalling undervaluation.
While Genting could easily raise its stake to 50 per cent through open-market purchases, TA Securities believes achieving the 75 per cent threshold required for full privatisation will be difficult due to the low offer price.
It, however, noted that the chance of Genting revising the price is slim, as the GENM board has no incentive to seek a competing bid.
Others described the offer as a reasonable exit opportunity for retail investors, given GENM’s discounted valuation and lingering concerns over related-party transactions.
CGS International analysts Lew Cheng Wei and Prem Jearajasingam said that Genting likely views GENM as undervalued and may be positioning the group for restructuring.
“We reckon there is a possibility that Genting could relist GENM in the future after possibly restructuring it, and when there is more positivity towards its earnings outlook,” they said.
Hong Leong Investment Bank analyst Chee Kok Siang said Genting’s offer price of RM2.35 a share exceeds his target price of RM2.06 apiece. He also advised minority shareholders to accept the offer.
Governance observers raised concerns
However, governance observers urged caution. Dr Ismet Yusoff, chief executive officer of the Minority Shareholders Watch Group, advised minority investors to wait for the independent advice circular before deciding whether to accept the offer.
He said the fairness of a voluntary takeover should not be assessed solely on short-term price premiums, but also on the company’s revalued net asset value, future earnings trajectory and strategic opportunities – including its bid for a New York casino licence.
“Given Genting Malaysia’s established asset base, cash-generating profile and global footprint, minority shareholders may question whether the offer fully reflects the company’s intrinsic value and long-term potential,” he told BT.
Dr Ismet added that large-scale transactions of this nature can influence investor perceptions of fairness and corporate governance standards.
“Transparency, valuation justification and regulatory oversight are crucial. If these elements are robust, confidence in Malaysia’s capital market will be strengthened; if not, it could dampen retail participation,” he added.
Rising share prices
Both counters posted sharp gains on high trading volumes when trading resumed, following a suspension on Monday pending the announcement.
GENM opened 9.8 per cent higher at RM2.35 from its previous close of RM2.14, briefly rising to RM2.36 before easing to RM2.31. More than 119 million shares changed hands within the first hour of trade, making it one of the most actively traded counters on the Malaysian bourse.
Parent company Genting climbed nearly 5 per cent to RM3 at the opening bell, with about 18.7 million shares traded.
Singapore-listed Genting Singapore (GENS) rose 1.4 per cent to S$0.725 by midday trading. DBS Group Research expects higher dividends from GENS – given its strong net cash position and robust free cash flow – as the most “probably avenue” to support Genting’s leverage.
At Tuesday’s close, GenM was up 8.4 per cent to RM2.32, with about 242.6 million shares traded, while Genting advanced 5.2 per cent to RM3.01 on a volume of 36.8 million shares. Genting Plantations slipped 1.2 per cent to RM4.85, and Genting Singapore gained 1.4 per cent to S$0.72.
“Should the privatisation succeed, we estimate Genting will move to a net debt position of about RM21 billion with net debt to Ebitda of around 2.4 times by end-FY2025, which remains manageable”, said DBS.
However, if GENM secures the New York casino licence and undertakes the anticipated US$5.5 billion investment, the resulting funding needs would be substantial, the house remarked.
Short-term impact to Genting
The proposed buyout – the largest in the country this year, next to the RM7.3 billion privatisation of Malaysia Airports which was completed earlier this year, would consolidate Genting’s gaming and hospitality assets under a single unlisted entity.
For Genting, Chee noted that there will be a short-term negative impact on earnings and the balance sheet due to higher interest expenses and additional debt.
“Nevertheless, we maintain a neutral view on the offer price given the potential value accretion from winning the New York gaming licence. Forecasts remain unchanged pending completion of the takeover,” he added.
Berjaya Securities’ Leong added that the full consolidation of GENM’s financial performance is expected to be earnings accretive for Genting, which could subsequently translate into a stronger future dividend payout for the parent company.
The privatisation proposal comes at a critical juncture for Genting, which has been pursuing opportunities to expand its global footprint amid intensifying competition in Asia’s gaming sector.
The group’s bid for a coveted New York State casino licence, one of four remaining to be awarded, is seen as a potential game-changer.
Should Genting secure the licence, analysts believe the project could require significant upfront capital expenditure, estimated at between US$2 billion and US$3 billion, which would be easier to fund within a private structure.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

