



Malaysia’s Boost bets on MSMEs, not hype, in its race to unicorn status
It is eyeing a valuation target of ‘a couple of billion dollars’ within five years
[KUALA LUMPUR] In a fintech arena long driven by scale-first, profit-later strategies, Malaysia’s Boost – the fintech arm of regional telco Axiata Group and partly owned by Singapore insurer Great Eastern – is trying to chart a more measured course, while still chasing unicorn ambitions.
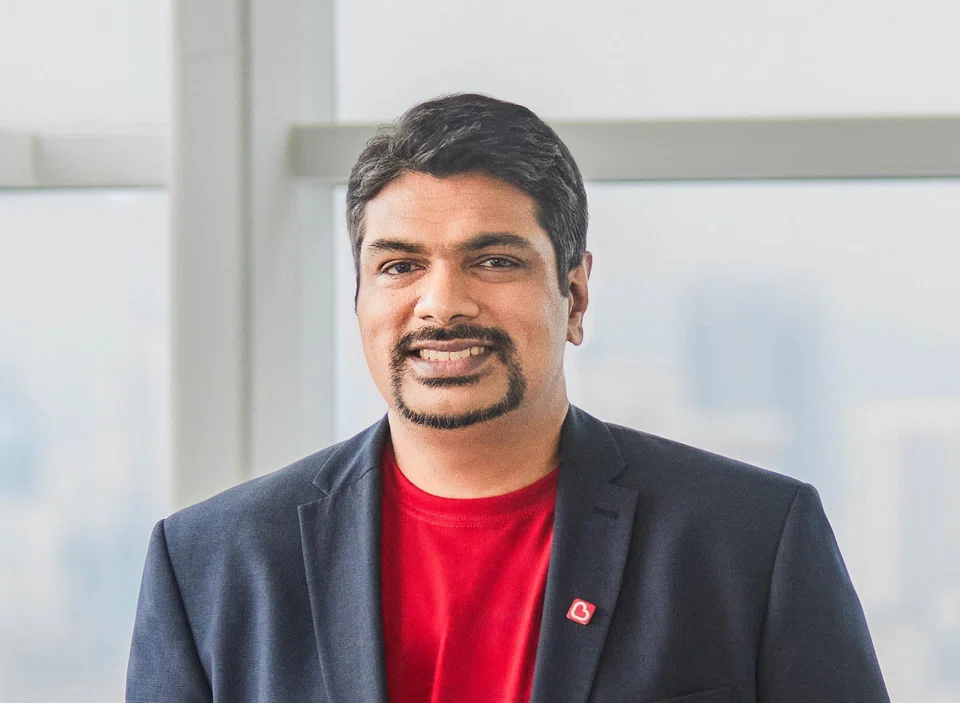
Boost Group chief executive officer Sheyantha Abeykoon was clear-eyed about the company’s goals, discreetly but firmly signalling an ambition to become Malaysia’s next unicorn, with a valuation target of “a couple of billion dollars” within five years.
A listing plan is also on the drawing board, though Abeykoon declined to commit to a timeline.
“We are actively exploring options for a listing. There are ongoing discussions and, ultimately, we expect to have some form of liquidity event, whether through an IPO (initial public offering) or another mechanism,” he told The Business Times.
“The exact structure and timing are still being worked out, but it is definitely on the horizon. Our shareholders are very supportive and management is fully committed to pursuing it,” he added.
Boost’s last publicly reported valuation dates back to 2020, when Great Eastern acquired a minority stake, valuing the company at about US$320 million.
Unlike many fintech peers chasing headline growth, Abeykoon believes valuation will follow discipline, particularly in lending to micro, small and medium-sized enterprises (MSMEs), which form the backbone of Boost’s loan book.
Building a full-spectrum fintech
That philosophy underpins Boost’s evolution from a payments-led fintech into a broader financial services group spanning merchant acquiring, lending and digital banking.
Axiata has continued to seek fresh capital to fund the fintech arm’s expansion. The move was confirmed by Axiata chief executive Vivek Sood during a February results briefing, when he said the group was in talks with a potential new shareholder, pending regulatory approval.
Currently, Axiata owns 77.7 per cent of Boost, alongside OCBC-controlled Great Eastern (nearly 20 per cent) and Mitsui & Co (2.3 per cent).
The Boost ecosystem also comprises its namesake app and regional payments player Boost Connect.
At the centre of this ecosystem is Boost Bank – a joint venture with RHB Bank and one of Malaysia’s five digital banking licensees. Boost holds a 60 per cent stake, with RHB owning the remaining 40 per cent.
Revenue growing, losses narrowing
For the first nine months of 2025, Boost’s revenue rose 49 per cent year on year to RM149.1 million (S$47.1 million), driven largely by growth in lending income. However, higher operating costs and taxes weighed on the bottom line.
Ebitda (earnings before interest, taxes, depreciation and amortisation) loss widened 9 per cent to RM109 million, while net loss deepened 4.4 per cent to RM159.9 million.
Revenue gains were concentrated in Boost Credit and Boost Bank, reflecting the steady expansion of the group’s loan books.
Boost Bank, which launched in June 2024, is now about 18 months into operations. Deposits have reached around RM600 million, while the loan book has surpassed RM300 million and is projected to reach RM350 million by end-2025.
MSMEs at the core
Boost’s growth story stands out not only for its pace, but for where its balance sheet is concentrated. Nearly the entire loan portfolio is deployed into small enterprises and MSMEs – a segment long underserved despite its central role in Malaysia’s economy.
Before becoming a digital bank, the group built its reputation as a specialised MSME lender, a foundation that helped it secure a banking licence.
According to Abeykoon, Boost caters to underserved MSMEs with loans averaging RM300,000 and most facilities below RM1 million, anchoring the portfolio firmly in micro-entrepreneurs, small retailers, wholesalers and family run enterprises.
Boost uses a digital-native platform to make small loans profitable, it said, whereas traditional banks are slowed down by old systems and manual work.
That strategy was tested during the pandemic, when Boost partnered Malaysia’s Ministry of Finance to deliver tailored financing, including interest-only loans and deferred repayments, that helped keep thousands of small firms afloat.
“Many have since expanded as the economy reopened, reinforcing Boost’s belief that SME lending can be both impactful and scalable,” said Abeykoon.
He said SME lending and payments now form Boost’s dual-revenue engine. As one of PayNet’s largest merchant acquirers, the group has leveraged its scale in payments to fuel its high-growth lending business.
“Together, these sectors account for the bulk of Boost’s recent revenue surge, and are expected to remain the primary growth drivers over the next three years,” he added.
Strategically, Abeykoon describes these businesses as entry points rather than end points.
“Payments and lending open the door... Once trust is established, the relationship can become much wider and deeper,” he said, adding that this foundation will lead to the adoption of wider services, including deposits, loyalty programmes and artificial intelligence-driven tools to streamline the daily operations.
Embedded banking advantage
A key differentiator has been embedded banking. Boost was the first in Malaysia to integrate banking products directly into its e-wallet, allowing users to move seamlessly from payments to deposits without a separate onboarding process.
About 70 per cent of Boost Bank’s deposit customers were converted from its e-wallet base, achieved at virtually zero acquisition cost.
Abeykoon said this demonstrates how embedded finance can scale more efficiently than stand-alone banking apps competing for attention.
Operational discipline underpins that efficiency. Boost Bank operates with about 180 staff, relying heavily on automation and algorithms to replace manual processes where possible.
Caution in BNPL
That discipline extends to consumer lending. While buy now, pay later (BNPL) remains popular, Boost has opted for controlled growth, emphasising affordability checks and non-predatory fees.
Malaysia’s BNPL market had more than 6.5 million active accounts and RM4.2 billion in outstanding balances as at end-September, according to data from the Consumer Credit Oversight Board Task Force, which is led by the Ministry of Finance, Bank Negara Malaysia and the Securities Commission Malaysia.
Abeykoon warned that unchecked expansion carries risks. Rapid customer acquisition is easy in consumer finance, he said, but over-leveraging borrowers can quickly undermine portfolio quality and social trust.
“You can grow very fast... but if you don’t lend responsibly, you don’t build a sustainable business,” he added.
Scaling with restraint
While Boost has not disclosed specific targets for customer numbers, assets or revenue, Abeykoon said the internal plans are calibrated around crossing the US$1 billion mark and eventually reaching a multibillion-dollar valuation.
Regional expansion forms part of that equation, but not at any cost. Boost’s current focus remains on Malaysia and Indonesia, where it has operated for nearly five years.
“Indonesia’s larger population and higher proportion of underserved customers offer scale, but also higher risk,” he said.
Beyond these two markets, Boost has launched pilots in Cambodia and other neighbouring countries, often leveraging Axiata’s regional footprint.
Still, Abeykoon is cautious about spreading capital and management attention too thinly.
He noted that financial services are heavily regulated and market-specific. “Boost will only enter markets where it believes it has both a ‘right to play’ and a ‘right to win’,” he added.






