

What’s taking Hongkong Land fund so long to seal Marina One deal?
The sheer asset size may mean the fund could require more time to raise equity
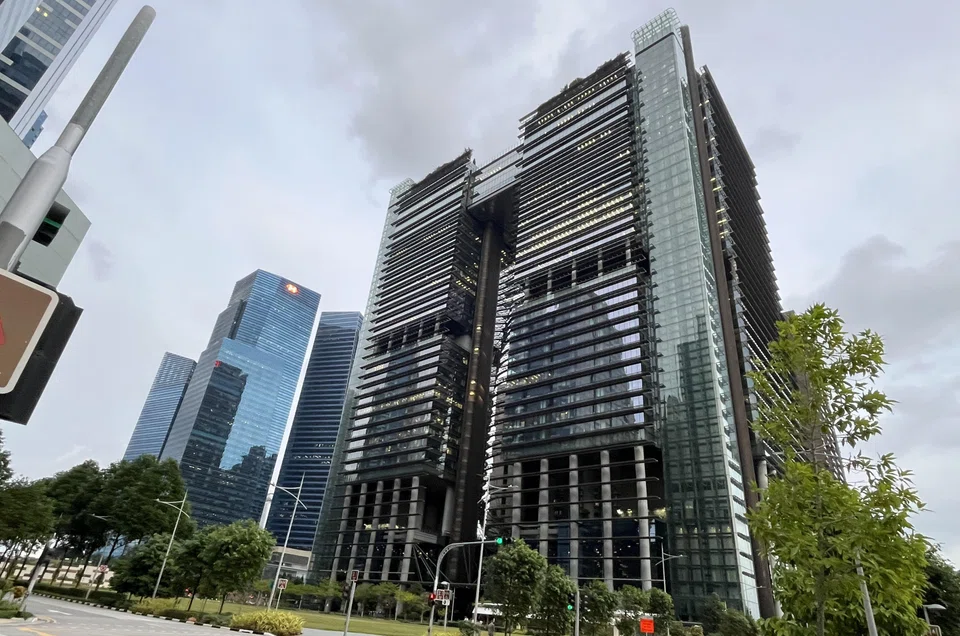
[SINGAPORE] For several months now, market watchers have been expecting Hongkong Land to announce an acquisition of the commercial component of the Marina One complex.
The asset, with an asking price of about S$5.7 billion, comprises about 1.88 million square feet (sq ft) of net lettable area of premium Grade A office space and 140,000 sq ft of retail space.
This is part of a mixed-use project developed by M+S, a 60:40 joint venture between Malaysian sovereign wealth fund (SWF) Khazanah Nasional and Singapore state investor Temasek.
Completed nearly a decade ago, the integrated development is on a site with 99-year leasehold tenure from Jul 1, 2011, leaving a balance of about 83 years and nine months.
Earlier this year, Hongkong Land launched the open-end Singapore Central Private Real Estate Fund (SCPREF) as part of the group’s pivot towards property fund management under the new direction charted by Michael Smith, who was appointed chief executive in April 2024.
At inception, the fund had S$8.2 billion worth of assets.
These include one-third stakes in Marina Bay Financial Centre Towers 1 and 2, Marina Bay Link Mall and One Raffles Quay, together with 100 per cent interest in One Raffles Link – all injected by Hongkong Land.
The company is the general partner and manager of the fund, and holds a majority stake in it at inception.
Also in the fund’s initial portfolio is a 100 per cent interest in Asia Square Tower 1, acquired from SWF Qatar Investment Authority (QIA).
Subsequently, SCPREF acquired Wheelock Place in Orchard Road for about S$1.1 billion, taking the fund’s assets under management (AUM) to S$9.4 billion, based on Jun 30, 2026 valuations.
If SCPREF buys the Marina One asset, as widely tipped by the market, it would reach the fund’s S$15 billion target – in one fell swoop.
Why has a deal not materialised yet?
Marina One was marketed via an expression of interest exercise; the initial submission of offers closed in the first half of this year.
In late July, The Business Times reported that the bid selection process was still ongoing. Industry watchers said Hongkong Land had offered the highest price for the property but its offer came with a string of conditions for the sale agreement.
Another contender for the asset is Mapletree Investments. The subsidiary of Temasek had served as the joint project manager, alongside UEM Sunrise of Malaysia, for the Marina One development.
Its participation in the bidding process for Marina One’s office and retail space, has been seen as providing some competition to ensure a decent exit price for M+S.
Pending the finalisation of terms, M+S reportedly planned to award the property to the successful bidder as early as August.
Two months on, and with no sign of a deal in sight, some industry watchers say there may be complexities, possibly related to the sale of shares in the special purpose vehicle that holds Marina One’s commercial component.
Or Khazanah and Temasek may have been asked to take part of the payment for a sale of Marina One in the form of units in SCPREF.
The main reason holding back a deal on Marina One between SCPREF and M+S may be the sheer size of the transaction. At over S$5 billion, this would be one of the biggest single-asset property investment deals in Singapore (excluding related-party transactions).
Along with Hongkong Land, QIA and APG Asset Management are also founding investors in the fund. Other investors in SCPREF include an established South-east Asia SWF.
When Hongkong Land launched SCPREF on Feb 3, it was made clear that the fund was in discussions to bring in additional institutional investors.
Perhaps SCPREF needs more time to raise the necessary equity from the fund’s existing and/or new investors.
Let’s say the Marina One office and retail space is priced at S$5.5 billion. Assuming borrowings of 50 to 60 per cent to fund the purchase, SCPREF would still have to raise S$2.2 billion to S$2.75 billion of equity.
Waning investor appetite for Singapore offices
Investor appetite for big-ticket Singapore office assets is weaker currently than it was six months ago.
The spread between office net yields – currently at about 3 to 3.5 per cent for a triple A Grade CBD office asset like Marina One – and borrowing cost is expected to come down. The fixed interest rate for longer-tenor loans has moved up.
It may be challenging for some institutional investors to get approval from their investment committees to buy Singapore offices at the moment.
The current tightness in the Singapore office market is being driven by supply constraints in the Central Business District rather than strong demand.
It is unrealistic to expect office demand to grow at an exponential rate, in the face of further adoption of AI and with flexible working arrangements still in place.
For SWFs and other institutional investors, more attractive returns beckon in other sectors, even within Singapore – such as retail malls, logistics, data centres and life science – or other alternative investments.
Risk diversification is also an important strategy. Investors may be reluctant to lock up large amounts of capital in a single Singapore office asset – or in a single fund.
Time to tweak strategy?
Where do all the above considerations leave Hongkong Land and SCPREF with regard to the Marina One acquisition plan?
The fund could tweak its strategy. Instead of buying a gigantic asset like Marina One, it could make a series of smaller acquisitions while sticking to its focus on high-quality, income-generating commercial assets in Singapore’s CBD and Orchard Road district.
SCPREF may just take a longer time to reach its AUM goal.
Another option could be for Hongkong Land to find a partner for SCPREF – perhaps in a rival – to buy up Marina One. Market watchers believe that within the M+S consortium, it is probably Khazanah that is more eager to exit Marina One.
Mapletree Investments’ parent Temasek could be amenable to holding its 40 per cent stake in the asset for a while longer. One scenario would be for Temasek to transfer its stake to Mapletree while SCPREF acquires the 60 per cent held by Khazanah.
On the other hand, Mapletree could press on with its rival bid for 100 per cent interest in the Marina One office and retail space. Its price may be lower than that offered by SCPREF, but it may have made fewer conditions on the vendors.
Effectively, from a Temasek group perspective, the outlay to gain full control of the Marina One asset would be for only the 60 per cent stake held by Khazanah.
Mapletree knows the asset inside out.
It may be high time for the major real estate group to have full ownership of a premium Grade A CBD office asset in its home market.






