

Why Mamdani’s New York has to fight to retain its crown
With Singapore, London and Dubai doing more to attract talent, the world’s premier financial hub is finding out its title is contestable
NEW York is still the world’s premier financial centre. It is also, for the first time in a long while, a centre that has to act as if the title is contestable – because it is.
The most recent Global Financial Centres Index, published in March, kept New York in first place. But just a single rating point separates it from London. Hong Kong sits one behind London. Singapore is one behind Hong Kong.
Four cities, separated by what amounts to a rounding error.
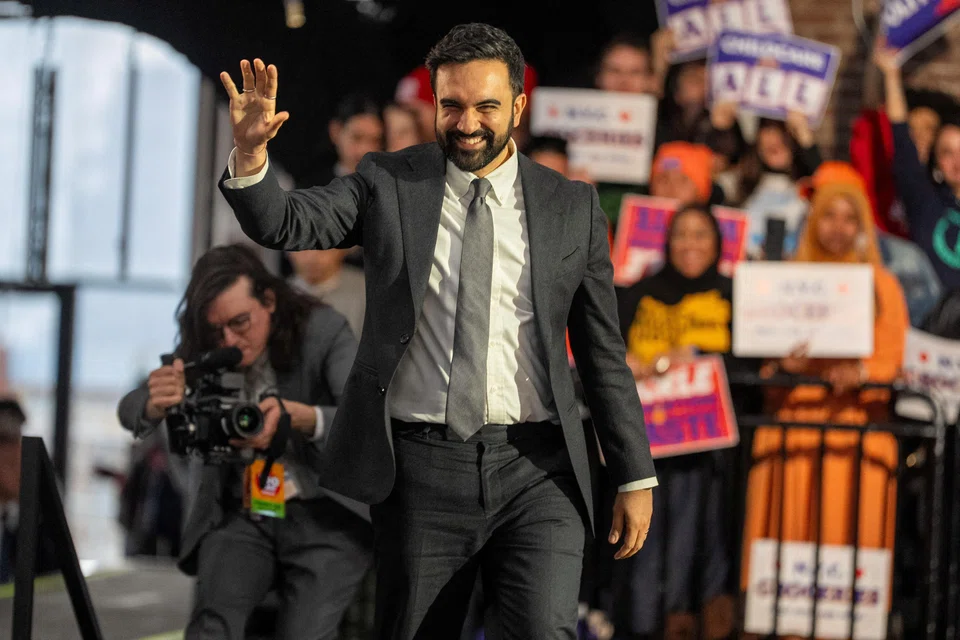
Into that environment walks Mayor Zohran Mamdani, who took office in January with the most explicitly redistributive platform any New York mayor has carried in living memory.
The substantive proposal at the heart of his agenda – raising the city’s top personal income tax rate by two points, on top of an already nation-leading state-and-city combined rate of 14.776 per cent – would put New York’s top earners at a marginal rate of roughly 16.78 per cent. That is before federal taxes.
That is before anyone has done anything ambitious with capital.
Hot on the heels
Compare the destination cities that now matter most.
Singapore taxes personal income at a top rate of 24 per cent, but with no tax on capital gains, no tax on most dividends and a 17 per cent headline corporate rate that, in practice, is often lower through targeted incentives.
It is English-speaking, has a common law system, is politically stable, and sits in the time zone where the next generation of capital allocation is playing out.
Over the past five years, it has become the world’s family office capital, multiplying the number of registered single family offices roughly 10 times.
The Monetary Authority of Singapore is not a regulator that financial firms fear; it is one they relocate to be near.
Hong Kong remains an extraordinary banking centre despite its political complications. London, even after Brexit, still leads in foreign exchange and global insurance.
Dubai has entered the top 10, and is openly courting hedge funds and private-credit shops with a regulatory regime designed in the language of the people it wants to attract.
None of these centres is trying to replace New York wholesale. They do not have to.
They only have to be the obvious second office, the obvious place for the next fund, the obvious destination for the next 200 partners who would have lived in Tribeca a decade ago.
Swaying the margin
This is the competitive structure Mamdani inherited, and it is the one his choices will be measured against.
The defenders of the mayor’s tax programme make a reasonable point: The research on millionaire flight is more cautious than its loudest critics suggest. Roughly 2.4 per cent of millionaires move in any given year, and only a fraction of those moves are tax-motivated.
The wealthy New Yorker who threatens on X to decamp to Palm Beach, more often than not, is still in Tribeca a year later.
The headlines about Apollo Global Management looking at Texas and Florida as possible places for its second headquarters, and news of Citadel CEO Ken Griffin saying his company is “doubling down” in Miami are noisy. But the empirical base case is not mass exodus.
That, however, is the wrong question. The question is not whether existing wealth leaves. It is about where new wealth chooses to form.
New York’s share of US millionaires dropped from 6.5 per cent in 2010 to 4.2 per cent in 2022, a 35 per cent decline, even as the absolute number rose.
The city kept what it had; it did not get the growth.
The marginal hedge fund analyst, the marginal partner at a private-credit shop, the marginal deputy of a sovereign wealth fund – these are the people who, on the margin, are now plausibly choosing Miami, Austin, Dubai or Singapore over the West Village.
A few thousand such decisions a year, compounded for a decade, is how a financial capital loses its lead.
Negotiations with finance
To his credit, the mayor seems to know this.
His meetings last month with Jamie Dimon at JPMorgan Chase and David Solomon at Goldman Sachs were not the actions of someone who believes the financial sector is replaceable.
They were the actions of a politician who has done the arithmetic on his own budget – one that depends, on its revenue side, on the very people his rhetoric has at times disparaged.
New York City’s tax base is not diversified the way Los Angeles’ or Houston’s is. A meaningful share of the city’s income tax comes from a strikingly small number of high earners, most of them in finance.
A budget cycle in which Wall Street has a bad year is a budget cycle in which the city has a bad year, full stop.
What New York actually needs from its mayor, in this environment, is not a retreat from progressive ambition. It is the recognition that the city needs to compete for its tax base in a global market.
Singapore will not punish the city for raising its top rate; it will simply absorb the families who decide, quietly, over a year of dinner conversations, that the next stage of their life will happen elsewhere.
London will not retaliate; it will reopen the doors it half-closed during Brexit. Dubai will not pick a fight; it will keep building the regulatory perimeter inside which capital feels welcomed rather than tolerated.
Home-ground advantage
New York’s advantages remain real, and they are not the kind any rival can copy in a decade.
The depth of capital markets, the density of legal and accounting talent, the network effects of having every counterparty within 10 blocks – these are agglomeration assets accumulated over a century.
They are not, however, indestructible. They erode the way Detroit’s auto base eroded: slowly, then suddenly, and always with the people in charge insisting the fundamentals were sound.
The mayor’s job, in plain terms, is to make sure that the price the city extracts from finance is one that the sector is willing to pay to stay.
That is not a question of ideology. It is a question of where the next office is opened, the next fund is domiciled, and the next generation of capital allocators decides to raise its children.
For most of the post-war era, the answer to all three was a foregone conclusion. It is not any more, and that is the part of the new political reality that has to be governed for, whatever one thinks of the politics that produced it.
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing
DBS tops trades in smaller board lots on debut of revised SGX framework

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Retrenched PMETs who return on lower pay see median 25% wage cut

