

Before life-cycle portfolios: A primer on how CPF really works
The Retirement Scheme is structured around three life phases, with the aim of achieving three objectives
IN THE past month since Finance Minister Lawrence Wong announced the launch of life-cycle funds for the Central Provident Fund (CPF) in 2028, there has been considerable discussion about what such portfolios are and whether CPF members should participate when the scheme is introduced.
In this article, I hope to provide clarity on the portfolios, but more importantly, to explain them within the broader context of Singapore’s CPF Retirement Scheme and how CPF helps Singaporeans plan for retirement.
Many people do not realise that the CPF Retirement Scheme works almost like a framework built around sets of three – in three life phases to achieve three objectives.
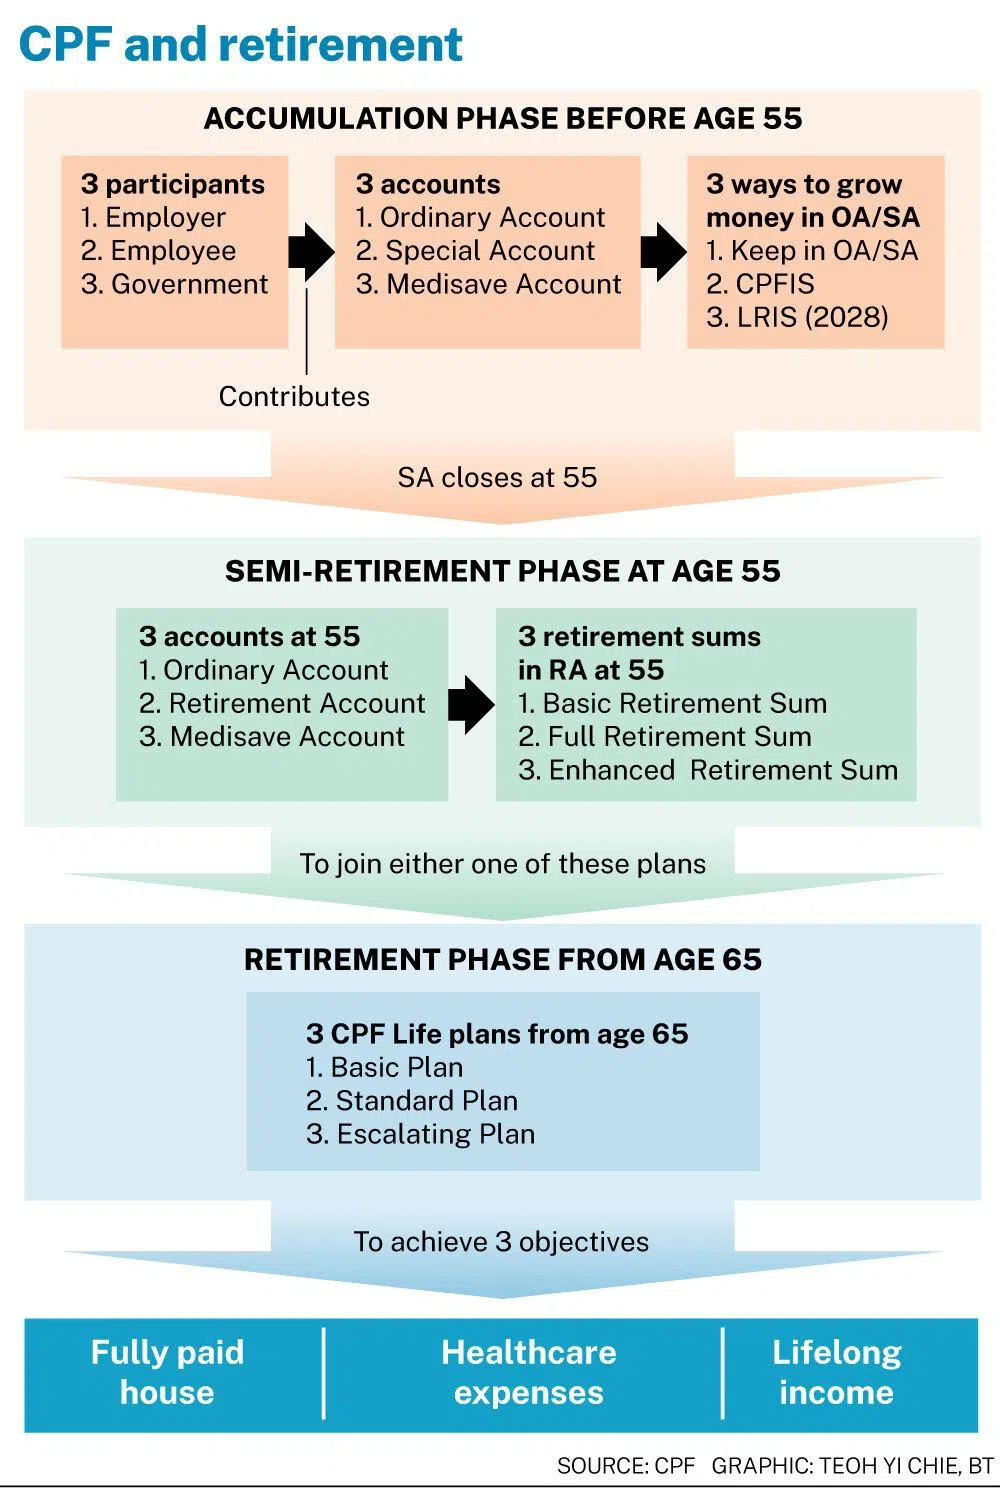
Life phase 1: Accumulation
In the accumulation phase, three participants contribute to CPF: the employer, employee and the government, which contributes indirectly through the interest paid on CPF balances.
These contributions flow into three accounts: the Ordinary Account (OA), Special Account (SA) and MediSave Account (MA).
Each account serves a distinct purpose. The OA primarily helps Singaporeans pay for their housing mortgage so that they can eventually own a fully paid home. The excess after paying mortgage can form part of their retirement fund later.
The SA is meant to accumulate funds for retirement. The MA helps to pay for healthcare expenses and insurance premiums such as MediShield Life, Integrated Shield Plans, ElderShield and CareShield Life.
For monies in the OA and SA, there are currently two ways to grow retirement savings. Members can simply leave their money in CPF and earn relatively high, near risk-free interest.
Alternatively, they can invest through the CPF Investment Scheme (CPFIS). From 2028, a new option will be introduced: life-cycle portfolios.
Life phase 2: Semi-retirement
At age 55, CPF enters the next phase. Monies in the SA, up to the prevailing Full Retirement Sum (FRS), are transferred into a newly created Retirement Account (RA). Any excess in the SA is transferred to the OA and the SA is then closed. At this point, members effectively have three accounts again.
The OA becomes relatively liquid. This gives members some flexibility and can support a gradual slowdown in work, which many may see as a semi-retirement phase.
The RA holds the retirement sum and continues to grow until the member eventually joins CPF Life, typically from age 65. The MediSave Account continues its role of supporting healthcare expenses and insurance premiums.
The retirement sum in the RA can be set at different levels: the Basic Retirement Sum (BRS), Full Retirement Sum (FRS), Enhanced Retirement Sum (ERS), or any amount in between.
Life phase 3: Retirement
From age 65 and up to age 70, CPF members join CPF Life, Singapore’s national annuity scheme. Members can choose among three CPF Life plans: Basic, Standard or Escalating. CPF Life then provides income for as long as the member lives.
This marks the third life phase: retirement.
Across these three life phases, the CPF system helps Singaporeans achieve three critical outcomes in life: a fully paid home, providing shelter and stability; healthcare protection, supported by insurance and MediSave; and a lifelong income stream in retirement.
Life-cycle portfolios
The CPF Advisory Panel of 2014 to 2016, of which I was a member, recommended the Lifetime Retirement Investment Scheme (LRIS), which was expected to adopt a life-cycle investment approach.
At that time, the panel observed that many CPF members did not have a good investment experience when investing through the CPFIS because they lacked sufficient investment knowledge and experience, and also faced high investment costs.
The purpose of the LRIS is to simplify investment and lower costs so that CPF members can grow their retirement savings more effectively in their accumulation phase. This has come to fruition in the life-cycle portfolios announced in the Budget. How the portfolios will be labelled is still to be decided.
In a life-cycle investment approach, younger members take on more equity exposure, and the portfolio is automatically rebalanced to become more conservative as retirement approaches.
This may appear straightforward, but implementing it is not necessarily easy.
Life-cycle funds assume that younger investors can take more risk because they have more time to recover from market volatility. This may be true in terms of ability to take risk, but it assumes that younger investors also have the willingness to take risk.
In reality, willingness to take risk depends on factors such as investment literacy, past investment experience and personal life events that shape how comfortable someone feels with volatility. Risk tolerance is far more complex than simply age.
Who should consider CPFIS’ life-cycle portfolios?
For affluent individuals, life-cycle portfolios may not necessarily be the most optimal approach. When we design portfolios for clients, we look at their wealth holistically.
CPF is simply one bucket of assets. It is also a bucket that provides relatively high, stable and low-risk returns. It may therefore make sense for many affluent investors to leave CPF untouched, while taking investment risk using other pools of capital.
For the public at large, life-cycle portfolios in the CPF can be useful. But it is important to understand that your CPF money will be invested in financial markets and privately managed. There is no government guarantee on returns and capital. Before investing, it is important to be educated.
And for those who dislike volatility, there is nothing wrong with not investing your CPF savings.
If you manage your CPF well, you may not accumulate as much as someone who invests successfully. But you will still have something very valuable: a fully paid home, healthcare protection and an income that lasts as long as you live.
When you reach the retirement phase of your life, those three things may matter far more than whether your portfolio beats the market.
The writer is chief executive officer, Providend, South-east Asia’s first fee-only, comprehensive wealth advisory firm
TRENDING NOW

Britain’s mansion tax shows the difficulty of targeting wealth

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

The only common thing in S-E Asia is that we all eat rice: Cisco’s Asean president
Singapore data centre operator DayOne opts for US IPO at likely US$20 billion valuation

