

The US is a rich man borrowing against his assets
Debt crisis predictions fail as a wealthy sovereign that borrows in its own currency doesn’t fail on a schedule
AMERICA’S national debt crossed US$40 trillion in August. Interest on that debt now costs more than the country’s entire defence budget.
The 30-year Treasury yield touched 5.34 per cent on Aug 18 – its highest level since 2007 – and the curve has steepened as the front end remains anchored.
If you add the uncertainty and tension between a US Federal Reserve biased towards hiking rather than cutting, oil that refuses to fall, core inflation stuck at more than 3 per cent, and a “new” America that treats allies as adversaries, you get this year’s most popular story: The US has finally borrowed too much, and its currency will pay for it.
It is a compelling story. It is also mostly wrong. Here is why.
The dollar refuses to collapse
Currency seems to be where anxiety is the loudest, but it should not be. The US dollar index sits at around 99 today. It traded above 109 in January 2025, fell hard through the spring of that year, and then did something the doomsayers did not expect – nothing.
It has been range-bound for roughly 17 months. I have showed this chart at the Endowus Wealth Summit for two years running; the reaction is always disbelief, because the narrative has run so far ahead of the actual, underwhelming moves.
My former colleague Stephen Jen coined the term “dollar smile”. The US dollar strengthens in two extreme scenarios: when strong growth triggers inflation and higher rates, or when a crisis or geopolitical shock sends investors to it as a safe haven.
In a normal environment, the greenback tends to weaken against a basket of currencies including the euro, yen or Asian and emerging-market currencies.
For a Singapore-based investor, this matters in a specific way. The Monetary Authority of Singapore has guided our currency along a gradual appreciation path for decades against almost every currency, not just the US dollar.
That is a story about Singapore’s own strength, not the US or its currency’s weakness. I expect this structural trend to continue – a reason to think about hedging your non-Singdollar exposure, but not a reason to believe that the US dollar is dying.
Textbook finance says that a country paying 3.5 to 3.75 per cent, with a central bank more likely to hike than cut, should have a strengthening currency.
The fact that the US dollar is flat rather than surging shows that the market is charging only a modest risk premium for fiscal and institutional uncertainty.
Debt a balance sheet issue, not income
Almost every alarming chart you have seen compares government debt to gross domestic product. But GDP is income.
Debt-to-income ratio tells you about the ability to service debt, and on that measure, the US is uncomfortable but not in crisis. Net interest is around 3 per cent of GDP, a level last seen in the early 1990s, when nobody was writing the US dollar’s obituary.
To judge whether the absolute level of debt is dangerous, a lender looks at collateral, not income. For example, a private banking client with S$50 million worth of investments and property who borrows S$10 million against them is not a credit risk.
Look at the US the same way. The Fed’s financial accounts, the closest thing to a national balance sheet, show total US non-financial debt of about US$81 trillion at the end of 2025: roughly US$34 trillion federal, US$21 trillion household and US$22 trillion business.
Against that, US households alone hold US$184 trillion of net worth. Household debt relative to disposable income is near its lowest level since the late 1990s, and corporate America’s current capital-investment boom is being funded largely from free cash flow, not debt.
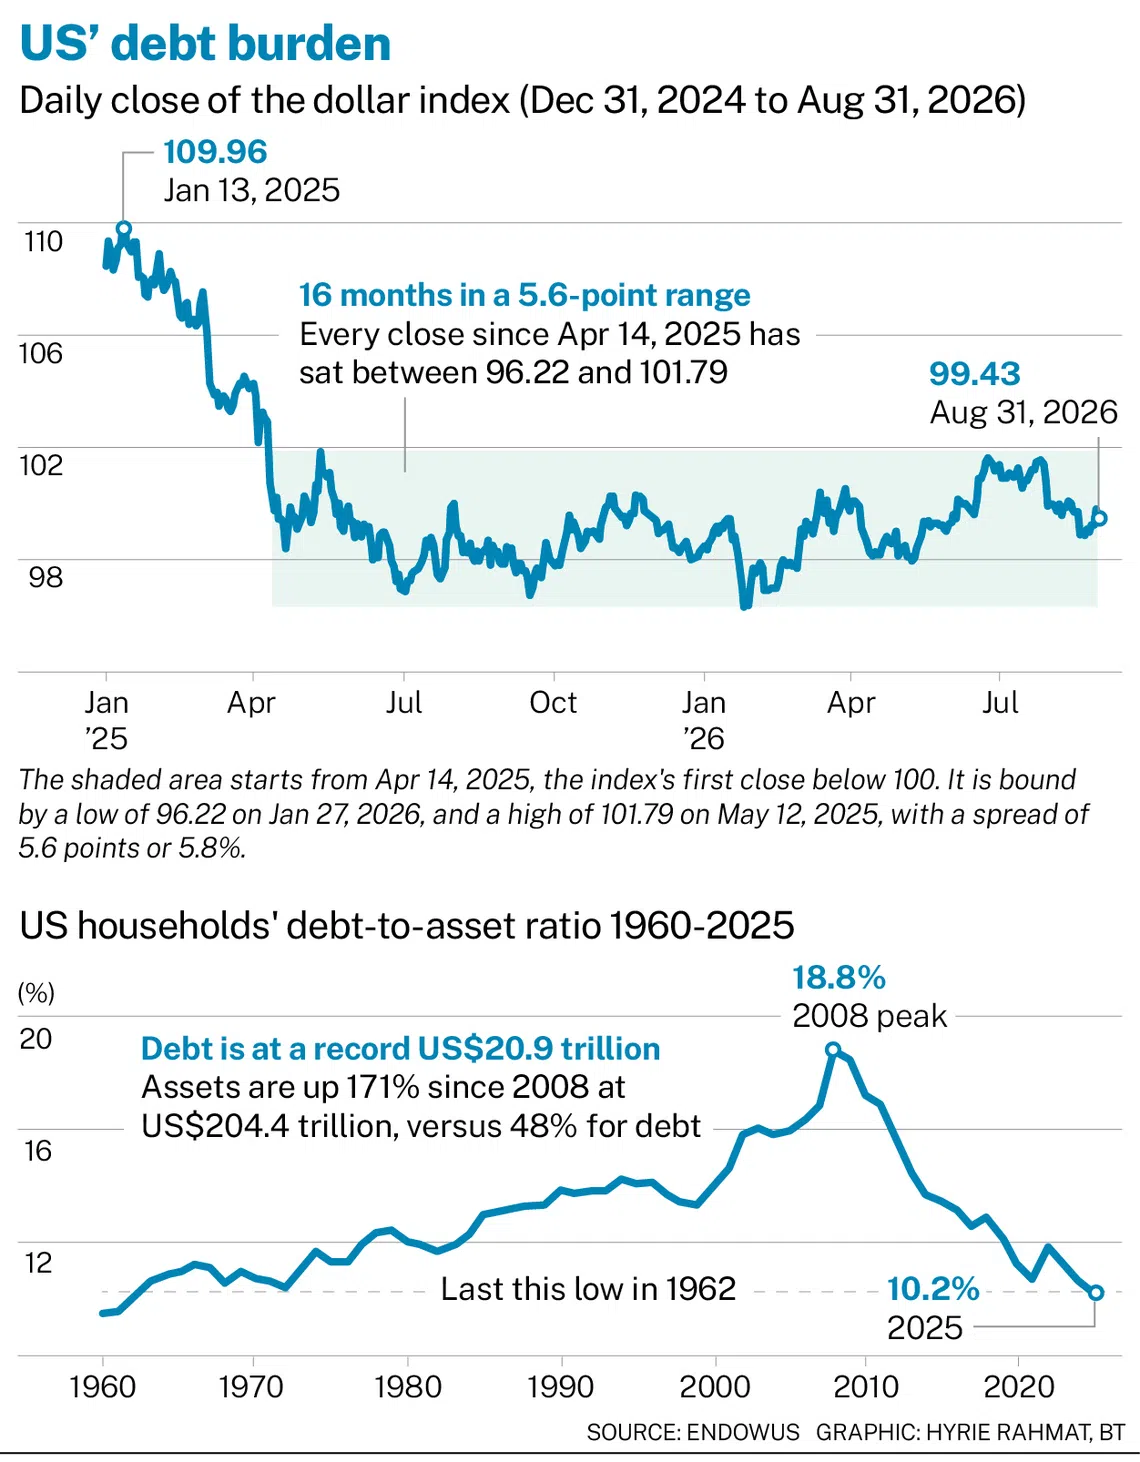
In other words, the debt problem sits on the government balance sheet inside a very rich country.
That is a governance and political problem, not a solvency one, which is why Treasuries remain the deepest and most liquid market on Earth. This is despite the fact that foreign government holders are diversifying by rotating from long bonds into bills, other government bonds and gold.
In fact, this is one of the loudest claims out there, that foreign claims on US assets, especially Treasuries, are dangerously high. What if everybody pulls their money? But why would they? What incentive is there for the US economy to collapse or the government to stall?
The largest global economy and the largest financial market falling would hurt growth, financial returns and financial stability for the rest of the world. It is a risk not even China would be willing to take.
China, once the largest holder of US Treasuries, held US$1.32 trillion at its peak in November 2013. Its holdings have since more than halved to US$633.4 billion as at June 2026.
If you look at broader trends, 14 of the top 20 countries holding US Treasuries actually increased their ownership in the past year versus six that reduced them. The total amount held by foreign nationals increased by US$205 billion to US$9.3 trillion. The foreign-selling narrative is overblown.
Something has to give? What the evidence says
Every sophisticated investor I speak to says the same thing: With both ends of the curve under pressure, something has to give. They may be right.
But behavioural finance has a name for what happens next. Predictions regarding the American debt crisis have been made continuously, since the debt was US$50 billion in the 1940s.
Each time the number got bigger, warnings got louder. Each time the prediction failed, because a sovereign that borrows in its own currency, backed by the world’s largest pool of wealth, does not fail on a schedule.
Recency bias makes us extrapolate a weak spring for the US dollar into a decade of decline. Availability bias makes the US$40 trillion headline feel like a cliff edge rather than an important marker on a very long trajectory.
Three decades of investing have taught me that the most expensive mistake is not being wrong about a forecast; it is repositioning an entire portfolio around one. Investors who dumped US dollar assets in April 2025 missed a 40 per cent rally in US equities.
Much ado about nothing?
There is a case for hedging back to Singapore dollars, although the interest rate differential makes it costly, especially as the duration extends beyond just six to 12 months.
You should still keep your equity exposure global and have Singapore in the mix, while including the American companies whose earnings are the reason the US is still a valuable asset and why the greenback has not collapsed.
Treat gold and alternative currencies as diversifiers, not as a verdict on America, political or economic. And if tempted to make a big directional call on the US dollar, remember that you would be betting against the most liquid, most efficient market in the world.
A good fiduciary adviser does not tell you where the greenback is going. It helps to size your exposures so that you do not need to know where it is headed.
The US is not a household drowning in credit-card debt. It is a rich man borrowing against his assets. The question for the lender was never how much they owe. It was always what they own.
The writer is co-founder and group chief investment officer, Endowus
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check

