CICT’s Q3 NPI rises 13.8% to S$334.9 million on contributions from Paragon and other acquisitions
For the nine-month period, the real estate investment trust’s NPI grows 10.4% on the year to S$965.4 million
[SINGAPORE] The manager of CapitaLand Integrated Commercial Trust ( CICT ) on Thursday (Oct 29) posted a 13.8 per cent increase in net property income (NPI) to S$334.9 million for the third quarter ended September.
Revenue for Q3 rose 15 per cent year on year to S$464.5 million.
For the nine-month period, the NPI for the real estate investment trust (Reit) grew 10.4 per cent on the year to S$965.4 million, and revenue rose 10 per cent to S$1.3 billion.
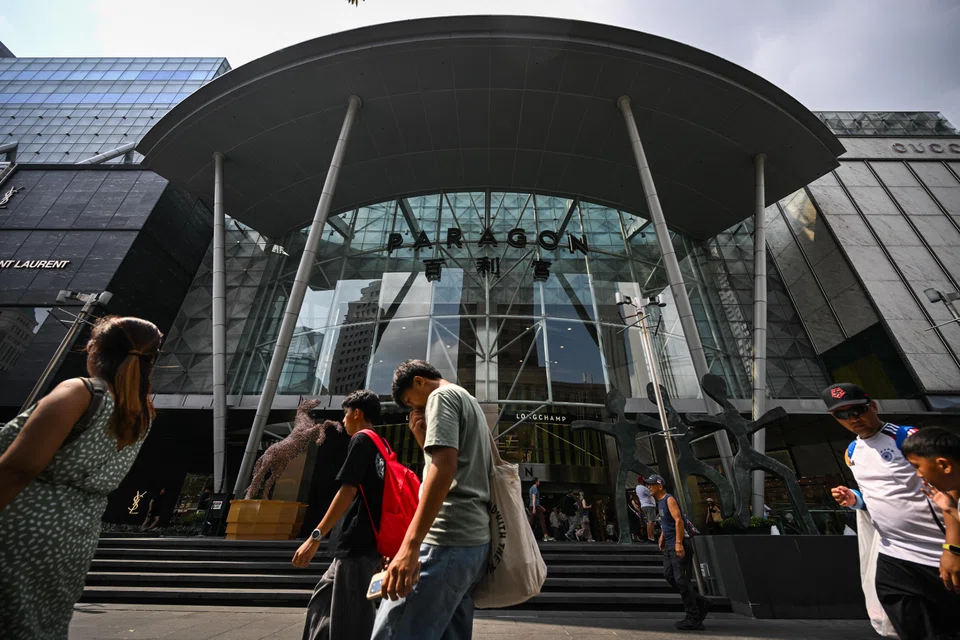
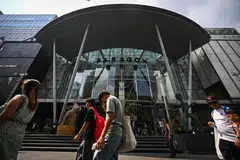
The increase was largely driven by contributions from Paragon, which the Reit acquired in July 2026; Gallileo, its commercial property in Germany, following asset enhancement works; and its increased stake in CapitaSpring.
CICT bought over the 55 per cent interest in the office and retail component of CapitaSpring that it did not already own for S$1 billion.
The increase was partially offset by the divestments of Bukit Panjang Plaza and Asia Square Tower 2, said the manager in its Q3 business update. The Reit completed the divestment of Asia Square Tower 2 on Sep 17, generating net sales proceeds of about S$2.45 billion.
DBS Group Research said in a note on Thursday that CICT remains one of its top picks among the Singapore Reits, given that it is a large cap offering about 4 per cent growth and an attractive yield of 5.3 per cent.
Revenue and NPI for the nine-month period are “tracking well” at 75 per cent of the brokerage’s full-year estimates, supported by resilient operating fundamentals.
CICT’s aggregate leverage stood at 39.7 per cent as at end-September, up from 37.4 per cent as at end-June, while portfolio weighted average lease to expiry was 3.1 years.
SEE ALSO
The Reit’s total borrowings stood at S$11.1 billion, up from S$9.9 billion as at end-June. Its average cost of debt inched down 0.1 percentage point to 2.8 per cent.
Given its robust NPI growth and lower borrowing costs, Jefferies analysts Wilson Ng and Geraldine Wong expect that CICT is on track to meet its full-year distribution per unit growth forecast of 4 per cent.
Committed occupancy rose to 96.1 per cent as at end-September, from 95.6 per cent as at end-June. Its retail occupancy rate remained largely stable at 97.3 per cent as at Sep 30, with suburban and downtown malls recording occupancy rates of 99.1 per cent and 96 per cent, respectively.
For the year to date, CICT recorded positive rent reversions of 7.1 per cent for its office portfolio and 4.6 per cent for its retail portfolio.
The manager expects mid-single-digit reversions for both its office and retail portfolios till 2027, which Jefferies’ Ng and Wong believe is “conservative”. They had a “buy” call on the counter with a target price of S$2.27.
Within the retail portfolio, suburban malls recorded rent reversion of 4.6 per cent, while downtown malls registered 4.5 per cent.
Revenue from its retail portfolio declined to S$143.5 million for Q3 from S$151.7 million in the year-ago period, while NPI fell to S$99.6 million from S$108.5 million. For the nine-month period, revenue dropped to S$435.3 million and NPI fell to S$310.2 million.
The decline came despite healthy tenant sales across the portfolio, which was driven by seasonal promotions and new store openings, such as Italian restaurant Osteria Mozza at Ion Orchard and frozen yogurt shop Yochi at Westgate.
Excluding Paragon, tenant sales grew 2 per cent for the nine-month period.
Asset enhancement works are progressing across its portfolio, including Lot One Shoppers’ Mall, which is slated for completion in the first quarter of 2027; the works on Plaza Singapura and The Atrium@Orchard are expected to be completed in the fourth quarter of 2028.
At Tampines Mall, CICT completed its asset enhancement works in Q3 2026, with about 97 per cent of the revamped space either committed or in advanced negotiations. The revamp, which cost about S$24 million, has introduced 16 new brands to the mall, including Sephora and Goldheart. The manager expects a return on investment of about 7 per cent.
DBS Group Research said it sees opportunities for incremental rental uplift as these projects are progressively completed. It maintained its “buy” call on the counter, with a target price of S$2.55, implying a 4.7 per cent target yield.
Meanwhile, construction works for the commercial component of the Hougang Central development is expected to start in 2027, with completion targeted for 2030 or 2031. The project has an estimated development cost of S$1.1 billion.
Units of CICT were trading 1.3 per cent or S$0.03 higher at S$2.29 as at 3.41 pm.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.