Positive rental reversions support S-Reits’ recent resilience
But distributions remain mixed, due to portfolio occupancy, currency fluctuations and financing costs
[SINGAPORE] As at Thursday (Nov 5), most real estate investment trusts in Singapore (S-Reits) have released their financial results or business updates for the period ended Sep 30.
While positive rental reversions emerged as a dominant theme across the sector, distributions remained mixed as portfolio occupancy, currency fluctuations and prevailing financing costs influenced distribution per unit (DPU) performance.
The top five most-traded S-Reits in the year to date all reported positive rental reversions. They are: CapitaLand Integrated Commercial Trust (CICT), CapitaLand Ascendas Reit (Clar), Keppel DC Reit , Mapletree Logistics Trust (MLT) and Mapletree Pan Asia Commercial Trust (MPACT).
Among these, CICT, Keppel DC Reit and MLT recorded increases in net property income (NPI) and/or DPU.
In its third-quarter business update, CICT said its NPI for the first nine months of 2026 rose 10.4 per cent year on year to S$965.4 million.
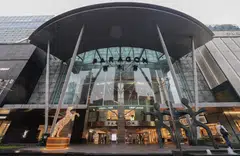
This was due largely to contributions from Paragon, Gallileo and CapitaSpring’s step-up acquisition, and partially offset by the divestments of Bukit Panjang Plaza and Asia Square Tower 2.

Rental reversions for its retail and office portfolios stood at 4.6 per cent and 7.1 per cent, respectively.
Clar recorded a positive rental reversion of 9 per cent for leases renewed in 9M. Stable leasing activity sustained a high portfolio occupancy rate of 90.1 per cent, with the Singapore properties tracking above the industrial average.
During the period, Clar completed close to S$1.8 billion in accretive acquisitions. As part of its ongoing portfolio rejuvenation strategy, it also divested three Singapore properties for S$281.7 million, representing a 25 per cent premium to independent market valuations.
These divestments are projected to raise its portfolio occupancy to 91.5 per cent on a pro forma basis.
Keppel DC Reit reported one of the highest rental reversions in the sector at 14 per cent for secured leases (excluding renewals yet to commence). This was accompanied by strong growth in distributable income and DPU, which rose 16.7 per cent and 11.7 per cent, respectively, on the year.
The manager attributed growth to stronger operations, acquisitions and increased effective interests in Keppel DC Singapore 3 and 4. These were partly offset by acquisition-related finance costs and more units in issue.
MLT maintained a positive average rental reversion of 2.1 per cent (4.2 per cent excluding its China portfolio) for Q2 FY2027. Its Singapore leases recorded a 5.3 per cent increase, while its China portfolio posted a 1.7 per cent decline.
Revenue and NPI grew year on year by 1.4 per cent and 1 per cent, respectively, driven by contributions from its Singapore redevelopment project and India acquisition, as well as organic growth from the existing portfolio. These were partially offset by divestments.
MPACT secured a positive rental reversion of 3.5 per cent for leases expiring in FY2027, with positive rental reversions in Singapore tempered by negative rental reversions in Hong Kong and China.
Its first-half FY2027 NPI decreased by 6.5 per cent, weighed down by softer overseas contributions, the absence of contributions from divested properties, and a stronger Singapore currency against the yen and Hong Kong dollar.
Aside from the five most-traded S-Reits, the three strongest-performing S-Reits in October were Acrophyte Hospitality Trust (Acro-HT), Frasers Centrepoint Trust (FCT) and Suntec Reit .
Acro-HT recorded a stronger Q3, with same-store NPI rising 6.6 per cent year on year. This was supported by a solid average daily rate, occupancy growth and continued cost discipline.
However, for 9M 2026, same-store NPI edged down 1.5 per cent due to the loss of contributions from divested hotels, as well as higher utility and insurance costs amid elevated energy prices and rising interest rates.
FCT posted a DPU of S$0.1235 for FY2026 – a new high – underpinned by a robust operating performance. NPI grew 15.7 per cent on the acquisition of Northpoint City South Wing and higher passing rents across most malls.
Retail portfolio committed occupancy, excluding Nex and White Sands, was 99.7 per cent as at Sep 30. Meanwhile, retail portfolio rental reversion – excluding Nex, Hougang Mall and White Sands – was 6.6 per cent.
The manager of FCT anticipates continued resilience in Singapore’s suburban retail market, with targeted asset enhancement initiatives at Hougang Mall, Nex and Causeway Point expected to support further growth.
Suntec Reit reported a 13.4 per cent year-on-year increase in its DPU to S$0.02017, attributable to a stronger operational performance across its Singapore office and retail portfolios as well as lower financing costs.
Among its Singapore assets, the Reit recorded rental reversions of 7.3 per cent for the office portfolio and 11.2 per cent for the retail portfolio in Q3.
UOB Kay Hian Research noted in October that S-Reits remain defensive and resilient, supported by firm asset valuation and continued low cost of debt. It maintained its "buy” calls on both CICT and MPACT.
DBS Group Research said rental growth and asset-management initiatives remain important drivers of DPU expansion, with such growth expected to remain intact at a forecast compound annual growth rate of about 3 per cent for FY2026 to FY2028. SGX RESEARCH
The writer is director of capital market development at SGX.
For more research and information on Singapore’s Reit sector, visit sgx.com/research-education/sectors for the S-Reits & Property Trusts Chartbook.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services