

Issue 211: Singapore defers green jet fuel levy for cargo; TUV SUD opens decarbonisation centre
This week in ESG: One-year delay for fuel charge to give air cargo industry time to prepare; S$30 million decarbonisation centre to address trust in carbon markets
Energy transition
Sustainable aviation fuel needs a reality check
Singapore’s decision to delay a green jet fuel levy for air cargo is the latest challenge confronting efforts to decarbonise the aviation sector.
The sector is veering further in the wrong direction with regards to sustainable aviation fuel, and it seems increasingly likely that the industry will have to adopt more realistic targets or accept widespread non-compliance. If that happens, investors in the sector may face higher-for-longer emissions in their portfolios as well as greater uncertainty about climate transition risks.
The Civil Aviation Authority of Singapore (CAAS) has announced that a planned sustainable aviation fuel (SAF) levy for air cargo will be deferred for one year, such that it will now apply to services sold from Oct 1, 2027 for flights that depart Singapore from Jan 1, 2028. The exact levy amounts are based on the prevailing price premiums of SAF over fossil-based jet fuel and route distances.
This is the second levy deferment for air cargo, after the aviation regulator’s March 2026 announcement of a six-month delay on the original plan to impose the levy for all passenger and cargo flights sold from April 2026 for flights departing Singapore starting Oct 1, 2026. There is no second deferment for passenger flights, which will begin to include the levy starting Oct 1 for flights departing Jan 1, 2027 onwards.
CAAS says that, compared to passenger operations, air cargo operations are more diverse and involve a wider spectrum of stakeholders. The delay takes into account industry feedback that it needs more time to work with CAAS to develop and implement a robust SAF levy collecting mechanism for cargo flights. Singapore has estimated that cargo SAF levies could be around S$0.01 to S$0.15 per kilogramme of cargo, depending on the length of the route.
CAAS granted the original March deferment as a response to disruptions arising from the Iran war.
The SAF levy is a critical piece in Singapore’s strategy for greening its aviation sector, with a goal of achieving a one per cent SAF uplift in 2026 en route to a 3-to-5 per cent uplift by 2030, subject to global developments and SAF availability. The levy collections will be channelled to a statutory SAF fund that will act as a central buyer of SAF for flights departing from Singapore. The policy thesis is that a consolidated central buyer can obtain better prices for plane operators, as well as provide a clearer demand signal for SAF producers.
It is clear that the 2026 uplift target will not be achieved. The 2030 goal could still be in play, but the delays mean that Singapore will have to raise the pace of uplift more rapidly than initially hoped, which might face resistance from plane operators going through the country.
All this attention to SAF has its roots in global efforts to decarbonise aviation, which contributes about 2 to 3 per cent of global greenhouse gas emissions. SAF is a key pillar in the International Civil Aviation Organization’s (ICAO) target of net zero greenhouse emissions for international aviation – which contributes about 1.5 per cent of global emissions – by 2050.
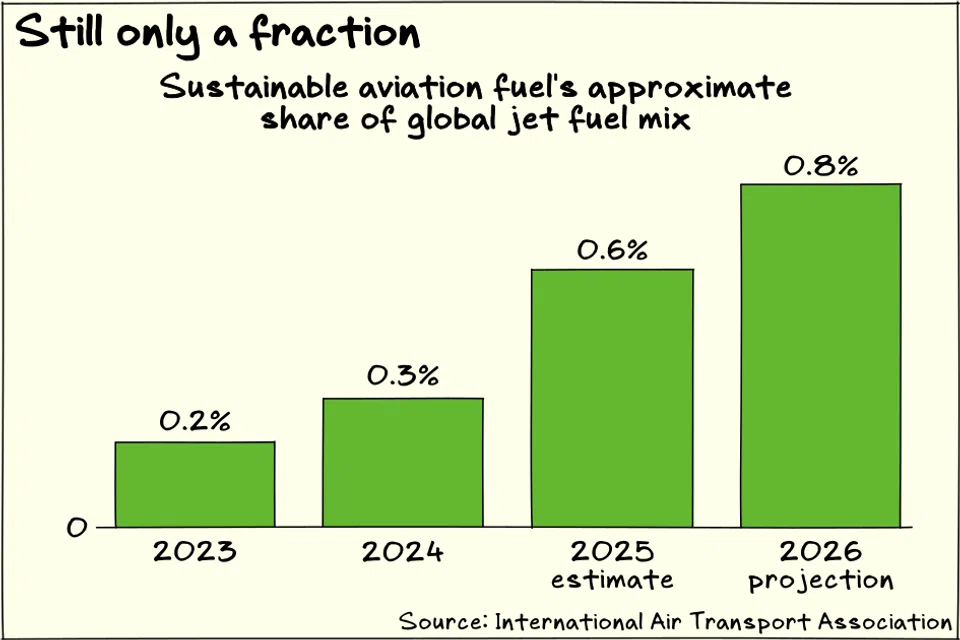
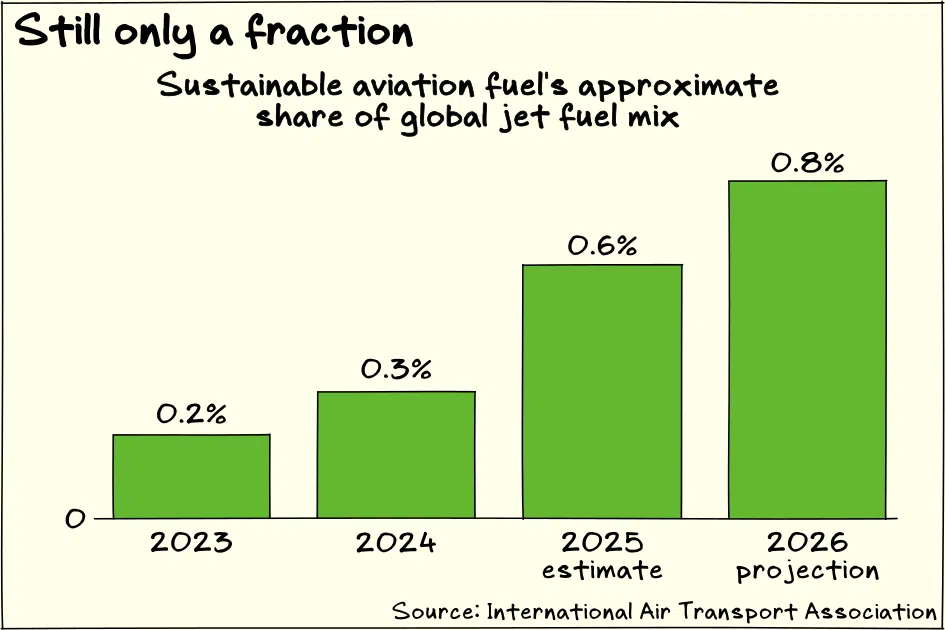
In support of that goal, the industry’s International Air Transport Association (Iata) has set a target of raising SAF to 65 per cent of the fuel mix by 2050. However, Iata’s latest estimate is that global SAF production will represent only about 0.8 per cent – or 2.4 million tonnes – of total fuel use in 2026 despite having five years to try to raise the percentage since the targets were adopted. Furthermore, SAF is still about two to five times as expensive as fossil jet fuel.
Iata director general William Walsh says: “The path to meeting 65 per cent of our needs in 2050 is growing more difficult with each year of ineffectively sequenced government policies and oil companies’ manifest lack of interest. The current energy shock should add even more urgency to the development of renewables, including SAF. But we have yet to see either the energy shock, the need to develop energy independence and jobs, or the urgency to mitigate climate change materialise in the incentives needed to create a viable SAF market.”
Iata also takes issue with attempts in Europe to mandate production of electro-SAF (e-SAF), which refers to SAF produced using renewable electricity, water and captured carbon dioxide instead of biomass. Production mandates in the European Union and United Kingdom are “utterly detached from reality” because they require supply to balloon without supporting that level of growth, says Marie Owens Thomsen, Iata’s chief economist and senior vice-president of sustainability.
But even if policymakers pull the right levers – and even if Singapore’s levy-and-centralised procurement strategy proves effective in helping to propel production while keeping SAF prices viable – there remains a question of whether it makes sense to bank so much of aviation’s decarbonisation on SAF.
A 2025 academic paper by French researchers Paul Bardon and Olivier Massol argues that aviation decarbonisation cannot rely on SAF at scale. The researchers observe that the aviation industry has never been able to meet its SAF goals. A 2008 target for 10 per cent SAF incorporation by 2017 was reduced in 2019 to 2 per cent by 2025, and progress towards the current goal remains elusive.
While Bardon and Massol acknowledge that better policies can help to drive more investments into SAF, they note limitations in the availability of biofeedstock. Allocating resources towards SAF production at the scale required to achieve net zero by 2050 will probably slow the decarbonisation of other sectors.
For example, using renewable energy to replace coal power, for electric vehicles or for heat pumps would be a more efficient way to decarbonise than producing e-SAF, the authors say, citing the British Climate Change Committee.
“In light of the unfairness and inefficiency of such a policy, this study argues that granting aviation priority over the industry-forecasted amounts of critical resources in 2050 is neither sensible nor fundamentally feasible,” the paper states.
The reality is that the aviation sector’s current decarbonisation goals do not appear to be realistic. To keep the goals credible, the industry will probably have to recalibrate. However, doing so will take the sector out of alignment with pathways for net zero by 2050.
This could create challenges for investors – especially institutional players – that have their own decarbonisation goals for their portfolios. For instance, Singapore’s Temasek has cited its stake in Singapore Airlines as a reason why it is likely to miss its 2030 target for portfolio emissions.
Being behind the decarbonisation curve also raises the risk of aviation players being on the wrong side of future climate-related policies. For example, an airline could face lower margins or lower ticket sales if policymakers tax their emissions more aggressively.
In fact, Bardon and Massol argue that policies “constraining the sector’s growth” are necessary to achieve net zero.
“Aviation can achieve decarbonisation only through a more sustainable air traffic growth associated with reasonable resource utilisation,” the authors write.
Carbon markets
TUV SUD bets on carbon market recovery
TUV SUD’s new decarbonisation centre in Singapore arrives at a pivotal time for carbon markets following a pullback over the past five years.
The S$30 million investment aims to help companies to measure and verify emissions and other carbon data, with a focus on serving the South-east Asian market. TUV SUD, a German testing and certification business, estimates that the cumulative carbon market opportunity in South-east Asia could be as high as US$3 trillion by 2050.
The new facility adds to a growing carbon ecosystem in Singapore, which has made sustainable finance a key pillar of its financial sector development strategy. In August, Singapore-based carbon exchange Climate Impact X announced a merger with UK-based carbon portfolio management firm Carbonplace.
These moves are ultimately bets that the carbon markets are gradually rebuilding after being hammered by integrity concerns over the past few years.
Some optimism appears justified. Data compiled by Ecosystem Marketplace shows voluntary carbon credit retirements holding roughly steady at 181.5 million tonnes of carbon dioxide equivalent in 2024, while prices of forestry-based carbon removal credits – classified as afforestation-reforestation and revegetation – increased in 2024 to an average of US$20.44 per credit.
Compliance markets are expected to drive growth on the demand side. A growing network of bilateral deals that are aligned with Article 6 of the Paris Agreement could unlock cross-border credit trading between countries. In the aviation sector, beginning in 2027 airlines will have to offset emissions that are in excess of a baseline.
Supply appears to be the major limiting factor at the moment. Issuance of Article 6 credits has been slow despite the growth of trading agreements. Demand is also picky, and focused on high-quality credits; however, issuance is only starting to ramp up for credits that meet stringent quality standards.
Reducing market friction could help to close some of the supply-and-demand gap, and that appears to be where the recent deals are aimed. TUV SUD’s centre addresses data friction, while the Climate Impact X-Carbonplace merger integrates several levels of the trading value chain into a one-stop shop.
Other ESG reads
- Sembcorp axes S$105 million deal to buy Philippine solar farm developer
- It’s not just Singapore that will benefit from the Asean Power Grid: philanthropy platform CEO
- Asean leaders should focus on energy transition, not US-China rivalry: Al Gore
- Haze in Singapore: PSI crosses 101 in central region as air quality enters unhealthy range
- Google, Cathay Pacific use AI to tackle aviation’s top climate headache
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Hwa Seng Builder, two China companies win S$1.2 billion Tuas Road Viaduct phase two contracts

Deal between tycoon friends sparks scrutiny of Philippine power sector

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

