

Is stagflation returning? That mostly depends on the Iran war
Oil prices, interest rates and a bond sell-off are raising alarm bells
EVEN though the possibility of stagflation gripping the global economy has yet to become the baseline consensus among policymakers and market watchers, a growing number of them are worried about it happening.
The International Monetary Fund’s managing director Kristalina Georgieva warned on Sep 24 that “winter is coming”, referring to the combination of high inflation and interest rates triggered by the Iran war and its effect on oil prices.
That caution is not new.
In April, Reserve Bank of Australia deputy governor Andrew Hauser said that this combination of economic malaise and persistent inflation is a “central banker’s nightmare”.
Likewise, Valdis Dombrovskis, European commissioner for the economy and productivity, warned in May of a significant “stagflationary shock” hitting the EU.
Stagflation brings about many challenges.
Money often gets misallocated to unproductive assets; higher unemployment reduces worker skill development and lowers asset accumulation for retirement.
Poor business confidence cuts capital expenditure, and reduces incentives for entrepreneurs to start new businesses.
It is hard to tackle stagflation because boosting demand, such as through fiscal stimulus, tends to worsen inflation, while reining in inflation with higher interest rates generally slows economic growth even further.
Stagflation, in other words, tends to resist traditional policy remedies, with neither fiscal nor monetary policy helping to kick-start economies.
To be sure, data does not yet indicate that stagflation currently grips the world economy.
In the US, the unemployment rate in August was 4.1 per cent, staying roughly steady since 2024.
Real gross domestic product has also not registered a negative quarter since early 2025.
And many financial market participants are still heavily invested in the narrative of an unprecedented boom in capital expenditure for artificial intelligence technologies, which is fuelling a global stock-market surge.
Iran war the main factor
But more economic red lights are flashing.
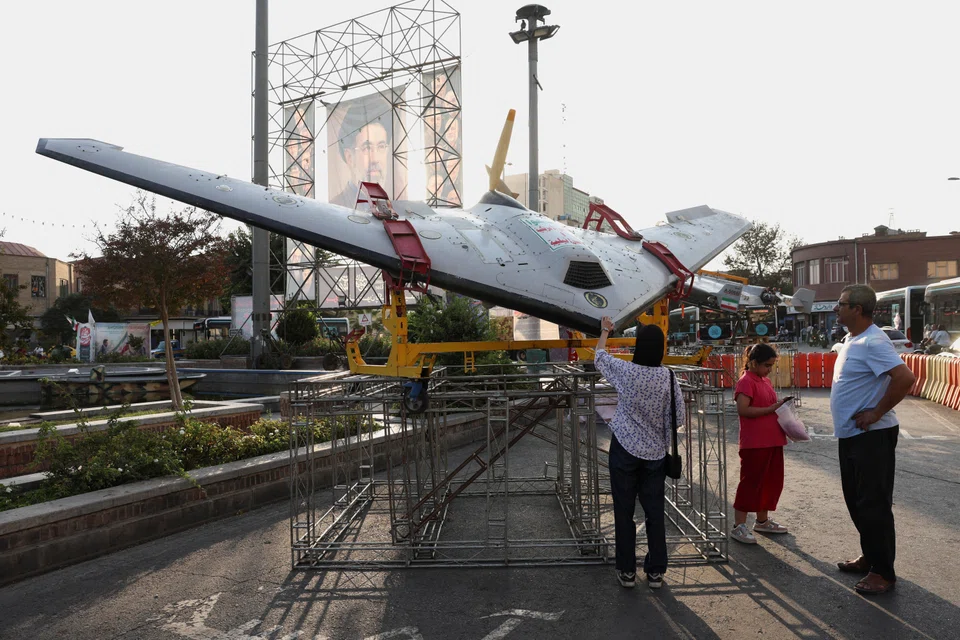
First, even though the US and Iran are reportedly exploring a deal to reopen the Strait of Hormuz, there is still a lack of optimism that there will be any sustainable breakthrough in the crisis before November’s US midterm elections, at least.
Not only are there continued shipping challenges in the Strait of Hormuz and Bab el-Mandeb, but lower Saudi Arabian oil output has also exacerbated what the International Energy Agency in March called the greatest-ever shock to the global energy sector.
Second, major central banks, such as the US Federal Reserve and European Central Bank (ECB), have recently raised interest rates.
Their hawkish commentary has caused traders to anticipate at least two more increases by the Fed, and several more from the ECB, by the end of the year.
Finally, investors are growing nervous about the indebtedness and future fiscal plans of an increasing number of governments, which has triggered a global bond sell-off and increased bond yields.
The most influential factor out of the three in determining whether a new period of stagflation dawns on the world is probably the Iran crisis.
Specifically, the possibility of a global recession depends on how long the war lasts, how much damage is done and how high energy prices rise.
As at Sep 25, online prediction market Polymarket showed just a one in four possibility that Hormuz would be reopened by the end of 2026 – plunging from nearly 90 per cent in June.
Meanwhile, Oxford Economics warned that if global oil prices average around US$140 per barrel for some two months, it would be enough to push parts of the global economy into a mild recession.
The market is not yet predicting that oil will cross this US$140 threshold.
However, forecasters such as HSBC and Goldman Sachs believe that the price of Brent crude could rise above US$120 in the coming months.
This is based on the fact that Gulf production currently remains significantly below pre-war levels, and countries’ strategic inventories are still near operational lows. Maritime transport could also be disrupted through 2027.
Crude prices, hence, may only ease in response to weaker demand and greater non-Opec supplies coming on tap.
While it is still too early to know if stagflation will take hold of the world economy, there are growing warning signs that this long-ago phenomenon – that some younger market participants have not experienced before, and others may have forgotten – will emerge again.
The writer is an associate at LSE IDEAS at the London School of Economics
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet
TRX and Labuan IBFC join forces to boost Malaysia’s regional financial ambitions

Crystal Jade Fine Dining faces charge for failing to file income tax return on time

