


Why are some central banks raising rates and others holding them?
The reasons behind their decisions reveal much about the state of the world economy
IN 2025, financial markets expected the world’s major central banks to be moving towards lower interest rates. Today, a better question may be: Who is not raising them, and why?
First, some major banks have tightened policy: The European Central Bank (ECB) raised rates on Sep 10; the US Federal Reserve followed on Sep 16, lifting rates for the first time in three years; and the Bank of Japan (BOJ) hiked its policy rate to 1.25 per cent, its highest in 31 years, on Friday (Sep 18).
As for the others: the Bank of England (BOE) and Reserve Bank of India (RBI) held rates, and China is expected to stand still.
But, while it is easy to separate the various central banks into two groups – those who hike and those who stand pat – the reasons behind their decisions are very different. And those differences reveal the divergences in the world economy.
A question of supply and demand
The US illustrates one side of the divide. The Fed said that economic activity was expanding at a solid pace, domestic spending remained resilient, productivity growth was strong and capital investment was robust.
But inflation remains elevated. The extraordinary investment associated with artificial intelligence adds another source of demand. The Fed therefore wants a “timelier return” to its 2 per cent inflation goal.
Japan is more unusual. Its economy is hardly booming, yet the BOJ has shifted from trying to push inflation up to preventing it from overshooting.
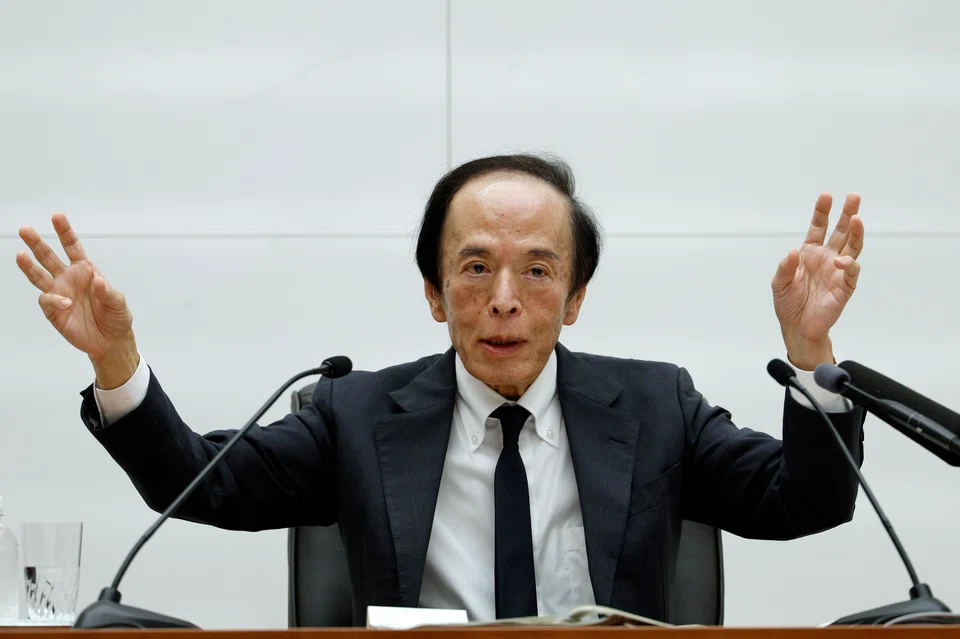
Governor Kazuo Ueda said that underlying inflation was now close to 2 per cent, wage pressures were broadening, and higher energy costs could spread from wholesale to consumer prices.
His conclusion is striking: The BOJ should act pre-emptively so that it is not later forced into much sharper rate increases. “Our policy phase has changed,” he said.
Yet, the yen weakened sharply after the decision, suggesting that markets remain uncertain whether Japan’s gradual tightening will be sufficient to offset inflation and exchange-rate pressures.
Japan demonstrates why “who is raising?” cannot simply be answered by looking at growth.
Ueda linked the simultaneous moves by the Fed, ECB and BOJ to common pressures from the Middle East energy shock and strong AI expenditure.
All of these are supply shocks, which can require monetary tightening if they begin feeding into wages, prices and inflation expectations.
Then consider those not raising.
The BOE on Sep 17 held its rate at 3.75 per cent, with governor Andrew Bailey saying that Middle East-driven energy prices have had a “limited effect on price and wage setting in the UK”, suggesting that the labour market remains soft.
China presents a clearer contrast. On Sep 20, its benchmark lending rates were kept unchanged for a 16th consecutive month. Weak household and corporate credit demand persists even as AI and advanced manufacturing strengthen industrial production.
The price of money
The emerging monetary divide is therefore not simply between the hawks and doves.
It is between economies where inflation requires demand to be restrained, economies where demand remains too weak to justify tightening, and a difficult middle group where central banks must judge whether an inflation shock will persist.
Public debt changes the stakes even more. Governments accumulated enormous debts during the era of exceptionally low rates. As these debts are refinanced, higher rates increase interest expenditure and governments’ preference for cheaper money.
Central banks are therefore being required to demonstrate their independence, precisely when governments can least afford higher rates.
But raising rates is not itself proof of independence. The real test is whether monetary policy responds to inflation and economic conditions rather than becoming constrained by government financing needs.
Japan is especially revealing: one of the world’s most indebted governments has not prevented the BOJ from tightening when it judges that price stability requires it.
Nor does holding policy rates necessarily mean financial conditions are easing.
The UK’s 30-year government bond yield, for example, hovered around 5.7 to 5.9 per cent in the past month, touching multi-decade highs.
Long-term bond yields can remain elevated as investors demand compensation for inflation and fiscal risk, while governments and technology companies compete for global savings.
Pressures outside borders
Elsewhere, when emerging economies decide on interest rates, they often do so with an additional external constraint.
India’s central bank decided to hold rates at its Aug 5 meeting. Data that came out in September, however, showed that August inflation rose to 4.82 per cent, above the RBI’s 4 per cent target, while the rupee has been pressured by global yields.
Indonesia held rates steady in August as well. But it had already hiked them by 1 per cent this year, partly to support its currency, which has weakened by 6.45 per cent against the US dollar in the year to date.
Higher advanced-economy rates can therefore push emerging-market central banks towards tightening – or postpone easing – even when domestic growth would prefer lower rates.
So we should watch not only who is or is not raising interest rates, but also why. In the new monetary order, that may tell us as much about the world economy as central banks’ interest rate decisions do.
The writer is a distinguished fellow at the Centre for Social and Economic Progress and former Asia-Pacific director at the International Monetary Fund
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

One-third of Singapore-listed firms at risk in severe AI downturn: MAS

‘Not done’: Keppel CEO Loh Chin Hua transformed the group, but says there’s ‘still a lot to do’

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

