Why Bessent’s bond buyback programme should worry us
The government isn’t retiring debt; it’s swapping expensive long-term IOUs for more short-term borrowing
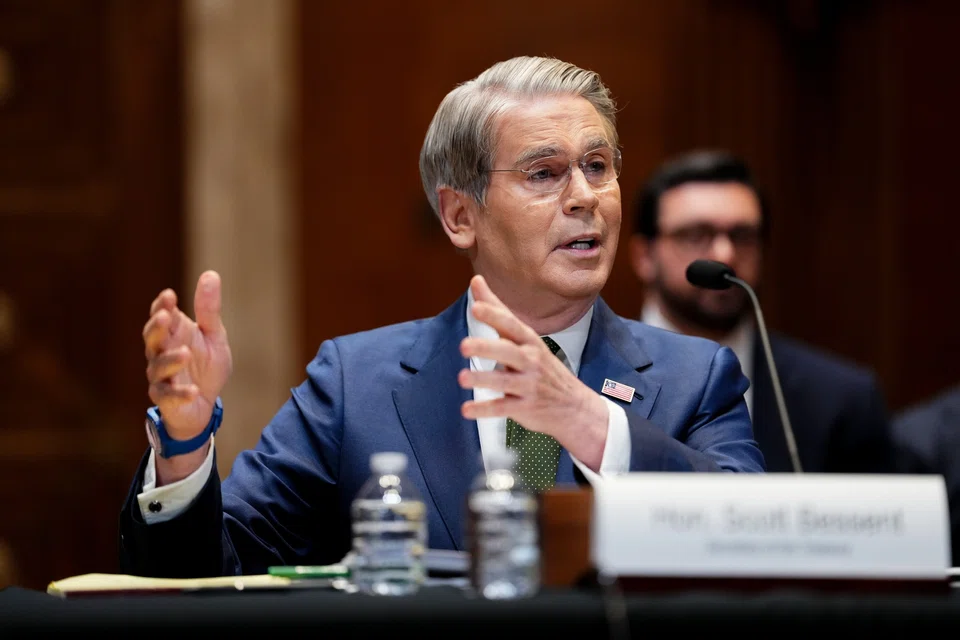
AUG 19 brought two pieces of news that belong in the same sentence, even if the US Treasury Department would rather they didn’t.
First, the country’s gross national debt crossed US$40 trillion, less than five months after passing US$39 trillion in March.
Second, in what one economist called a “surprise announcement”, the Treasury said it would increase the size of its government debt repurchases by “at least double”.
US Secretary of the Treasury Scott Bessent wants these to look like a coincidence of timing. They are not. They are two symptoms of the same disease, and the second is being marketed as the cure.
The sleight of hand
Start with what a “buyback” actually is. The government isn’t retiring debt; it’s swapping expensive long-term IOUs for more short-term borrowing.
That can be a legitimate liquidity tool for the thin longer-dated end of the market. But it still exposes the Treasury to fluctuations in interest rate risks, and is not an answer to a US$40 trillion balance sheet.
Yet the political framing has been almost the opposite. Bessent told reporters that “there’s nothing magic about the 40 trillion number, and we can grow our way out of that”, pairing the debt milestone with a buyback announcement clearly timed to reassure markets.
The rhetorical move is to let a bond market operation stand in for fiscal seriousness.
Small numbers in a big market
The numbers involved are mismatched to the problem they’re supposed to solve.
The Treasury’s purchases went from US$2 billion to at least US$4 billion at a time. These are sums that sound large, but are tiny in a market worth more than US$32 trillion.
Wall Street noticed immediately: analysts warned the impact would likely be short-lived. They were right: rates climbed back the following morning.
Indeed, a policy that can’t hold for 24 hours isn’t stabilising anything. It’s buying a news cycle.
Analysts are pointing out the flaws
It’s worth noting that the scepticism isn’t coming from partisan critics; it’s coming from the bond desks that actually have to price this debt.
Krishna Guha, vice-chairman of equities at Evercore ISI, dismissed the plan as “a weak form of Operation Twist”, a Federal Reserve move that swaps long-term debt for short-term liabilities.
He also warned that it “will have little enduring impact and could backfire” if investors read it as a sign that Washington is struggling to fund itself cheaply.
Thomas Simons, chief US economist at Jefferies, told Reuters that the surprise announcement upended Treasury’s tradition of consistent communication about “regular and predictable” debt issuance and felt like something that was “shot from the hip”.
Predictability is an essential quality, not a bureaucratic nicety, in sovereign debt markets. Undermining it to win a day of favourable headlines is a strange trade.
The historical precedent
Meanwhile, US debt is accelerating at a rate of about US$2 trillion a year, and Treasury’s own advisory panel, the Treasury Borrowing Advisory Committee, has warned of a US$1.45 trillion funding shortfall in fiscal years 2027-2028.
Steve Hanke, a monetary economist who served on President Reagan’s Council of Economic Advisers, put the tactic in its proper historical context.
“What he is trying to do is control the yield curve and keep those long-bond prices higher and the yields lower. But the problem is, if he buys them back, he still has to finance the deficit. So he is going to have to issue more of the short-term debt. Yield curve control is a fool’s game.”
A distraction, not a solution
Doubling a bond buyback programme while the debt burden rolls past US$40 trillion is not fiscal policy. It’s stagecraft dressed as intervention.
It worked for about one trading session. And it arrives instead of, not alongside, the fiscal consolidation plan officials keep promising is just around the corner.
If the administration wants markets and the public to believe it’s serious about the debt, a bigger buyback number is the wrong place to start.