

Does diversification still work? Market concentration raises challenges
Due to the surge in AI as a theme in public equities, fixed income and real assets, exposure risk is rising
IT IS often said that diversification is the only free lunch in investing. That is because by spreading your funds across asset classes, you benefit from lower risk without sacrificing returns.
Is that still true? Thanks to the surge in artificial intelligence as a theme – across public equities, fixed income and even real assets – concentration risk is rising and threatens to make diversification less effective.
If you have done nothing in the past few months, the strong performance of the AI and tech theme has likely skewed your strategic asset allocation towards equities, and technology in particular.
A 60/40 mix (60 per cent equities, 40 per cent bonds) may have become 80/20, for instance, making your portfolio vulnerable to market corrections.
These factors include structurally higher interest rates, regulatory restrictions on AI development, constraints on the build-out of data centres and so on. So far, higher yields, which usually exert pressure on equity valuations, have not dampened investors’ enthusiasm.
Ten-year Treasuries briefly crossed 5.27 per cent in recent days. The S&P 500 has risen more than 12 per cent in the year to date, and 21 per cent since end-March.
That AI would shape up to be most powerful and transformational driver of economies and businesses is not in dispute. Still, too much capital linked to the largest US stocks may court more volatility than some investors can handle.
The “tip of the iceberg”
Institutional investors are concerned, as leading global professional services firm Marsh found in its recent investment conference in Singapore.
Hooman Kaveh, executive chair of Marsh’s investment platform, said: “If you look at the AI theme in public markets, it might be about semiconductor companies, cloud computing and hyperscalers. But data centres are also in infrastructure and real estate investments.
“Then in venture capital, you have data companies, plus there is private equity. All that is a wake-up call for asset owners. If you look with the right tools, the AI exposure has been a real shock; the concentration risk in public indices is only the tip of the iceberg.”
In the Invesco Global Sovereign Asset Management survey of central banks and sovereign wealth funds, market concentration was cited the most significant risk in AI investments, followed by bubble and valuation risks.
Respondents reported reviewing “whether the diversification they assumed from broad market exposure is actually present”.
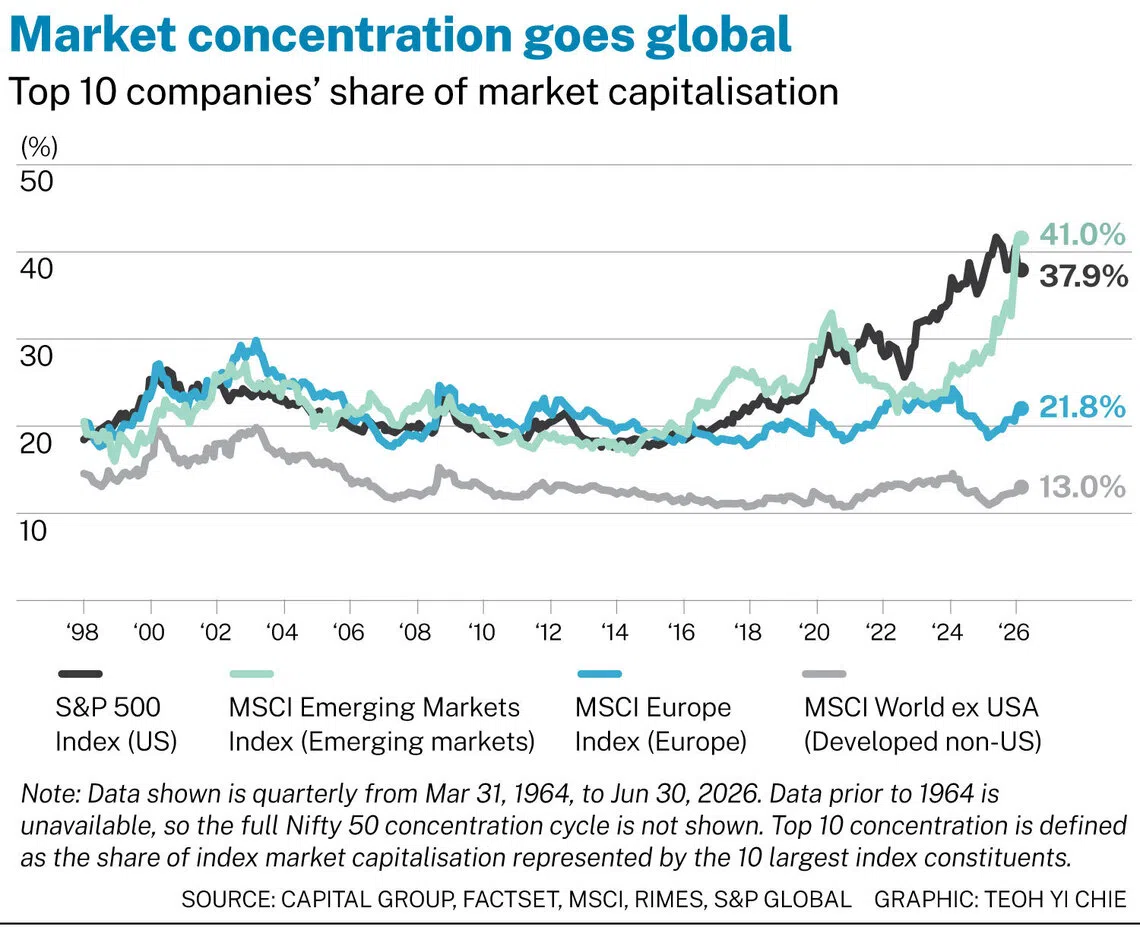
With the ubiquity of the AI theme, concentration has become a global characteristic of markets and earnings, Capital Group explained in an article.
In the US, AI investments account for nearly 39 per cent of real gross domestic product. The Magnificent Seven (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla) and other tech stocks account for more than 39 per cent of US capital expenditures and 42 per cent of earnings.
In South Korea, Samsung and Hynix’s share of earnings is more than 76 per cent, and in Taiwan, Taiwan Semiconductor Manufacturing Co alone accounts for 57 per cent.
Some active fund managers have begun to take a more defensive stance, a Morningstar article said, trimming some AI holdings and focusing on high-dividend payers and companies with lower debt.
Active funds typically have a concentration limit of 10 per cent on single securities.
By definition, index-tracking funds hold the entire market index. Capitalisation-weighted indices hold the largest companies. The 10 largest stocks comprise around 38 per cent of the S&P 500, and nearly 27 per cent of the MSCI World Index.
For risk mitigation, there appears to be few alternatives to diversification. But investors have to be vigilant; even fixed-income funds may have AI-related debt. Hyperscalers have become major issuers of investment-grade bonds.
Those in or near retirement should review their asset mix, and trim exposures back to their strategic weights.
Still early in the AI opportunity
Hou Wey Fook, DBS Bank’s chief investment officer, maintained that AI development and adoption will broaden over time, unlike markets and interest rates, which move in cycles.
He said: “We are still at an early stage, with AI set to find uses across almost every part of the global economy.”
The investment opportunity, he added, expands beyond semiconductors, chips and data centres, and includes companies providing infrastructure and putting AI to commercial use.
Endowus group chief investment officer Samuel Rhee noted that concentration is not unusual throughout markets’ history.
He said: “What makes this cycle feel exceptional is how compressed it is. Fast adoption, infrastructure investment and market repricing have happened in three or four years.
“In some ways it is exceptional. AI may be the first general-purpose technology that works on cognition itself, which really is a first in human history. So it is natural that markets are paying up for it.”
He added: “We don’t try to call the AI trade either way. You can’t remove a theme that runs through the whole of the US economy, which is the largest economy by far and thus the global economy. But you can make sure your exposure is deliberate and sized, rather than accidental.
“The bottom line is that the equity market is by definition a quality-weighted index of the best companies that are not only the most profitable, but are also likely to be the future winners of AI.”
For now, strategists say AI valuations are not excessive. Delwin-Kurnia Limas, Asia-Pacific head of technology at UBS Chief Investment Office, said that most AI stocks are trading at relatively reasonable multiples.
Semiconductors, he noted, have a forward price-to-earnings ratio of 22 times, below the peak of 33 times in June and more than 100 times at the height of the dotcom boom.
Earnings growth is expected to be robust – 46 per cent in 2027, after an estimated 107 per cent in 2026 based on consensus estimates.
“That said, mid-cycle digestion is a real risk, especially for 2028 capex, as it will need to be increasingly funded by equity/debt raises, along with vendor financing.
“Intensifying competition from open-weight models, rising political pushback on data centre builds and higher financing costs are among a few key risks to consider.”
Investors, he noted, should not divest from AI, but maintain a globally diversified portfolio.
“In our view, diversification remains the most effective way for investors to participate in the long-term AI opportunity, while managing the risks associated with concentration and volatility.”
He favours a barbell positioning – quality semiconductor and hardware names that benefit from AI infrastructure spending on one end, and on the other end, mega-cap tech platforms and defensive tech, which are expected to be more defensive if the AI capex boom fades.
Eli Lee, Bank of Singapore chief investment strategist, said that portfolios can appear diversified while remaining concentrated in the same underlying drivers of risks.
“While AI remains a compelling investment theme, we view it as one opportunity competing for capital within the overall portfolio, and evaluate it relative to other opportunities based on its contribution to the portfolio’s resilience and long-term outcomes.”
Bank of Singapore uses a “whole portfolio approach” in evaluating concentration risk. “Rather than focusing on individual holdings or asset class labels, we assess AI exposure through the lens of the total portfolio and its underlying economic risk exposures.
“We believe this approach is important in easing behavioural strain during volatility. When portfolios are understood as systems designed to operate across a range of conditions, rather than collections of holdings, decisions tend to be steadier and intent remains clearer.”
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check

