

Asia’s green transition: The next phase must also emphasise market building
The region's focus must go beyond scaling climate finance to fostering the ecosystem that deploys it
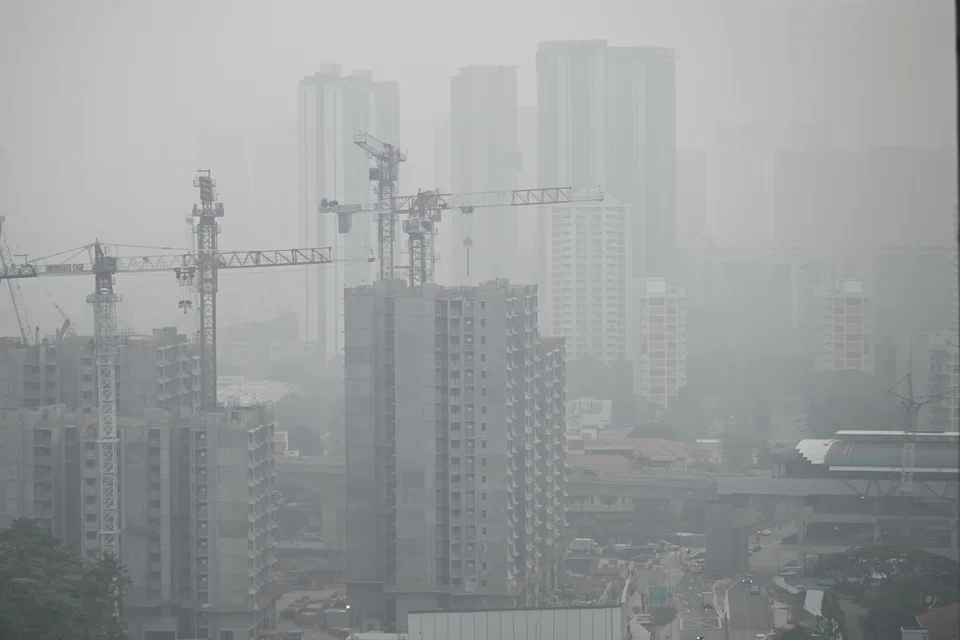
THE climate emergency is no longer something that is happening at some point in the future.
Catastrophic disasters – such as the forest fires in Indonesia that have brought thick polluting smog and haze to the region, and the devastating flash floods in Nepal – will occur with increasing frequency unless we dramatically accelerate our efforts to combat the accelerating climate breakdown.
In response, it is obvious that capital needs to flow into climate solutions at an exponentially faster rate – particularly to those countries that are most vulnerable to the impacts of climate change.
We have argued in these pages that closing South-east Asia’s climate finance gap would require more than good intentions. Almost one year on, the argument remains more relevant than ever.
The challenge is immense, yet there are reasons for optimism.
Investor appetite for projects across Asia continues to grow. Transition finance is gaining momentum, with new pools of capital emerging at pace and collaboration between public and private actors becoming stronger and more sophisticated.
The UK and Singapore have deepened their partnership through initiatives such as Financing Asia’s Transition Partnership (Fast-P), helping to catalyse investment into the region’s transition.
Despite this progress, an important challenge remains. The gap between available capital and investable projects remains too wide.
There is no shortage of investors looking for credible opportunities. The bigger constraint is the supply of projects that are ready to absorb capital at scale.
Across much of Asia, promising opportunities continue to stall because of project preparation challenges, fragmented regulations, inadequate risk allocation and a lack of common standards.
From capital to capacity
This is why the next phase of Asia’s transition cannot be focused solely on mobilising more private finance. It must also be aimed at building stronger markets and creating conditions that allow capital to flow efficiently at scale.
The UK-Singapore partnership offers an example of how this can be achieved.
Both countries bring complementary strengths to the table. The UK has a deep-rooted expertise in sustainable finance, investment mobilisation and market development. Singapore has established itself as one of the world’s leading financial centres and an increasingly important hub for climate innovation and transition finance across Asia.
Together, we are supporting not just individual investments, but the broader ecosystem required to attract long-term private capital.
Programmes such as Fast-P illustrate this approach. Going beyond financing, the initiative aims to build the frameworks, partnerships, and investment pathways that enable capital to move across borders and into transition opportunities throughout the region.
This is an important distinction. Markets that can consistently attract investment do not emerge accidentally. They are built through institutions, standards and platforms that create confidence for investors and lasting opportunities for businesses.
British International Investment’s (BII) own experience across emerging markets like India reinforces this lesson. Over many years of investing in climate-related sectors, we have learnt that capital is necessary, but it is rarely sufficient by itself.
Successful investments depend on enabling ecosystems.
Renewable energy projects require reliable regulation and grid infrastructure. Electric mobility requires charging networks, supportive policy frameworks, and consumer confidence. New technologies need demonstration projects that prove commercial viability and attract follow-on investment.
South-east Asia has the potential to achieve similar levels of market development. However, the region’s diverse markets will each follow their own path.
The lesson from India is not that there is a single model to replicate, but that a coordinated approach can create the conditions for private capital to participate at scale, make more projects bankable and accelerate the energy transition.
Key priorities ahead
The priority is developing stronger project pipelines. Many opportunities remain stuck at the early stages of development because project sponsors lack access to the technical expertise as well as feasibility studies and transaction support needed to reach investment readiness.
Greater investment in project preparation can significantly increase the number of bankable opportunities available to investors.
Through its US$1.5 billion British Climate Partners initiative, BII is putting this approach into practice, using platform equity to build and scale climate assets in India and South-east Asia.
Its first investment, North Star, is a US$300 million platform established with Copenhagen Infrastructure Partners to accelerate the development of renewable power projects in India, combining BII’s capital and market expertise with private investment.
Second, governments, development finance institutions (DFIs) and private investors need more effective mechanisms for sharing risk. Blended finance structures, guarantees and other risk-mitigation tools can help crowd private capital into sectors and markets that might otherwise be viewed as too challenging.
These instruments are especially important in emerging economies, where perceived risks often do not mirror on-ground realities. The Green Investment Partnership under Fast-P, for instance, helped de-risk its capital structure and attract further commercial investment into scaling mid-market green and sustainable infrastructure in Asia.
Third, greater alignment around standards and frameworks is crucial. Investors operate across multiple markets. Common approaches to areas such as sustainability disclosure, transition finance and impact measurement can reduce complexity, increase transparency, and improve capital allocation.
A more harmonised investment landscape would make it easier for capital to flow to where it is most needed.
Finally, Asia needs stronger regional investment platforms that can connect capital, expertise, and opportunities across borders. No single country can address the transition challenge alone.
Regional cooperation will be essential if markets are to achieve the scale required to meet climate and development goals.
Singapore’s upcoming Asean chairmanship in 2027 is hugely important. It presents an invaluable opportunity to move the conversation forward and drive the region’s energy transition and climate resilience on to new strengths.
The focus should not be only on the scale of climate finance available to the region, but on the quality of the systems that deploy it.
The stakes are high. Asean will play a decisive role in determining the pace and success of the global transition. The region has the capital, talent, and ambition required to lead. What it now needs is stronger market architecture capable of turning opportunity into action.
The next phase of the transition will depend on both capital mobilisation and market-building. If governments, DFIs and private investors work together to strengthen project pipelines, align standards and share risk more effectively, they can help transform climate ambitions into investable realities.
The goal is not simply to finance more projects. It is to build markets that can finance themselves over time.
If we get this right, Asean will not only participate in the global transition; it can also help define how transition finance markets develop for decades to come.
Nik Mehta is the British High Commissioner to Singapore; Leslie Maasdorp is CEO of British International Investment.
This essay is part of New Global Order, a series which explores how the changing world landscape is reshaping business, politics and beyond.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
The line between public servants and private property

