

CICT H1 DPU up 7.1% at S$0.0602, bolstered by CapitaSpring and Gallileo tower in Germany
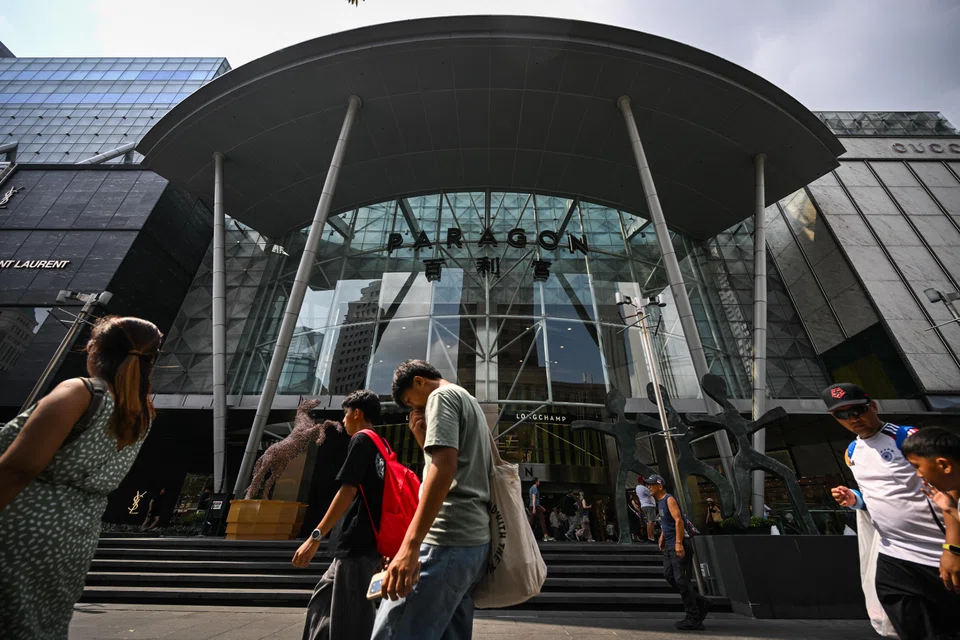
NPI rises 8.7% to S$630.5 million; contributions from Paragon seen as among income drivers for rest of year
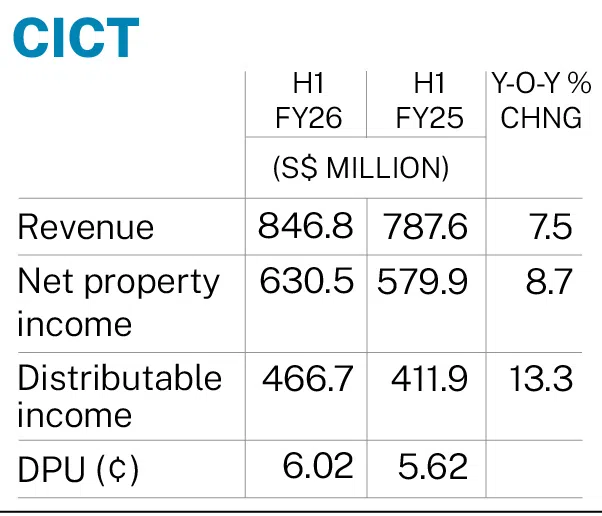
[SINGAPORE] The manager of CapitaLand Integrated Commercial Trust (CICT) on Wednesday (Aug 12) posted a distribution per unit (DPU) of S$0.0602 for the first half ended June, up 7.1 per cent from S$0.0562 in the year-ago period.
The DPU includes an advance distribution of S$0.0398 for the period from Jan 1 to Apr 28, which was paid on Jun 8. The remaining S$0.0204 will be paid on Sep 25, after the record date on Aug 20.
The DPU grew despite an enlarged unit base following a private placement to partially fund CICT’s acquisition of Paragon in April, it added, noting that this was supported by stronger operating performance and lower interest expenses. CICT’s unit base grew 5.8 per cent year on year to around 7.7 billion units.
Income growth was led by contributions from the commercial component of CapitaSpring – of which CICT acquired the remaining 55 per cent in August 2025 – and lease commencement at Gallileo in Germany following asset enhancement works. These partially offset the loss of income from the sale of Bukit Panjang Plaza in February this year.
Tan Choon Siang, CEO of the manager, expects the robust performance to continue for the rest of the year, supported by several income drivers.
These include contributions from the Paragon acquisition, which was completed on Jul 1; further lease commencements at Gallileo; continued positive rental reversions; and takings from Tampines Mall and Lot One Shoppers’ Mall following the completion of their upgrading works in the third quarter of 2026 and early 2027, respectively.
“Together with lower financing costs, these provide greater income visibility and support a strong growth outlook,” he said at the trust manager’s earnings briefing on Wednesday.
Based on the closing price of S$2.37 per unit on Jun 30, CICT’s annualised distribution yield is 5.1 per cent, said the manager.
Distributable income rose 13.3 per cent to S$466.7 million, from S$411.9 million in the year-ago period.
Revenue for H1 was up 7.5 per cent on the year at S$846.8 million, and net property income (NPI) grew 8.7 per cent year on year to S$630.5 million.
“Backed by a strong balance sheet and a diversified portfolio of high-quality assets, we remain well-positioned to navigate market uncertainties and deliver sustainable returns and long-term value for our unitholders,” Tan said.
Stronger rent reversion for suburban retail assets
Overall portfolio occupancy stood at 95.6 per cent as at Jun 30. Occupancy for the retail portfolio was 97.7 per cent, while the integrated developments and office portfolios recorded occupancies of 95.5 per cent and 94.4 per cent, respectively.
For H1, the retail portfolio recorded tenant retention rates of 83.9 per cent and positive rental reversion of 4 per cent. Reversion was stronger for suburban assets at 5.1 per cent, compared with 3.2 per cent for downtown assets.
The softer downtown rental reversion was largely attributed to specific assets undergoing asset enhancement initiatives, the manager said.
Overall rental reversion remains within the management’s mid-single-digit expectations, said Tan. He also highlighted that the resilient domestic economy, supported by gross domestic product growth and retail sales, should also provide a positive backdrop for retail spending.
Tenant sales rose 1.6 per cent year on year on a per-square-foot basis in H1, with both downtown and suburban malls recording growth. Performance was supported by seasonal promotions and new store openings.
Downtown sales remained positive despite softer tourist arrivals in Q2, while suburban malls continued to benefit from resilient domestic spending, said the manager.
On Paragon, Tan sees the medical block as offering the greatest upside, given the healthy rental reversions in the high single digits and its sizeable contribution of about 20 per cent of net lettable area.
British retailer Marks & Spencer recently renewed its lease at the Orchard Road mall for another three years.
Tan noted that, while the space occupied by department store Metro also presents potential upside, the extent remains uncertain given the potential downtime and reconfiguration required.
When asked if Hongkong Land could reposition Wheelock Place into a stronger competitor to Ion Orchard, which is part of CICT’s portfolio, he said that he does not expect a material impact. Hongkong Land’s Singapore private fund in July announced that it was buying Wheelock Place for S$1.1 billion.
He added that the two malls have long coexisted, and any rejuvenation of Wheelock Place could ultimately benefit Ion by enhancing the vibrancy and footfall of the broader Orchard Road precinct.
Office portfolio
For its office portfolio, CICT recorded positive rental reversion of 6.5 per cent and tenant retention rate of 70.8 per cent. Average rents rose to S$11.03 per sq ft per month as at end-June, from S$10.81 a year earlier.
Leasing momentum remained healthy, with major Q2 renewals and new leases including PGIM (Singapore) and Simpson Spence Young at CapitaSpring, and Cambiaso Risso Asia at Six Battery Road.
With German insurer Allianz set to vacate around 88,000 sq ft at CapitaSky upon its lease expiry in March 2027, CICT’s manager said that it is in discussions with prospective tenants, including some existing ones seeking to expand within the building.
On acquisitions, CICT remains focused on Singapore, noted Tan. While several office assets are currently on the market, increasingly competitive pricing could make deals harder to justify, and it will remain selective in evaluating opportunities, he added.
The trust’s sponsor, CapitaLand Investment, is said to have placed a formal bid for One Raffles Place at slightly more than S$2 billion in July.
In April, CICT sold Asia Square Tower 2 to Malaysia-listed IOI Group for nearly S$2.48 billion, and acquired Paragon for S$3.9 billion from Cuscaden Peak using funds from the Asia Square divestment.
As at Jun 30, 2026, CICT’s aggregate leverage stood at 37.4 per cent, down from 38.5 per cent as at Mar 31.
Its average cost of debt was stable at 2.9 per cent, with about 78 per cent of total borrowings on fixed interest rates. Its average term to maturity of debt was 4.1 years. Weighted average lease expiry was stable at three years.
CICT’s adjusted net asset value per unit was S$2.13 as at end-June, up 1.9 per cent from S$2.09 as at Dec 31, 2025.
Units of CICT closed 0.8 per cent or S$0.02 lower at S$2.49 on Wednesday.






